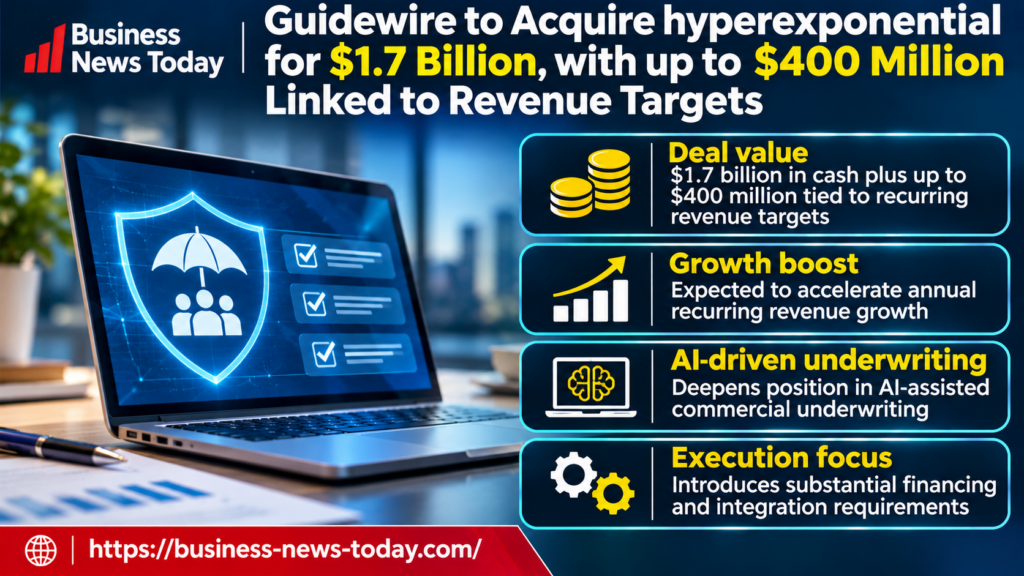
Guidewire Software, Inc. (NYSE: GWRE), the American technology supplier to property and casualty insurers, has signed a definitive agreement to acquire London-based hyperexponential for a base purchase price of $1.7 billion in cash, with up to another $400 million payable if specified recurring revenue targets are achieved. Announced on October 27, 2026, at Guidewire’s Connections conference in Las Vegas, the transaction could reach a maximum stated consideration of $2.1 billion before applicable adjustments. The acquisition will extend Guidewire’s software platform into AI-supported underwriting and pricing decisions across commercial and specialty insurance, building on an existing technology partnership between the businesses. Guidewire expects meaningful annual recurring revenue growth contributions, but the proposed transaction introduces financing, integration and execution risks that will be central to evaluating its long-term shareholder value.
Hyperexponential develops underwriting and pricing technology used by insurers, reinsurers and managing general agents. Its platform supports activities involving submission evaluation, risk assessment, pricing and portfolio decisions. According to the acquisition announcement, the technology has supported underwriting decisions associated with more than $75 billion in annual commercial property and casualty insurance premiums.
Guidewire Chief Executive Officer Mike Rosenbaum has framed the acquisition as a way to bring specialised AI-supported decision-making into a platform already widely used for insurance administration. Hyperexponential co-founder and Chief Executive Officer Amrit Santhirasenan has emphasised the value of combining pricing and underwriting insight with Guidewire’s policy and risk information.
The agreement is signed but the acquisition is not yet completed. Guidewire expects closing in the second quarter of its fiscal year 2027, subject to the relevant conditions. Until completion, hyperexponential remains a separate business and the projected financial benefits should be treated as management expectations rather than realised results.
What is hyperexponential’s underwriting technology and why does Guidewire consider it strategically valuable?
Commercial property and casualty insurance involves evaluating complex risks that can vary substantially between customers. Insurers may need to consider industry exposure, property characteristics, claims history, location, policy limits and specialised contractual terms. These inputs influence both whether coverage should be offered and the price required to support an acceptable underwriting return.
Hyperexponential develops software intended to help insurers convert information into pricing and underwriting decisions more efficiently. Its platform supports the evaluation of incoming submissions, application of models and assessment of portfolio implications. The company is positioning AI agents as tools that can assist specialists across several stages of the underwriting process.
Guidewire already supplies core systems used by insurers to manage policies, claims and billing. Its platform provides access to operational information accumulated throughout the insurance lifecycle. Combining that recordkeeping foundation with specialised underwriting software could allow customers to connect decision-making with the data underpinning individual policies and broader portfolios.
The strategic logic is that insurance systems become more valuable when they support consequential business decisions rather than only recording completed transactions. Better access to risk information could improve the speed and consistency of underwriting. However, those improvements depend on the accuracy and relevance of the data and the quality of the models used.
The combined offering will still need to preserve professional accountability. Underwriting decisions can involve substantial financial consequences and regulatory obligations. AI may help analyse information or recommend actions, but insurers must maintain appropriate controls over policy terms, pricing practices and the circumstances in which automation can make or influence decisions.
Hyperexponential’s technology is already available through Guidewire’s PartnerConnect ecosystem. That existing relationship may reduce some integration uncertainty compared with combining previously unrelated products. Nevertheless, operating as an independent partner is different from full ownership and deeper technical integration.
Why is the $75 billion premium figure important but not equivalent to hyperexponential revenue?
Guidewire says hyperexponential’s platform has supported underwriting decisions across more than $75 billion in annual commercial property and casualty insurance premiums. This demonstrates involvement in a financially important part of the insurance market and provides evidence that the technology is used by sizable insurance organisations.
The premium figure is not hyperexponential’s revenue. Insurance premium represents payments associated with coverage written by insurers, while a technology supplier generally earns licence, subscription or service revenue through different commercial arrangements. Treating the $75 billion figure as software sales would materially overstate the target’s financial scale.
Nor does the amount establish the value of every policy ultimately bound or the profit generated by the insurers using the technology. Underwriting decisions may include evaluated risks, submitted business and pricing activity, depending on the platform’s deployment. The disclosure should therefore be interpreted as a measure of the risk activity supported by the software rather than a direct financial statement.
Guidewire identified several established customers associated with hyperexponential, including Aviva, Allianz, Sompo, Beazley, Markel, HDI, Cincinnati Financial, Convex and Bowhead. The customer roster supports the target’s position in commercial and specialty insurance, particularly in the United Kingdom and international markets.
For investors, the more relevant valuation measures would include hyperexponential’s annual recurring revenue, growth rate, gross margin, retention and future cash generation. The announcement does not disclose a complete standalone profit and loss statement. That limits the ability to calculate an acquisition multiple based on earnings or free cash flow.
The consideration suggests that Guidewire places considerable value on hyperexponential’s growth prospects and strategic position. Whether the price is justified will depend on the recurring revenue and operating economics generated after closing.
How does the $1.7 billion cash price differ from the potential $2.1 billion maximum transaction value?
The transaction involves two components. The first is a $1.7 billion base cash payment, subject to customary adjustments. The second is contingent consideration of up to $400 million tied to specified recurring revenue targets.
If the contingent conditions are fully achieved, total stated consideration could reach $2.1 billion. That is approximately 23.5% above the base purchase price. However, the additional payment is not guaranteed and should not be presented as an unconditional liability of the same amount at signing.
The structure aligns part of the sellers’ consideration with future commercial performance. Guidewire may benefit if recurring revenue grows sufficiently to justify a larger payment, although strong performance could also trigger additional cash obligations. The net economic impact will depend on how much profit and cash flow accompany that revenue.
The precise targets and timing associated with the contingent consideration have not been disclosed in the announcement. Therefore, investors cannot reliably estimate the probability or expected value of the additional payment from the published terms alone.
The base transaction is itself significant for Guidewire’s capital allocation. It involves deploying substantial financial resources into an adjacent software category with the aim of generating faster recurring revenue growth. The decision must be compared with alternative uses of capital, including internal development, smaller acquisitions and shareholder returns.
A larger product portfolio may improve competitive positioning, but the purchase price makes execution particularly important. Integrating the business without retaining its customers, technical staff and development momentum would weaken the economic justification for the transaction.
How will Guidewire finance the acquisition, and what does $1 billion of new borrowing mean for shareholders?
Guidewire expects to finance the acquisition through $1 billion of new term-loan borrowing combined with existing cash. Bank of America and Citibank have provided binding debt commitments supporting the proposed financing. This gives management a defined funding route but also changes the company’s prospective financial structure.
Borrowed funds create interest and repayment obligations that must be considered alongside the acquired business’s earnings contribution. The transaction announcement does not disclose the final interest rate, amortisation schedule or complete post-closing balance sheet. Therefore, the annual financing cost cannot be calculated reliably from the principal amount alone.
Using existing cash reduces liquidity available for other purposes. The exact amount ultimately deployed will depend on transaction adjustments and the final funding structure. Management must balance the acquisition’s strategic benefits with ongoing investment needs across Guidewire’s core software and cloud operations.
The company has also announced share repurchase programmes during 2026, including a $500 million authorisation in January. An acquisition financed partly with cash and debt introduces a different capital allocation priority. Investors will need to evaluate whether the expected growth from hyperexponential provides a better return than alternative uses of those resources.
Guidewire expects the acquisition to remain consistent with its long-term margin targets. This is an important management commitment because acquiring a rapidly expanding software business can affect operating expenses, research spending and integration costs. Strong recurring revenue growth does not automatically create stronger free cash flow in the near term.
The financial implications will be clearer after closing, when management reports the acquisition’s accounting treatment, cash deployment and financing arrangements. The cost of borrowing and the performance of the acquired business will jointly influence the return on the transaction.
Why is Guidewire forecasting 650 basis points of additional recurring revenue growth in fiscal 2027?
Guidewire expects hyperexponential to contribute at least 650 basis points of inorganic annual recurring revenue growth during fiscal 2027. In percentage terms, 650 basis points equals 6.5 percentage points. This is a contribution to the company’s reported recurring revenue growth rate associated with the acquisition, not a forecast that the target will generate 650% growth.
Starting in fiscal 2028, Guidewire expects the transaction to contribute at least 150 basis points, equivalent to 1.5 percentage points, to durable organic annual recurring revenue growth. That outlook suggests management expects the benefits to extend beyond simply consolidating an acquired revenue base.
The distinction between inorganic and organic growth is important. Acquiring a business can increase reported annual recurring revenue immediately upon consolidation, while organic growth requires expansion from the combined operating platform over time. Investors will need to determine whether growth continues after the initial acquisition effect has been absorbed.
The forecasts provide a measurable basis for later assessment. If Guidewire reports higher recurring revenue but fails to achieve its anticipated contribution, the acquisition’s financial rationale may weaken. If the combined business generates stronger organic expansion while maintaining margins, it would provide more substantial support for the strategy.
The company expects no impact on its previously issued first-quarter fiscal 2027 guidance because the transaction is not anticipated to close within that period. Updated guidance for the second quarter and full fiscal year is expected with the next earnings release in December.
The credibility of these growth targets will depend on integration execution, customer demand and the ability to expand hyperexponential’s technology across Guidewire’s existing insurance relationships. The targets remain forward-looking and are not guaranteed outcomes.
Can AI underwriting tools improve insurer loss ratios, or will automation introduce new risks?
The acquisition’s strategic value is based partly on the potential to improve insurance underwriting decisions. The loss ratio, which compares claims and related costs with earned premiums under a given definition, is a central measure of underwriting performance. More accurate risk assessment and pricing may help insurers avoid policies whose expected losses are inadequately reflected in premiums.
AI tools can assist by processing large volumes of information, identifying patterns and applying models more consistently. They may also reduce the time needed to respond to submissions, allowing underwriters to evaluate more opportunities. These operational advantages can be commercially meaningful in competitive specialty markets.
However, speed alone does not establish better underwriting. Automated decisions may be affected by incomplete data, biased historical patterns or inaccurate model assumptions. Errors can result in underpricing risk, rejecting profitable customers or creating compliance problems.
The company’s preferred language of agentic underwriting describes software that can assist with actions across an underwriting workflow. That does not eliminate the need for professional judgement and governance. Insurers will need to determine which decisions can be automated and which require human review.
Implementation may also involve substantial data integration work. Existing pricing models, regulatory requirements and policy administration systems vary between insurers. A successful product must support those differences without forcing customers into inappropriate standardisation.
Guidewire’s opportunity is to combine the acquired platform with established insurance administration capabilities. The strongest evidence of success would be customer deployments showing faster processing, consistent pricing and improved underwriting outcomes. The transaction announcement does not provide a controlled study proving that every deployment produces those benefits.
How should GWRE investors assess the acquisition’s effect on profitability and valuation?
Guidewire is committing substantial capital to a software business with technology closely connected to its existing customer base. The purchase offers a potential route to faster recurring revenue growth and a stronger position in commercial insurance underwriting. Those advantages could support valuation if management meets its targets without sacrificing profitability.
At the same time, the transaction introduces additional borrowing, cash expenditure and integration risk. The maximum stated consideration is materially higher than the base price, while the target’s standalone earnings and cash-flow characteristics have not been fully disclosed. This limits the precision of any immediate valuation calculation.
The October 27 announcement comes ahead of Guidewire’s expected fiscal 2027 second-quarter closing period and a December financial guidance update. These events provide a sequence for assessing transaction progress and the costs associated with integration.
An optimistic investor interpretation would emphasise the target’s established customer relationships, the $75 billion premium activity supported by its software and the forecast contribution to recurring revenue growth. A more cautious assessment would focus on the acquisition multiple, debt financing and the possibility that projected AI-related growth requires greater expenditure than anticipated.
The next practical milestones will be transaction closing, disclosure of the final purchase accounting and the publication of updated financial guidance. Subsequent reporting should establish the acquired business’s actual contribution to recurring revenue, operating margins and cash generation.
Guidewire is making a significant strategic move into underwriting decisions that sit alongside its established policy administration systems. Its long-term value will depend on whether combining the platforms improves customer outcomes and generates recurring revenue at returns sufficient to justify the acquisition price.
What are the key takeaways from Guidewire’s hyperexponential acquisition agreement?
- Guidewire signed a definitive agreement on October 27, 2026, to acquire London-based hyperexponential.
- The base purchase price is $1.7 billion in cash, subject to adjustments.
- Up to $400 million in additional consideration depends on specified recurring revenue targets.
- Maximum stated consideration is therefore approximately $2.1 billion.
- hyperexponential’s technology has supported underwriting decisions involving more than $75 billion in annual commercial insurance premiums.
- The target serves established insurance customers including Aviva, Allianz and Beazley.
- Guidewire expects to use $1 billion of new term-loan financing alongside existing cash.
- The company forecasts at least 650 basis points of inorganic recurring revenue growth contribution in fiscal 2027.
- Closing is expected during Guidewire’s second fiscal quarter of 2027, subject to conditions.
- Integration, financing costs and the ability to sustain organic recurring revenue growth will determine the transaction’s financial return.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.