



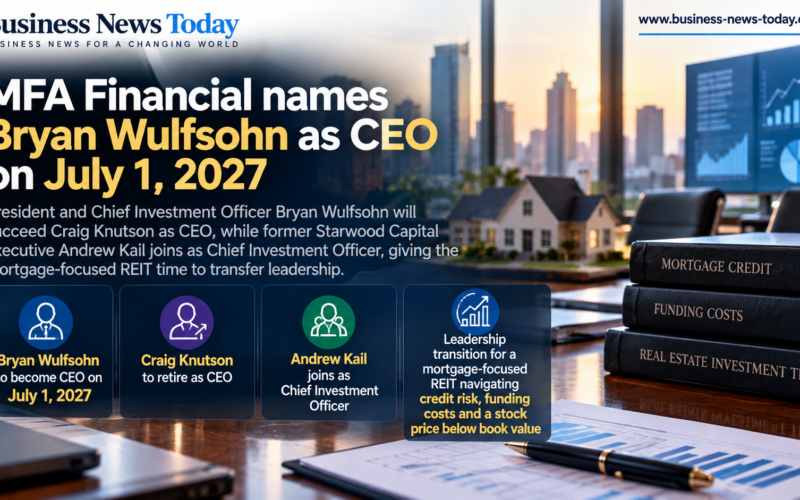
MFA Financial, Inc. (NYSE: MFA) has laid out a detailed executive succession plan nearly nine months before the Chief Executive Officer position changes hands, appointing Bryan Wulfsohn to succeed Craig Knutson on July 1, 2027. Wulfsohn, currently President and Chief Investment Officer, will join the board on January 1 before taking the top executive position six months later.
Knutson, 67, will retire as Chief Executive Officer on June 30 after approximately a decade leading the company and is expected to remain on the board. MFA Financial is simultaneously bringing in Andrew Kail as Senior Vice President and Chief Investment Officer from January 1, creating an extended period in which the next Chief Executive Officer, outgoing Chief Executive Officer and incoming investment chief can work together.
The measured transition is notable because MFA Financial operates in a business where leadership decisions are tightly linked to portfolio risk. As an internally managed mortgage real estate investment trust, the company invests in residential mortgage assets whose economics depend on interest rates, credit performance, funding conditions and housing-market behaviour. A rushed succession could therefore create considerably more risk than at a simpler operating company.
Why is MFA Financial announcing its next CEO so far in advance?
The timeline appears designed around continuity. Knutson joined MFA Financial in 2008 and has served as Chief Executive Officer or Co-Chief Executive Officer since 2017, giving him extensive institutional knowledge across multiple interest-rate and mortgage cycles.
Wulfsohn is similarly familiar with the company. He joined MFA Financial in 2010, became Chief Investment Officer or Co-Chief Investment Officer from 2019 and has served as President since September 2024.
That makes the appointment a classic internal succession rather than a strategic break. The board is effectively transferring control to the executive already deeply involved in deciding what mortgage assets MFA owns, how those assets are funded and how portfolio risk is managed.
Announcing the change months early also gives investors transparency. Mortgage real estate investment trusts can be highly sensitive to funding and asset-value movements, so uncertainty around leadership could introduce an unnecessary additional risk factor.
The succession plan removes most of that uncertainty before Knutson actually retires.
Why is Andrew Kail’s appointment as CIO just as important as the CEO change?
Wulfsohn cannot continue indefinitely carrying both the Chief Executive Officer and Chief Investment Officer responsibilities after the transition. MFA Financial therefore needs an executive capable of taking responsibility for portfolio construction, asset selection and funding strategy.
Kail brings more than 25 years of mortgage-finance experience and most recently worked at Starwood Capital Group as Managing Director and Head of Residential Lending. That background makes his arrival particularly relevant because MFA Financial has increasingly built capabilities around residential whole loans and specialist lending.
The company’s strategy is not simply to own highly liquid agency mortgage securities. It invests across credit-sensitive residential assets and operates Lima One Capital, which originates loans for real estate investors.
Managing that portfolio requires expertise in credit underwriting, securitisation, housing markets and financing structures. Bringing Kail into the organisation six months before Wulfsohn becomes Chief Executive Officer creates time for him to understand the portfolio before assuming full investment leadership.
The structure also allows Wulfsohn to shift gradually from portfolio specialist to enterprise leader.
What financial position does Bryan Wulfsohn inherit?
MFA Financial reported second-quarter 2026 GAAP net income available to common stockholders and participating securities of $36.2 million, equivalent to $0.35 per basic common share. Distributable earnings were substantially lower at $12.2 million, or $0.12 per basic share, although distributable earnings before realised credit losses reached $36.7 million.
GAAP book value ended the quarter at $12.71 per common share, while the company’s non-GAAP economic book value measure stood at $13.20. MFA also reported $141.2 million of unrestricted cash and approximately $294.1 million of unpledged agency mortgage-backed securities.
The figures illustrate both resilience and complexity. Book value was broadly stable during the quarter, but realised credit losses weighed on distributable earnings. That leaves management balancing the need to generate attractive portfolio returns against the risk of pushing too far into higher-yielding credit assets.
Lima One Capital originated approximately $316 million during the quarter, up 44%, while MFA Financial securitised or re-securitised more than $800 million of loans. Management also reported resolving nearly $200 million of previously delinquent loans, lowering the portfolio-wide default rate to 7% from 7.8%.
Wulfsohn therefore inherits an organisation actively expanding origination while still managing legacy credit issues.
Why does the MFA stock price create pressure on the next leadership team?
MFA Financial shares closed at $6.88 on October 9 after falling 4.18% during the session. The stock has declined substantially from its 52-week high of $10.43 and trades at a large discount to the company’s most recently reported GAAP book value of $12.71 per common share.
A mortgage REIT trading materially below book value is effectively receiving a message from investors that the market places a discount on the portfolio, earnings durability, future book value or some combination of those factors. Closing that valuation gap will become one of Wulfsohn’s largest strategic challenges.
The dividend adds another layer. MFA Financial most recently declared a quarterly common dividend of $0.36 per share, substantially above second-quarter distributable earnings of $0.12 per share. One quarter does not determine dividend sustainability because mortgage REIT earnings can fluctuate considerably, but the gap inevitably attracts investor attention.
Management therefore needs to demonstrate that portfolio returns, credit performance and future distributable earnings can support shareholder distributions without steadily eroding book value.
The succession plan does not itself solve those issues. It does, however, place a portfolio specialist in the Chief Executive Officer role, suggesting the board wants investment strategy to remain at the centre of the company’s approach.
How do interest rates change the challenge facing MFA Financial?
Mortgage REITs operate at the intersection of asset yields and funding costs. When interest rates change sharply, asset values, borrowing expenses, refinancing behaviour and credit performance can all move simultaneously.
Higher rates can create attractive yields on newly originated loans but can also pressure borrowers and raise the cost of financing those investments. Falling rates may support asset values and refinancing but can reduce income on new investments or create prepayment risk.
This makes macroeconomic positioning unusually important for MFA Financial. Wulfsohn has spent years managing the portfolio through different rate environments, which likely contributed to the board’s decision to promote him rather than recruit an executive without direct investment experience.
Kail’s addition provides further depth. A Chief Investment Officer with residential-lending expertise can concentrate on asset-level decisions while the Chief Executive Officer manages capital allocation, financing, investor communication and organisational strategy.
That division of responsibility becomes increasingly valuable if mortgage markets remain volatile.
Is this succession about continuity or a new MFA Financial strategy?
Everything disclosed so far points primarily toward continuity. The incoming Chief Executive Officer has spent 16 years at MFA Financial, the outgoing Chief Executive Officer is expected to remain a director and the transition will unfold over several months.
That does not mean strategy will remain completely unchanged. Wulfsohn may place greater emphasis on particular asset classes, origination channels or capital structures once he holds final executive authority. The large gap between share price and book value also creates pressure to demonstrate how capital can be deployed most effectively.
The board has nevertheless avoided the uncertainty associated with an external turnaround appointment. MFA Financial is signalling that it believes the existing strategy can create value if executed well rather than requiring a wholesale reinvention.
Investors now have months to evaluate that proposition before Wulfsohn formally becomes Chief Executive Officer. For a financial company built around long-duration assets and carefully managed leverage, that deliberate pace may be one of the most important features of the succession itself.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.