
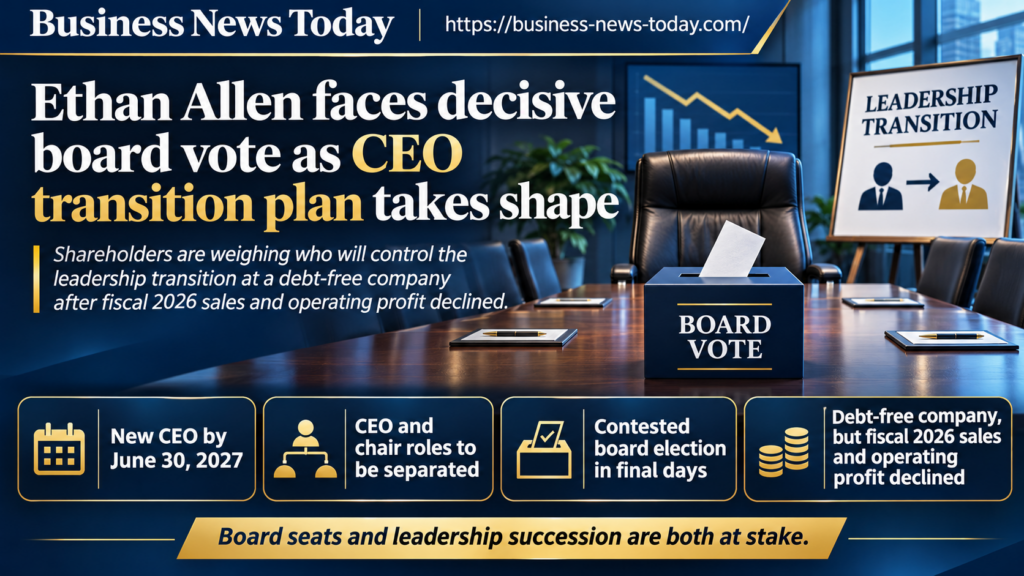
Ethan Allen Interiors Inc. (NYSE: ETD) has put a firm deadline on one of the most consequential leadership transitions in its recent history, saying a new chief executive will be announced by June 30, 2027 and that the CEO and chair positions will be separated after the transition. The commitment comes days before the November 4 annual meeting, where investor Doug Bergeron and DGB Investment are seeking to replace all five incumbent directors with an alternative slate and have proposed retail executive Stefanie Tsen Ward as an interim CEO candidate if their nominees are elected. Current Chairman and CEO Farooq Kathwari would move into a non-executive director role after his successor takes over and remain through the 2027 annual meeting before leaving the board under the company’s plan. The governance fight therefore centres on a more fundamental question than board composition: which directors should choose the next CEO and oversee the attempt to restore growth after fiscal 2026 revenue fell 5.7% and operating income declined more sharply.
Ethan Allen’s new CEO deadline turns a long-running succession issue into a measurable commitment
The October 30 announcement gives shareholders a specific endpoint that was previously less defined. Independent directors are leading the CEO search with an external search firm, and Ethan Allen says the successful candidate will also join the board. Separating the chief executive and chair positions would further change the governance structure by preventing the next CEO from automatically inheriting the authority currently concentrated in Kathwari’s dual role.
Kathwari would remain available during the handover as a non-executive director until the 2027 annual meeting. That structure preserves access to his operating knowledge while creating a date by which board leadership should become more independent of the outgoing chief executive. For a vertically integrated company that designs, manufactures, distributes and retails much of its own furniture, continuity has practical value because a new CEO will inherit responsibilities extending from factories and supply chains to design centres and digital customer acquisition.
The commitment also raises the standard against which the incumbent board can be assessed. June 30, 2027 is now a public deadline rather than an open-ended search, and shareholders will be able to judge whether the process produces an executive whose background matches the challenges visible in Ethan Allen’s financial results. A delay beyond that point or a succession that fails to improve growth would weaken the argument that continuity during the search was preferable to a more immediate leadership reset.
The November 4 proxy vote will determine who controls the CEO search rather than whether succession occurs
DGB Investment, Bergeron and related participants beneficially own approximately 5.2% of Ethan Allen’s outstanding shares and have nominated five directors, enough to replace the company’s entire five-member board if their slate wins. The activist group argues that the company needs faster leadership change and has identified Tsen Ward, a former Neiman Marcus integrated retail executive, as the person its nominees would recommend as interim CEO following the annual meeting.
Ethan Allen’s board opposes that approach and argues that installing an interim chief executive before conducting another search for a permanent leader would create an additional transition. Under the company’s plan, the existing independent directors would complete the search already underway and move directly from Kathwari to a permanent successor. Both sides therefore acknowledge that leadership change is required, but they differ materially over who should manage it and whether an interim step would improve or disrupt the process.
That makes the proxy contest unusually focused. Shareholders are not choosing between permanent retention of the current structure and leadership change because Ethan Allen has already committed to replacing Kathwari as CEO. They are choosing between two governance pathways for reaching that outcome, with potentially different implications for strategy, management continuity and the speed of operating changes.
Falling fiscal 2026 sales make the succession debate more than a corporate-governance exercise
Ethan Allen reported fiscal 2026 net sales of $579.5 million, down from $614.6 million in fiscal 2025 and $646.2 million in fiscal 2024. The two-year decline means the next CEO will inherit a business that has maintained unusually strong product margins but has not converted those economics into top-line growth.
Gross margin actually improved to 61.2% in fiscal 2026 from 60.5% a year earlier as cost of sales declined faster than revenue. Operating income nevertheless fell to $45.0 million from $62.0 million, reducing operating margin to approximately 7.8% from roughly 10.1%. Net income declined to $39.9 million from $51.6 million.
The figures explain why the succession discussion has attracted more attention than a normal retirement timetable. Ethan Allen is profitable and financially stable, so the next CEO is not being asked to rescue an insolvent or loss-making enterprise. The challenge is harder to disguise but potentially easier to finance: turn a high-gross-margin, vertically integrated furniture business back toward sustainable revenue growth without sacrificing the profitability and balance-sheet strength that remain important advantages.
Ethan Allen’s debt-free balance sheet gives the next CEO room to invest, but raises the return hurdle
Ethan Allen ended fiscal 2026 with $187.5 million of cash and investments and no outstanding debt. Operating cash flow reached $52.5 million during the year, giving the company substantial flexibility relative to its approximately $513 million stock-market value at the October 30 close.
That financial position means leadership change is unlikely to be constrained primarily by access to capital. Management can invest in marketing, digital tools, stores, manufacturing and customer acquisition without first repairing an overleveraged balance sheet. The more difficult capital-allocation question is whether those investments can generate enough incremental sales and operating profit to justify the spending.
Ethan Allen increased marketing expenditure by approximately 10% during fiscal 2026 and expects another roughly 15% increase during fiscal 2027. The board has highlighted online designer appointments, live chat and a 3D room planner as parts of its strategy for linking digital discovery with the company’s personalised interior-design model. Management has said customer spending is materially higher when shoppers work with an Ethan Allen designer, making digital tools valuable primarily if they move more consumers into that higher-conversion relationship.
The company also declared a $3 per share special cash dividend during August, demonstrating its willingness to return capital while continuing to fund growth initiatives. The next CEO will consequently inherit a shareholder base accustomed to meaningful cash distributions as well as demands for stronger growth, requiring a balance between reinvestment and capital returns rather than a simple choice of one over the other.
Digital execution has become central to the fight over Ethan Allen’s future growth model
Ethan Allen’s operating structure differentiates it from many furniture retailers because the company manufactures about three-quarters of its custom products in its own North American facilities and operates a network of design centres supported by in-house interior designers. That vertical integration can support customisation, quality control and gross margin, but it also creates a larger fixed operating system that needs enough sales volume to remain productive.
Digital commerce therefore cannot be treated as a separate online business. Ethan Allen’s stated strategy is to use digital channels to generate consumer interest and then connect customers with designers and physical locations where higher-value transactions can take place. The effectiveness of that model depends on customer acquisition costs, conversion rates and whether younger customers perceive the brand as relevant enough to begin the journey online.
The board is also evaluating potential future directors with experience in cybersecurity, artificial intelligence, supply chains or vertical integration. That list effectively identifies the capabilities Ethan Allen believes will matter during the next stage of the business. AI could improve product discovery, customer engagement and designer productivity, but technology investment will create value only if it increases sales or reduces operating friction rather than becoming another layer of spending around an unchanged revenue base.
A new CEO therefore does not need to dismantle the designer-led model to modernise the company. The stronger strategic opportunity may be to make Ethan Allen’s existing differentiated assets easier for customers to discover, configure and purchase while using technology to improve the economics of each designer relationship.
The timing of Ethan Allen’s earnings creates an unusual information gap around the shareholder vote
Ethan Allen’s annual meeting is scheduled for November 4, while fiscal first-quarter 2027 results are due on November 9. Shareholders will therefore cast the contested board vote five days before receiving the company’s next full quarterly financial update.
DGB has criticised that sequence, arguing that shareholders should have access to the latest results before deciding the board’s composition. The filing timetable itself does not establish why Ethan Allen selected November 9, and it would be inappropriate to infer that the company intentionally withheld results to influence the election without supporting evidence.
The chronology nevertheless increases the importance of the most recently available audited numbers. Investors voting on November 4 know that fiscal 2026 sales fell 5.7%, operating income declined about 27%, cash generation remained positive and the balance sheet carried no debt. They will not yet know whether the first quarter of fiscal 2027 shows evidence that increased marketing and digital investment are beginning to improve demand.
November 9 consequently becomes the first significant operating checkpoint after the governance decision. Whoever controls the board will quickly face fresh evidence about whether the existing growth programme is gaining traction or whether the CEO search needs to prioritise more substantial changes in merchandising, marketing, stores or operating strategy.
Ethan Allen shares show limited conviction ahead of the proxy contest rather than a dramatic activist premium
Ethan Allen shares closed at $20.36 on October 30, up 0.9% for the session and giving the company a market capitalisation of approximately $513 million. The stock was almost unchanged from its October 23 close of $20.45 and approximately 3.8% below the $21.16 closing price recorded on October 1.
ETD was trading within a 52-week range of approximately $18.28 to $25.26, placing the shares closer to the lower half of that range despite the company’s debt-free position. The valuation suggests investors recognise the balance-sheet strength but have not assigned a large premium to the current growth trajectory.
The contested election has attracted attention without producing a sustained activist-driven rerating. That may reflect uncertainty over which slate will prevail, but it also reflects the fact that changing directors does not automatically change consumer demand. Furniture remains a discretionary category exposed to housing activity, household formation and consumer confidence, meaning governance improvements still need to translate into better commercial execution.
The stock’s next larger move is therefore likely to require operating evidence rather than another round of campaign materials. A credible CEO appointment could improve confidence in the strategic direction, but revenue growth and operating-margin recovery would provide more durable validation.
What would make Ethan Allen’s CEO transition successful rather than merely orderly?
The first requirement is completing the search within the June 30, 2027 deadline while avoiding an extended period of executive uncertainty. A permanent successor needs enough authority to make decisions about product, digital investment, manufacturing, retail locations and capital allocation rather than functioning mainly as a caretaker for an established model.
Revenue provides the clearest operating measure. Fiscal 2026 sales of $579.5 million were about 10% below fiscal 2024 levels, so stabilising and eventually reversing that decline would show that marketing and customer-engagement investments are producing commercial results. Maintaining gross margin near recent levels while sales recover would make that growth substantially more valuable.
Operating margin is the second test because increased marketing cannot be justified indefinitely if it produces only modest revenue improvement. Ethan Allen needs the additional customer acquisition spending to create operating leverage rather than permanently resetting expenses at a higher level.
The November 4 vote determines who will oversee those decisions, while November 9 results provide the next evidence about the starting position. The June 2027 CEO deadline then creates the final governance checkpoint. By that stage, shareholders should know not only who is leading Ethan Allen but whether the new structure represents a genuine change in accountability rather than a change of title around the same growth problem.
Key takeaways from Ethan Allen’s CEO succession plan and November 4 proxy battle
- Ethan Allen has committed to announcing a new CEO by June 30, 2027.
- The company plans to separate the CEO and chair roles after the leadership transition.
- Farooq Kathwari would become a non-executive director following the CEO handover and leave the board at the 2027 annual meeting.
- DGB Investment and related investors own approximately 5.2% of Ethan Allen and are seeking to replace all five incumbent directors.
- DGB’s nominees intend to recommend Stefanie Tsen Ward as interim CEO if their slate gains control.
- Ethan Allen’s annual shareholder meeting is scheduled for November 4, with fiscal Q1 2027 results due November 9.
- Fiscal 2026 revenue declined 5.7% to $579.5 million and operating income fell to $45.0 million.
- Gross margin increased to 61.2%, showing that profitability pressure came despite resilient product economics.
- Ethan Allen ended fiscal 2026 with $187.5 million of cash and investments and no debt.
- ETD closed at $20.36 on October 30, leaving CEO selection, first-quarter results and eventual revenue recovery as the main measurable tests.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.