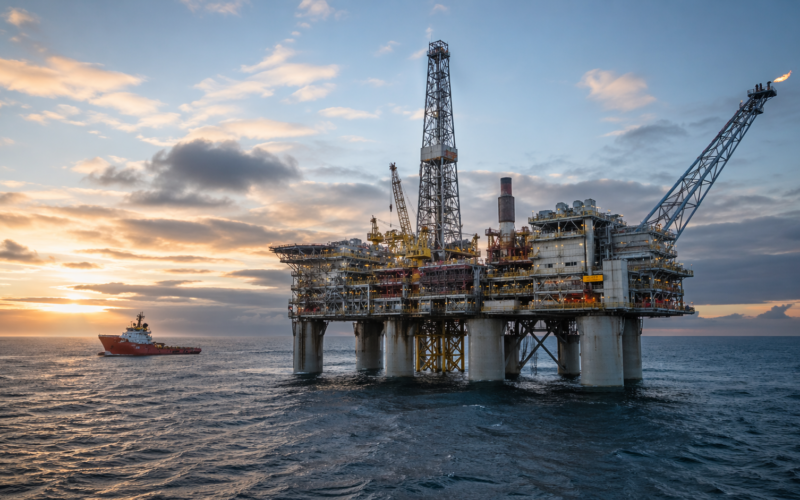
TotalEnergies SE, the State Oil Company of the Azerbaijan Republic and XRG have taken the final investment decision for full-field development of the Absheron gas and condensate field in the Caspian Sea, clearing the project’s most important commercial threshold and targeting start-up in 2029. The expansion is designed to lift total Absheron production capacity from the current 1.5 billion cubic metres of gas a year to 6 billion cubic metres annually, while condensate capacity is expected to rise from around 12,000 barrels per day to 47,000 barrels per day.
TotalEnergies holds a 35% interest and operates the development alongside SOCAR, which also owns 35%, and XRG, which holds the remaining 30%. The field lies approximately 100 kilometres southeast of Baku and contains around 140 billion cubic metres of recoverable gas reserves under TotalEnergies’ latest project disclosure. Phase one has been producing since 2023, providing the operating foundation on which the much larger full-field development will now be built.
The sanction moves Absheron beyond engineering preparation and into the capital-execution phase. That distinction is important because an offshore development can spend years progressing through reservoir appraisal, concept design, environmental review and front-end engineering without creating certainty that partners will commit the money required to build it. Final investment decision means the consortium has now authorised the project around an agreed development concept, opening the path for drilling, subsea installation, processing infrastructure, procurement and eventual commissioning.
How will the Absheron full-field development increase production?
TotalEnergies said the sanctioned development will produce gas through four subsea wells, with production transported to shore through a pipeline incorporating advanced automation. The hydrocarbons will then be processed in a new fully electrified plant designed to limit energy consumption and greenhouse-gas emissions. TotalEnergies is targeting Scope 1 and Scope 2 emissions intensity of less than 4 kilograms of carbon-dioxide equivalent per barrel of oil equivalent, unusually low for a large upstream gas project.
The design represents a considerable expansion from Phase 1. The initial development links one subsea producing well to gas-processing infrastructure connected with SOCAR’s existing Oil Rocks facilities and supplies roughly 150 million cubic feet of gas per day alongside around 12,000 barrels per day of condensate to Azerbaijan’s domestic market. Full-field development is intended to push the asset into a substantially larger production class rather than simply adding incremental output to the existing configuration.
At the planned 6 billion cubic metres per year plateau, Absheron’s gas capacity would be four times the nominal capacity of the original 1.5 billion-cubic-metre Phase 1. Condensate capacity would rise by close to four times as well. That production step-up explains why the final investment decision matters more economically than the earlier milestone of first production: Phase 1 proved the field, while full-field development is intended to monetise it at scale.
Where will the additional Absheron gas be sold?
The consortium plans to supply part of the increased production to Azerbaijan’s domestic market while exporting gas to Turkey through existing gas infrastructure that connects Azerbaijan with the wider European market. The ability to use established export networks reduces the need to create an entirely new international transportation system alongside the upstream development.
That infrastructure advantage gives Absheron strategic flexibility. Azerbaijan can allocate part of the field’s production to growing domestic requirements while using additional volumes to strengthen export flows. The combination is particularly valuable for a producing country seeking to maintain internal supply security without giving up the commercial benefits of international gas sales.
The project should nevertheless be viewed as an incremental addition to regional supply rather than a stand-alone transformation of the European gas market. Six billion cubic metres per year is meaningful at the level of Azerbaijan’s production system and bilateral export relationships, but the timing, contractual allocation and actual ramp-up profile will ultimately determine how much incremental gas reaches each destination after 2029.
Why did TotalEnergies, SOCAR and XRG choose this ownership structure?
The 35%-35%-30% structure spreads development exposure across three financially substantial partners while retaining TotalEnergies as operator. SOCAR provides the national-company participation and local infrastructure relationships that are fundamental to a major Azerbaijani offshore development, while XRG adds capital and an international gas-growth mandate backed by Abu Dhabi’s broader energy investment ecosystem.
For XRG, Absheron forms part of a wider strategy to build an international gas portfolio. The company said the project could unlock up to 5 trillion cubic feet of recoverable gas resources and characterised the investment decision as an important step in expanding its position in Azerbaijan and the Caspian region.
For TotalEnergies, the project fits a portfolio strategy that continues to allocate capital to hydrocarbon developments where the company believes cost and emissions intensity can remain competitive. TotalEnergies has highlighted Absheron’s electrified processing configuration and targeted sub-4 kg CO2e/boe operating intensity as important characteristics, signalling that project economics and carbon intensity are increasingly being considered together when large upstream developments compete internally for capital.
What does the 2029 start-up target mean for project execution?
A 2029 production target gives the consortium approximately three years from sanction to build out wells, subsea infrastructure, pipeline connections and the new processing plant. That is a substantial programme, particularly because multiple workstreams must converge before first gas rather than being completed independently. Drilling must align with subsea construction, pipeline readiness, onshore processing and commissioning schedules if the consortium is to avoid stranded infrastructure or idle wells.
The use of subsea wells and a shore-based electrified processing concept could reduce some offshore topside complexity compared with constructing a large new offshore processing installation. However, moving processing onshore does not eliminate execution risk. It shifts part of that complexity into long-distance production transportation, automation, power supply, plant construction and the interfaces between subsea and onshore systems.
The project therefore enters a period in which contract awards, fabrication progress and drilling performance will become more informative than additional resource estimates. Investors and contractors should watch for major engineering, procurement and construction packages, subsea-system awards, drilling campaigns and confirmation that the onshore plant remains aligned with the 2029 start-up timetable.
How is the market viewing TotalEnergies as Absheron moves ahead?
TotalEnergies shares in Paris closed at €78.10 on September 29, down 2.38% for the session after closing at €80.00 the previous day. That single-day movement should not be read as a market verdict on Absheron because the company’s shares are simultaneously responding to oil prices, refining conditions, portfolio decisions, shareholder distributions and broader equity-market factors.
Indeed, TotalEnergies had also been drawing investor attention around plans to increase shareholder distributions, including a larger fourth-quarter share buyback and continued dividend growth ambitions. The stock had risen following that broader capital-allocation update before giving back ground in the subsequent session, reinforcing the point that a field-level final investment decision is only one variable in the valuation of a diversified energy major.
From a project perspective, the useful investment signal is less about one day’s share-price response and more about the quality of capital deployment. Absheron offers a large existing resource base, infrastructure access, a proven producing first phase and an emissions profile that TotalEnergies expects to sit at the lower end of upstream gas developments. The remaining question is whether those advantages translate into disciplined construction and competitive returns once large-scale spending accelerates.
Why is the Absheron final investment decision more important than another project announcement?
The September decision removes the largest uncertainty that previously surrounded the field’s next phase. Absheron had already produced first gas, and engineering work had established a credible pathway towards larger development, but those steps did not guarantee that the three partners would sanction full-field expenditure. Final investment decision converts that pathway into an authorised project with a defined 2029 production objective.
It also clarifies the production scale. Current company guidance now points to approximately 6 billion cubic metres of gas a year and 47,000 barrels of condensate per day, supported by four subsea wells and a new electrified onshore processing plant. Those numbers provide contractors, infrastructure operators, customers and investors with a far clearer basis for judging Absheron’s commercial significance than earlier development concepts.
The next story will therefore not be whether Absheron might proceed. It will be whether the consortium can turn a sanctioned Caspian gas development into four times the current gas capacity by 2029 while maintaining the low-cost and low-emission characteristics TotalEnergies is using to justify the investment.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.