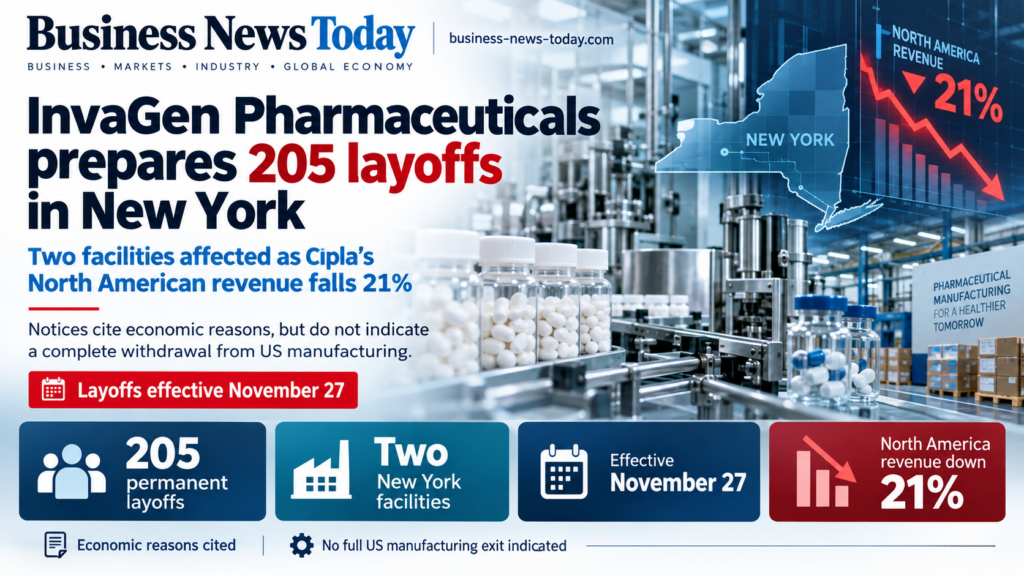
(Updated October 12, 2026, to include Cipla Limited’s official statement.) Cipla Limited (NSE: CIPLA; BSE: 500087), the Mumbai-based pharmaceutical group, faces a significant workforce reduction at US subsidiary InvaGen Pharmaceuticals Inc. after New York WARN disclosures identified 205 permanent layoffs in Suffolk County. The notices cover 160 employees at InvaGen’s Central Islip location and another 45 at its Hauppauge site, with both actions scheduled to become effective November 27 and the stated reason classified as economic. The filings describe layoffs rather than facility closures, an important distinction because InvaGen remains a material Cipla subsidiary and the wider US organisation continues to operate. The workforce action arrives after Cipla’s North America revenue fell 21% year over year in the first quarter of fiscal 2027, contributing to a sharp contraction in group profitability despite record revenue from India.
Cipla’s North America business generated approximately ₹1,532 crore, or $162 million, of first-quarter sales, compared with a much stronger prior-year period. The decline reflected lower contribution from mature high-value products and supply disruption affecting lanreotide, while the group is trying to rebuild growth through respiratory products, peptides and future launches. Cipla has now provided an official explanation for the workforce reductions, emphasising its continued commitment to the United States and its strategic shift towards complex and specialised pharmaceutical products. The company has not identified specific products or manufacturing activities affected by the 205 job reductions.
In a statement shared with Business News Today, Cipla said:
“Cipla remains firmly committed to the US, having invested over USD 1 billion in the past decade and continuing our investments by adding two sites in the last two years. These workforce adjustments are a part of a strategic realignment as we sharpen our focus on complex and specialized products to position the business for sustainable, long-term growth.”
Cipla’s statement reinforces the distinction between workforce reductions at specific facilities and a broader withdrawal from the US pharmaceutical market. InvaGen remains involved in portfolio development and licensing, while the wider group continues preparing new respiratory and oncology opportunities for the American market. The workforce reductions are consistent with the strategic realignment described by Cipla, although the company has not detailed how these adjustments will affect the future operations of its two New York facilities.
Why are 205 InvaGen jobs being cut when Cipla still considers the United States strategically important?
The US pharmaceutical market remains commercially significant for Cipla even after the recent revenue decline. Complex generics, respiratory medicines and differentiated products can produce margins that are difficult to replicate in conventional commoditised generics, making North America important to the group’s longer-term portfolio. The challenge is that the revenue contribution from individual high-value products can decline sharply when exclusivity erodes or competitors enter.
That volatility creates pressure to align manufacturing and labour costs with the next generation of products rather than the historic portfolio. InvaGen’s Long Island operations have been part of Cipla’s US manufacturing footprint, but a facility and workforce configured around an earlier product mix may require substantial adjustment when volumes change. The WARN notices cite economic factors without specifying which operating decisions drove them.
Cipla also retains manufacturing and commercial operations elsewhere in the United States. That makes it important not to convert the Long Island layoffs into a claim of broad US withdrawal. The more credible interpretation is that Cipla is trying to improve the economics of its American footprint while continuing to build selected growth assets.
How does the 21% North America revenue decline change the context around InvaGen’s layoffs?
North America revenue fell to approximately ₹1,532 crore in the June quarter, down 21% year over year, creating a significant drag on group profitability. Cipla’s consolidated net profit fell 39% to roughly ₹789 crore and EBITDA declined 33% to about ₹1,192 crore, while EBITDA margin contracted to 16.7% from 25.6% in the prior-year quarter. Those movements illustrate how much profitability can change when high-margin US products weaken.
The comparison was difficult because the prior year included stronger contributions from products such as lenalidomide and lanreotide. Lenalidomide economics have been changing as the generic opportunity matures, while lanreotide supply was disrupted after regulatory issues affected a supplier. That means some of the decline is product-cycle specific rather than evidence of a uniform collapse across the entire American portfolio.
Still, management cannot assume every lost dollar returns. A healthier US business needs new products capable of replacing declining contributions while its fixed manufacturing and commercial cost structure remains aligned with realistic volumes. The 205 layoffs add tangible evidence that the cost side of that adjustment is now affecting employment.
Why should the New York layoffs not be interpreted as a complete InvaGen shutdown?
New York’s WARN data classifies both actions as permanent layoffs rather than plant closures. Central Islip accounts for 160 affected workers and Hauppauge for 45, but the filings do not say that the entire facilities are being permanently shut. That is materially different from a WARN filing explicitly classified as a closure.
Cipla’s latest annual reporting also continues to identify InvaGen Pharmaceuticals Inc. as a material subsidiary incorporated in New York. The group has continued operating and recruiting selectively across its US network, reinforcing the need to treat the workforce action as location-specific rather than a complete exit from domestic US operations.
That distinction matters for both employees and investors. A partial workforce reduction can still significantly alter manufacturing capacity, shift production between sites or change the economics of particular product lines, but it does not necessarily eliminate the strategic value of the subsidiary.
How does Cipla’s future US pipeline complicate the decision to reduce InvaGen employment?
Cipla is trying to replace older profit drivers with a new portfolio spanning respiratory therapies, complex generics, peptides and biosimilar opportunities. That transition can create a mismatch between current manufacturing needs and future product requirements because different dosage forms and technologies require different equipment, quality systems and specialist skills. Reducing employment in one part of the network can therefore occur simultaneously with investment or recruitment elsewhere.
One example is Cipla’s expansion into a future pembrolizumab biosimilar opportunity through InvaGen’s licensing relationship with Qilu Pharmaceutical. The asset remains a future development and commercial opportunity rather than an immediate source of US earnings, but it illustrates that InvaGen continues to have strategic relevance beyond existing manufacturing volumes. Commercialisation responsibilities can also differ substantially from the manufacturing labour requirements of older generic products.
The broader issue is timing. Cipla needs to absorb declining contributions from mature products before newer respiratory, peptide and biologic opportunities reach meaningful scale. Workforce and manufacturing costs often need to adjust during that gap even if management remains optimistic about the longer-term market.
What does Cipla’s stock performance suggest about investor expectations for the US recovery?
Cipla shares closed at ₹1,301 on the NSE on October 9, down 0.44% for the session. The stock had fallen about 3% across the latest five trading sessions and approximately 4.6% from its September 9 close, while remaining within a 52-week range of roughly ₹1,166 to ₹1,673. That places the shares substantially below their annual high while still comfortably above the low.
The market is therefore already discounting some of the pressure on North American earnings. The workforce news is material locally, but the larger valuation question remains whether new product launches can restore regional sales and margins after the decline in older high-value assets. A successful recovery would reduce the strategic importance of any single generic product.
Investors should also distinguish between short-term earnings pressure and Cipla’s broader group performance. India revenue rose 12% to a record ₹3,452 crore in the first quarter, providing a strong domestic counterweight to the North American decline. That diversification gives Cipla more flexibility to restructure its US cost base without making the entire group’s growth dependent on an immediate American rebound.
What should employees and investors watch as InvaGen’s November 27 layoffs approach?
The first issue is whether Cipla provides additional detail on the future roles of the Central Islip and Hauppauge facilities. WARN notices establish the number of affected employees and timing but provide limited strategic explanation. Production transfers, capacity changes or facility investment would give a clearer indication of whether the cuts are primarily volume-related or part of a broader footprint redesign.
The second issue is North American sales progression in subsequent Cipla results. Management has expected sequential improvement from new launches and pipeline additions, making the next few quarters important for establishing whether the first-quarter decline represented a trough or a more persistent reset. Continued weakness would put greater pressure on costs and product launch execution.
The third issue is manufacturing quality and supply resilience. US pharmaceutical economics depend not only on regulatory approval but on keeping products continuously available, especially when high-value launches rely on limited manufacturing sources. Cipla needs a leaner cost structure without reducing operational resilience to a point where supply interruptions erase the savings.
The 205 InvaGen layoffs therefore sit inside a much larger strategic transition. Cipla is attempting to move from an American portfolio supported by mature high-contribution generics toward another generation of respiratory, complex generic and biologic opportunities while managing the inevitable earnings gap between them. For the affected New York employees the adjustment is immediate, but for Cipla the longer-term test is whether a smaller or differently configured manufacturing footprint can support stronger US economics rather than simply lower costs.
What are the key takeaways from InvaGen’s 205 New York layoffs and Cipla’s US reset?
- New York WARN disclosures identify 205 permanent InvaGen Pharmaceuticals layoffs effective November 27.
- The workforce reductions include 160 jobs in Central Islip and 45 in Hauppauge.
- Both filings cite economic reasons and classify the actions as layoffs rather than facility closures.
- InvaGen remains a material subsidiary of Cipla Limited and should not be described as exiting the United States.
- Cipla’s North America revenue fell 21% year over year to approximately ₹1,532 crore in the latest reported quarter.
- Group net profit fell 39% and EBITDA declined 33%, with US weakness contributing materially to the contraction.
- India’s business remained strong, with quarterly revenue up 12% to a record ₹3,452 crore.
- Cipla continues developing future US opportunities across respiratory medicines, complex generics, peptides and biosimilars.
- #CIPLA closed at ₹1,301 on October 9, around 4.6% below its September 9 level.
- The key strategic test is whether the workforce reset improves US economics without weakening manufacturing quality or the launch capacity needed for the next product cycle.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.