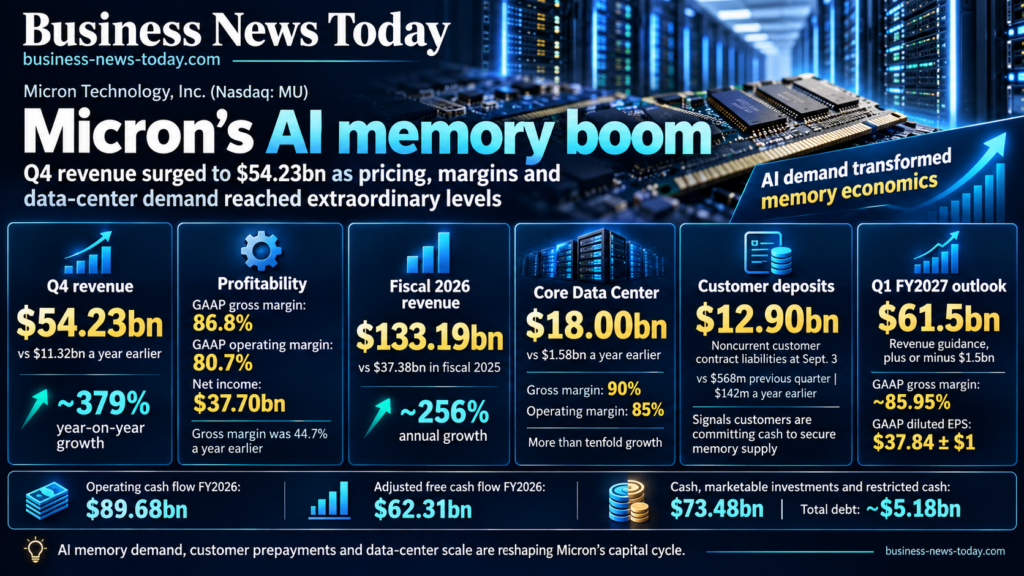
Micron Technology, Inc. (Nasdaq: MU) reported fiscal fourth-quarter 2026 revenue of $54.23bn, almost 4.8 times the $11.32bn generated a year earlier, as artificial-intelligence infrastructure demand produced extraordinary pricing and profitability across memory products. GAAP gross margin reached 86.8%, while GAAP operating margin was 80.7% and net income climbed to $37.70bn.
The year-on-year revenue increase calculates to approximately 379%, while fiscal 2026 revenue reached $133.19bn compared with $37.38bn in fiscal 2025. That represents annual growth of approximately 256%, illustrating how dramatically the memory cycle changed during the year.
Micron’s Core Data Center Business Unit generated $18.00bn of fourth-quarter revenue compared with $1.58bn a year earlier, an increase of more than tenfold. Gross margin within the unit reached 90% and operating margin was 85%, levels that would have appeared extraordinary for a commodity-sensitive memory business only a few years ago.
Management expects the momentum to continue into fiscal 2027, forecasting first-quarter revenue of $61.5bn, plus or minus $1.5bn. The guidance includes a GAAP gross-margin expectation of approximately 85.95% and GAAP diluted earnings per share of $37.84, plus or minus $1.
How extraordinary is Micron’s 86.8% fourth-quarter gross margin?
The year-earlier comparison demonstrates the scale of the change. Micron’s GAAP gross margin was 44.7% in the fourth quarter of fiscal 2025. It therefore expanded by more than 42 percentage points in twelve months.
Memory manufacturing historically moves through pronounced supply cycles. DRAM and NAND producers invest billions of dollars in fabrication capacity, but additional supply can depress prices rapidly when end-market demand weakens. Conversely, shortages can create exceptional pricing when capacity cannot respond quickly enough.
Artificial intelligence has altered the demand side because accelerators require enormous quantities of high-performance memory and data-centre storage. High-bandwidth memory is particularly important because GPUs and other accelerators need rapid access to large datasets while performing training and inference.
Micron’s figures indicate that the current market is not merely producing greater shipment volume. Pricing and product mix are allowing the company to retain an unusually high portion of revenue as gross profit.
Investors should still resist treating 86.8% as a permanent normal margin. Semiconductor supply eventually responds to high returns, customers seek alternatives and technology transitions can change competitive positions. The current economics demonstrate scarcity and product value; they do not eliminate memory cyclicality.
How important has the data-centre business become to Micron?
Core Data Center generated $18.00bn during the fourth quarter, equal to roughly one-third of total company revenue. That compares with just $1.58bn in the corresponding period last year.
Cloud Memory generated another $16.28bn, with an 83% gross margin and 76% operating margin. These are separate Micron business units, so the figures should not be combined indiscriminately with industry definitions that may group cloud and data-centre memory differently.
The shift shows why Micron is increasingly valued through the artificial-intelligence infrastructure cycle rather than through traditional PC and smartphone memory demand alone.
Mobile and Client still generated $13.11bn in the quarter, while Automotive and Embedded contributed $6.82bn. Both also delivered unusually strong margins, demonstrating that tight memory conditions and product improvements extend beyond hyperscale data centres.
The concentration of profitability around memory supply creates an important risk. Customers building vast AI clusters have strong incentives to secure capacity, but those same customers are sophisticated enough to redesign systems, negotiate long-term agreements and push suppliers toward future capacity expansion.
Micron’s competitive advantage therefore depends on maintaining leading technology while expanding supply without creating the oversupply that historically ended memory booms.
What do Micron’s customer deposits reveal about the AI memory shortage?
Micron’s balance sheet provides an unusually tangible sign of customer demand. Noncurrent customer contract liabilities reached $12.90bn at September 3, compared with $568m at the end of the previous quarter and only $142m a year earlier.
The cash-flow statement separately shows $12.75bn of proceeds from customer contract-liability deposits during fiscal 2026. These amounts should not be described as current revenue. A contract liability represents an obligation associated with consideration received before the corresponding revenue-recognition conditions have been satisfied.
Economically, however, customer deposits can strengthen Micron’s funding position by providing cash before future supply is delivered. They can also indicate that customers are willing to make significant commitments in order to secure memory capacity.
Micron’s management refers to Strategic Customer Agreements as a source of greater confidence in the durability of future performance. The precise economics can vary between individual contracts, and the balance-sheet liability should not automatically be equated with a fixed amount of guaranteed future profit.
The development nevertheless changes working-capital dynamics. Semiconductor producers historically financed expensive capacity expansions largely from their own cash flows and debt. Customer funding can shift some of the financial burden toward buyers seeking certainty of supply.
Can Micron fund the enormous capacity required by AI demand without stretching its balance sheet?
Fiscal 2026 operating cash flow reached $89.68bn. Micron reported $27.37bn of net capital expenditure and adjusted free cash flow of $62.31bn for the full year.
The company ended fiscal 2026 with $73.48bn of cash, marketable investments and restricted cash. Current and long-term debt totalled approximately $5.18bn at September 3, meaning the balance sheet looks dramatically stronger than during earlier downcycles.
Capital requirements are also enormous. Micron reported $30.71bn of property, plant and equipment expenditure before government incentives and other adjustments during the year, while management continues expanding technology and manufacturing capacity.
The distinction between capital expenditure and Micron’s non-GAAP adjusted free-cash-flow calculation matters. Investors should use the company’s defined measure consistently rather than combining GAAP investment figures with a non-GAAP cash metric without recognising the adjustments.
The broader conclusion remains clear. Current profitability gives Micron an extraordinary amount of internally generated capital with which to invest. The challenge is allocating it without assuming that today’s pricing environment persists forever.
Why did Micron shares ease after reporting extraordinary results?
Micron shares rose 3.03% to $1,097.39 on October 1, the first full trading session after the September 30 results, before declining 2.05% to $1,074.89 on October 2.
The two-day pattern demonstrates how elevated expectations have become. Revenue of $54.23bn and a $61.5bn next-quarter forecast would normally represent an extraordinary positive surprise, but Micron’s shares had already risen dramatically during 2026 as investors capitalised the AI memory shortage.
The key question has shifted from whether demand is strong to how long extraordinary pricing can remain strong. A business generating an 86.8% gross margin attracts investment from both existing suppliers and customers seeking alternatives.
Micron’s first-quarter fiscal 2027 guidance suggests management does not expect an immediate collapse. Revenue at the midpoint would rise another 13.4% sequentially from the already record fourth quarter.
That leaves investors confronting an unusual semiconductor valuation problem. Micron’s earnings are no longer merely recovering from a trough. They have moved into territory where the durability of margins, customer commitments and capital discipline may matter more than another quarter of spectacular revenue growth.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.