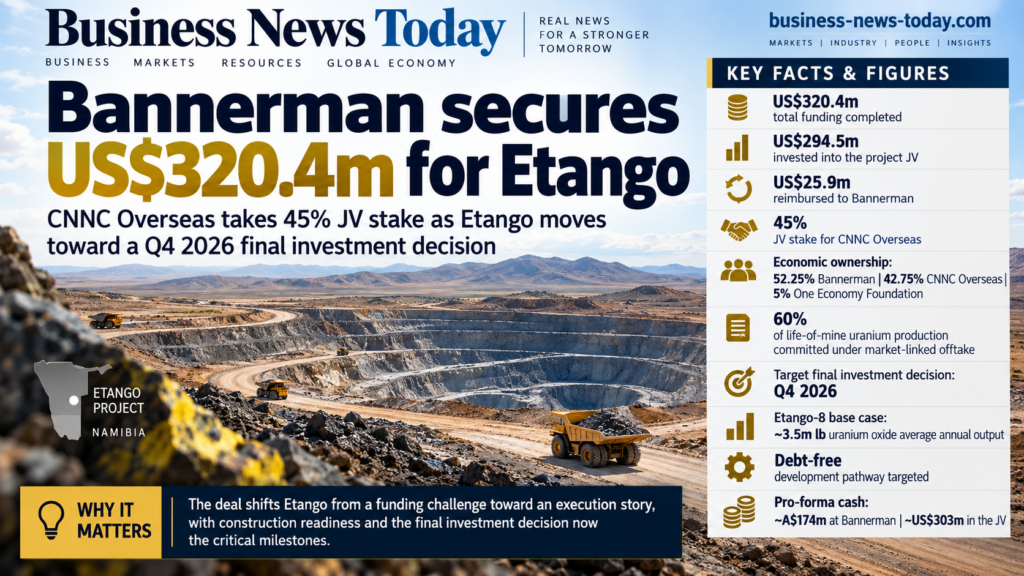
Bannerman Energy Ltd (ASX: BMN) has completed its landmark strategic financing and joint venture with CNNC Overseas Limited, receiving US$320.4 million to support development of the Etango uranium project in Namibia ahead of a targeted final investment decision during the fourth quarter of 2026.
The completed funding comprises US$294.5 million invested into the incorporated project joint venture and approximately US$25.9 million reimbursed directly to Bannerman Energy Ltd for eligible project expenditure. CNNC Overseas Limited is part of China National Nuclear Corporation’s uranium business and now holds 45% of the project joint-venture company.
Because the joint venture owns 95% of Etango and Namibia’s One Economy Foundation retains a 5% loan-carried project interest, the resulting economic ownership is approximately 52.25% for Bannerman Energy Ltd, 42.75% for CNNC Overseas Limited and 5% for the One Economy Foundation.
The financing is designed to allow Etango to advance without conventional project debt, materially reducing one of the largest risks historically associated with turning a development-stage uranium resource into an operating mine.
How does the US$320.4 million CNNC Overseas Limited transaction work?
The transaction is not simply a loan.
CNNC Overseas Limited has become a long-term equity partner at project level, funding its stake through the joint venture. Future project capital and operating requirements will generally be contributed 55% by Bannerman Energy Ltd and 45% by CNNC Overseas Limited through their interests in the joint-venture company.
Bannerman Energy Ltd retains governance control through three of five joint-venture board seats and three of five key executive positions, including the chief executive role. Certain major decisions, however, require unanimous approval, giving CNNC Overseas Limited meaningful protection over strategic matters including the final investment decision.
That structure allows Bannerman Energy Ltd to retain majority economic exposure while sharing both funding requirements and development risk with one of the world’s most important nuclear-fuel participants.
The trade-off is obvious. Bannerman Energy Ltd no longer owns the overwhelming majority of Etango economics. It has exchanged a large minority interest in the project for construction funding, a major customer relationship and significantly reduced dependence on debt markets.
Why does the 60% uranium offtake commitment matter?
CNNC Overseas Limited has agreed to purchase 60% of Etango’s life-of-mine uranium production at market-linked prices.
The pricing mechanism uses a combination of spot and term uranium indices and is subject to periodic review, rather than locking Bannerman Energy Ltd into a permanently fixed low price. Bannerman Energy Ltd retains the ability to market the remaining 40% of production.
That arrangement gives Etango an unusually strong connection between financing and future customers. For a uranium mine, contracted demand from a major nuclear-fuel buyer can reduce marketing risk and provide greater confidence that physical output will have a route to market.
The 60% commitment is nevertheless substantial. If future uranium prices rise dramatically, CNNC Overseas Limited will be entitled to a majority of production under the agreed market-linked mechanism rather than Bannerman Energy Ltd being able to market every pound independently.
The important distinction is that the offtake is market-priced rather than a deeply discounted financing arrangement. Bannerman Energy Ltd has argued that this preserves commodity-price exposure while providing strategic certainty around sales.
How close is Etango to construction?
Bannerman Energy Ltd has been targeting a final investment decision in the fourth quarter of 2026, with early works already progressing.
Etango holds its mining licence and environmental approvals, removing several significant regulatory hurdles. The existing Etango-8 definitive feasibility study is based on an eight-million-tonne-per-year processing operation producing an average of roughly 3.5 million pounds of uranium oxide annually under the study assumptions.
Separate expansion work has examined the potential for substantially higher production, including an approximately 6.7-million-pound annual scenario, although that should not be confused with the current base-case construction plan.
Bannerman Energy Ltd also completed a A$124 million underwritten placement on September 10 at A$4.00 per share. The company described that financing as an important final equity step ahead of the investment decision.
Following the CNNC Overseas Limited transaction, Bannerman Energy Ltd said its pro-forma corporate cash position was approximately A$174 million, while the joint venture had around US$303 million. Management considers the structure sufficient to fund its share of project working capital through commercial production under the current plan.
Is Etango really fully funded without debt?
The transaction creates a pathway to construct Etango without commercial project debt, but investors should distinguish that statement from a guarantee that no additional capital will ever be required.
Project cost movements, construction delays, working-capital requirements or scope changes can alter funding needs. Bannerman Energy Ltd and CNNC Overseas Limited are also responsible for their respective shares of future costs under the joint venture.
What has changed materially is financing risk. Instead of needing to negotiate a large conventional debt package while simultaneously raising equity, Bannerman Energy Ltd now has a strategic partner that has already contributed hundreds of millions of United States dollars and is contractually aligned with future production.
That is particularly important for uranium developments because construction schedules can span several years while revenue does not begin until commissioning and sales commence.
The debt-free structure also leaves Etango without the scheduled interest and principal burden associated with conventional project finance during ramp-up, although the price of that flexibility is permanent sharing of project ownership.
What does Bannerman Energy Ltd’s share price say about investor sentiment?
Bannerman Energy Ltd traded around A$3.70 on September 25, down approximately 3.6% during the session.
A negative one-day reaction does not mean investors regard the CNNC Overseas Limited deal as commercially unfavourable. Much of the transaction had already been announced and progressively de-risked before completion, so the final receipt of funds contained less surprise than the original February agreement.
The recent A$124 million placement at A$4.00 also creates a near-term valuation reference point. With shares below that issue price, investors appear to be balancing the reduction in funding risk against dilution, uranium-market volatility, execution risk and the economics surrendered to the strategic partner.
Completion therefore shifts the valuation debate. Financing has moved from being one of Etango’s central uncertainties toward construction execution and future uranium economics.
What becomes the next defining catalyst for Bannerman Energy Ltd?
The final investment decision is now the obvious milestone.
Once the joint venture formally commits to full construction, investor attention will move toward engineering progress, capital discipline, commissioning schedule and uranium contracting.
The partnership also makes China National Nuclear Corporation more than a financier. Through CNNC Overseas Limited, the group becomes a major shareholder in the project and the buyer of most future production, aligning Etango directly with one of the world’s largest nuclear-fuel supply chains.
That strategic relationship materially improves project certainty, but it does not eliminate mine-building risk. Bannerman Energy Ltd still has to turn cash, permits and engineering plans into a functioning Namibian uranium operation.
September 25 nevertheless represents a structural change in the story. Etango is no longer principally an undeveloped uranium project searching for hundreds of millions of dollars. It is a funded joint venture with a major nuclear-industry partner, leaving the investment decision and construction execution as the hurdles that now matter most.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.