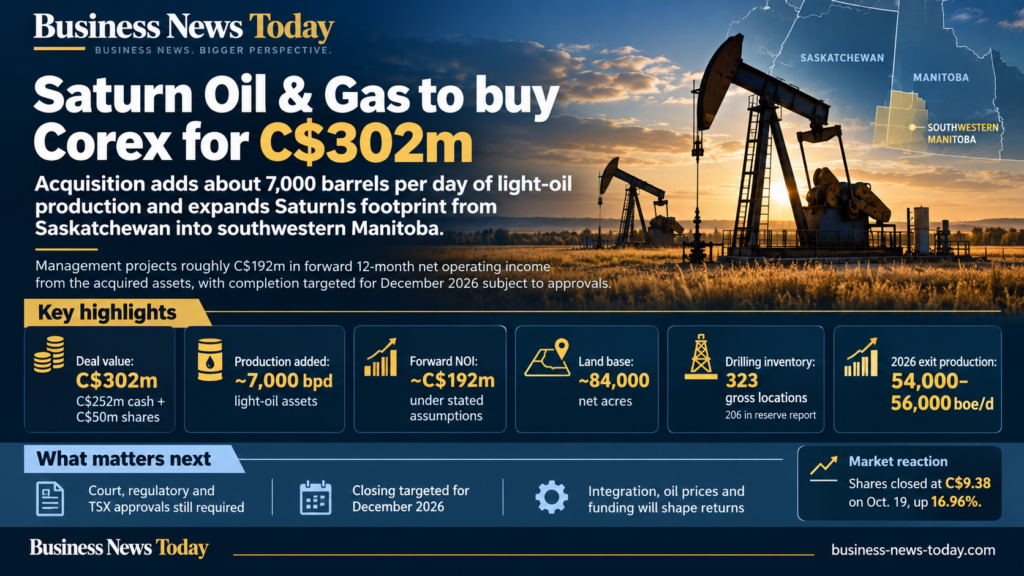
Saturn Oil & Gas Inc. (TSX: SOIL), the Calgary-based Canadian oil producer, has entered into a definitive agreement to acquire Corex Resources Ltd. for approximately C$302 million in cash and shares, adding an estimated 7,000 barrels per day of light-oil production and expanding its operating footprint from Saskatchewan into southwestern Manitoba. Announced on October 19, 2026, the transaction comprises approximately C$252 million in cash and C$50 million in Saturn shares, with completion targeted for December subject to court, regulatory and stock exchange approvals. Management expects the additional production and its existing development programme to support a 2026 exit production rate of 54,000 to 56,000 barrels of oil equivalent per day, while projecting approximately C$192 million of forward 12-month net operating income from the acquired assets under specified commodity-price and investment assumptions. Although the proposed acquisition appears attractive on management’s operating-income valuation measures, the outlook remains sensitive to oil prices, development spending, integration costs and the funding required to complete the purchase.
Why is Saturn Oil & Gas acquiring Corex Resources to expand into southwestern Manitoba?
The acquisition extends Saturn’s existing southeastern Saskatchewan operations into neighbouring southwestern Manitoba, creating a more geographically connected light-oil production portfolio. Corex’s assets are located near areas where Saturn already operates, potentially allowing the combined company to coordinate drilling, infrastructure and marketing activities across provincial boundaries. This offers a different commercial rationale from an acquisition involving geographically isolated production.
Corex is a privately held Calgary-based company with production concentrated in light oil. Saturn estimates that the assets will contribute approximately 7,000 barrels per day, increasing its overall liquids weighting to around 86%. The transaction therefore strengthens the company’s exposure to crude oil production rather than introducing a major new natural gas business.
The acquired asset base includes approximately 84,000 net acres and an average working interest of around 96%. High working interests can provide greater operational control over development decisions and the corresponding economic exposure, although they also increase the capital required from the operator when new wells are drilled.
Saturn intends to apply techniques used within its Saskatchewan operations, including open-hole multilateral drilling, to development targets identified within the acquired acreage. Management believes those capabilities could support improved recovery and more attractive drilling economics. However, the productivity and financial returns from future wells remain prospective until supported by actual results.
The proximity of the acquired assets to existing transportation and gathering infrastructure also creates potential commercial benefits. Saturn has identified opportunities to improve oil marketing arrangements, reduce costs and streamline operational activities.
The acquisition is therefore intended to create operating efficiencies as well as increase production. Whether those efficiencies can be realised will depend on the detailed asset integration programme and subsequent operating performance.
How does the C$302 million Corex acquisition price compare with expected operating income?
Saturn estimates that the acquired assets could generate approximately C$192 million of net operating income over a forward 12-month period. Comparing the C$302 million purchase consideration with that forecast produces a multiple of approximately 1.57 times projected net operating income, consistent with management’s stated acquisition multiple of around 1.6 times.
The calculation appears attractive, but the underlying earnings measure requires careful interpretation. Net operating income is not equivalent to consolidated net profit, free cash flow or cash available for distribution after financing and development expenditure. It excludes certain costs that affect the eventual economic benefit to shareholders.
Saturn’s projection assumes commodity strip prices prevailing on October 13 and approximately C$77.8 million of development capital investment in the Corex assets over the following 12 months. Consequently, the C$192 million operating-income estimate should not be interpreted as a fixed contractual payment or cash generation independent of future drilling.
The company also estimates an operating netback of approximately C$82 per barrel for the acquired assets under the same pricing assumptions. A netback measures revenue remaining after specified operating and related costs, but the precise definition matters when comparing businesses with different accounting and production characteristics.
The transaction includes assets with an estimated proved developed producing net present value, discounted at 10%, of approximately C$370 million. The purchase price represents about 82% of that measure. However, discounted reserve values depend on future production assumptions, commodity prices, operating costs and reserve engineering, and they do not represent cash already realised.
Saturn has also disclosed larger estimated values for total proved and proved-plus-probable reserves. These measures incorporate additional development assumptions and should not be added to the producing-reserve estimate as separate sources of value.
A successful acquisition would require the actual operating and development performance to support the expected returns after financing and corporate costs are considered.
What do the 323 identified drilling locations add to Saturn Oil & Gas’s production outlook?
Corex’s portfolio includes 323 gross identified drilling locations, representing 279 net locations. Of these, 206 gross locations, or 189 net locations, are included in the latest reserve report, while additional development opportunities have been identified through internal technical evaluation.
The distinction between booked and unbooked drilling inventory is important because internally identified prospects may require additional technical work before they justify investment. They should not automatically be treated as proved reserves or future production that is certain to occur.
Saturn has identified potential open-hole multilateral development targets in the Lodgepole Formation near Virden and the Spearfish Formation. The company believes these opportunities may provide additional value beyond the existing reserve report, although their economics remain dependent on drilling outcomes and the applicable development costs.
The acquisition also includes infrastructure assets that management believes could support operating efficiencies. Existing waterflood programmes currently affect a portion of forecast production and may offer opportunities for expansion. Waterflooding can help maintain reservoir pressure and improve recovery in suitable fields, but the benefits vary according to geological conditions and the costs of water injection and handling.
Saturn expects the acquired production to support an exit rate of 54,000 to 56,000 barrels of oil equivalent per day in 2026, alongside development activity already underway. The company does not expect the acquisition to materially alter its full-year average production guidance of 43,000 to 44,000 barrels per day because closing is anticipated relatively late in the year.
The higher exit rate therefore provides a potential starting point for 2027 rather than a measurement of production already achieved in October. A more reliable assessment will emerge after closing and the release of updated annual production and capital expenditure guidance.
How will Saturn finance the Corex acquisition, and what does the share component mean for investors?
The C$302 million consideration comprises approximately C$252 million in cash and C$50 million in Saturn common shares. The company plans to finance the cash portion through available cash and drawings under its credit facility. The transaction therefore introduces additional borrowing requirements while also increasing the number of shares outstanding.
The equity consideration is valued using a deemed share price based on the preceding 20-day volume-weighted average. Shares issued to funds associated with Corex’s majority shareholder, Azimuth Energy Partners, will be subject to staggered release arrangements over 18 months following completion. Such provisions can influence the timing at which newly issued shares become available for unrestricted trading.
The use of shares reduces the immediate cash requirement compared with an entirely cash-funded transaction. However, existing investors will have a smaller percentage ownership interest after the new shares are issued, subject to the final share count and transaction arrangements.
Saturn expects the acquisition to increase adjusted funds flow and free funds flow per share, supported by the acquired production and operating margins. That is a management forecast rather than an established result, and the outcome will depend on whether incremental cash generation exceeds the associated financing and dilution costs.
Management also maintains a target of exiting 2027 with net debt below one times adjusted EBITDA. The target assumes the transaction and development programme perform sufficiently well to support debt reduction. Commodity-price weakness, higher investment requirements or production underperformance could affect that outcome.
The company estimates approximately C$6 million in annual operating efficiencies after integration, including potential cost reductions and improved marketing arrangements. Those savings remain prospective and should be evaluated against actual operating expenditure in subsequent reporting periods.
Why did Saturn Oil & Gas shares surge after the Corex transaction announcement?
Saturn shares closed at C$9.38 on October 19, gaining approximately 16.96% from the previous session’s C$8.02 close. The stock subsequently closed at C$9.77 on October 23, approximately 21.8% above the pre-announcement closing level. The strength of the market response indicates increased investor interest during the period, although changes in oil prices and broader market conditions may also have contributed.
The acquisition’s apparent valuation discount relative to management’s discounted reserve estimates and projected operating income provides a commercially relevant explanation for the attention. However, those estimates remain dependent on commodity pricing, production and capital investment assumptions, making it premature to conclude that the transaction has already created a quantified amount of shareholder value.
Corex shareholders representing more than 72% of outstanding shares have entered support arrangements sufficient to exceed the applicable two-thirds approval threshold. Nevertheless, the transaction remains subject to court, regulatory and stock exchange approvals and customary closing conditions.
Completion is expected in December 2026, with Saturn planning to release its 2027 capital programme and updated guidance around that period. Those disclosures should provide more detailed information about development spending and the integration of Corex’s production.
The acquisition potentially strengthens Saturn’s light-oil production base and adds a substantial inventory of drilling opportunities. Its commercial success will depend on delivering the forecast operating margins, integrating the assets efficiently and reducing debt while funding profitable development.
Key takeaways on Saturn Oil & Gas’s C$302 million Corex Resources acquisition
- Saturn agreed to acquire Corex Resources for approximately C$302 million.
- Consideration comprises around C$252 million in cash and C$50 million in shares.
- The acquisition adds an estimated 7,000 barrels per day of light-oil production.
- The assets are located in southwestern Manitoba, adjacent to Saturn’s Saskatchewan operations.
- Management projects approximately C$192 million in forward 12-month net operating income under specified assumptions.
- The company estimates a purchase multiple of around 1.6 times projected operating income.
- The portfolio includes approximately 84,000 net acres.
- Saturn identified 323 gross drilling locations, including 206 locations in the reserve report.
- The company expects 2026 exit production of 54,000 to 56,000 barrels of oil equivalent per day.
- Completion is targeted for December 2026, subject to outstanding approvals and conditions.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.