MP Materials Corp. (NYSE: MP) could face an unusual change in its shareholder register if China Rare Earth Group completes a proposed acquisition of Shenghe Resources. Reuters reported on September 18, citing people familiar with the matter, that the Chinese state-owned rare-earth group is in talks to acquire Shenghe and is seeking a controlling interest. The discussions are confidential, no completion timetable is known and none of the companies involved publicly commented to Reuters.
Shenghe beneficially owned approximately 5.55 million MP Materials shares, representing about 3.1% of the company based on the ownership filing referenced by the US Securities and Exchange Commission. If China Rare Earth Group acquires Shenghe and retains that investment, it could indirectly obtain economic exposure to the US rare-earth producer through Shenghe’s existing stake. That would not amount to control of MP Materials and should not be confused with ownership of its operations, management or Mountain Pass mine.
Why does Shenghe own part of MP Materials in the first place?
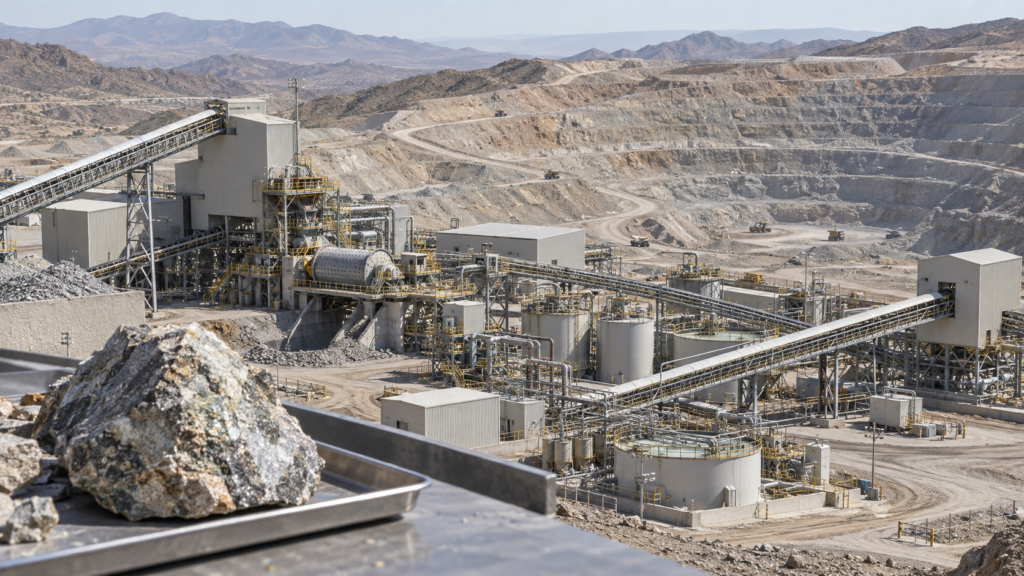
The relationship predates MP Materials’ current role as a major part of US critical-minerals policy. Shenghe, a Chinese rare-earth company with extensive processing expertise, became involved with the Mountain Pass operation as the mine was rebuilt after the bankruptcy of its previous owner.
For years, Mountain Pass produced rare-earth concentrate that was shipped to China for further processing because the United States lacked sufficient domestic separation capacity. Shenghe therefore had both an equity relationship and a commercial connection to MP during an earlier phase of the company’s development.
That operating model has changed dramatically. MP stopped shipping rare-earth concentrate to China in 2025 as it accelerated domestic separation and magnet manufacturing, and its 2026 results increasingly reflect sales of separated neodymium-praseodymium products rather than raw concentrate.
The remaining Shenghe equity stake is consequently a legacy financial link inside a company whose strategic direction has moved decisively toward a US-based end-to-end rare-earth supply chain.
Why would China Rare Earth Group want to acquire Shenghe Resources?
Reuters reported that the potential transaction forms part of China’s continuing consolidation of the rare-earth industry. China Rare Earth Group was created in 2021 by combining several state-linked entities and has become a major force in heavy rare-earth materials. Acquiring Shenghe could bring additional domestic capacity as well as overseas investments under the larger state-owned group.
Shenghe owns interests outside China in addition to its MP Materials position. Its international exposure includes assets connected with rare-earth projects in Australia and other jurisdictions, making the company strategically broader than its approximately 3% stake in MP.
Consolidation can strengthen control over production planning and access to tightly managed Chinese rare-earth quotas. Rare earths are essential for permanent magnets used in electric vehicles, industrial motors, wind turbines, robotics, electronics and defence equipment, giving supply-chain structure significance beyond the mining industry itself.
The talks remain preliminary enough that investors should avoid assuming China Rare Earth Group will ultimately acquire Shenghe. A controlling transaction would require corporate, regulatory and financing steps before the ownership implications become concrete.
Why is the potential ownership overlap with the US government unusual?
MP Materials entered a major public-private partnership with the US Department of Defense in July 2025. The department agreed to purchase $400 million of convertible preferred stock and received a warrant that, on an as-converted and as-exercised basis at the time of the agreement, represented approximately 15% of MP’s issued and outstanding common shares. MP said the structure positioned the Department of Defense to become its largest shareholder.
That agreement also included a 10-year NdPr price floor of $110 per kilogram, a long-term commitment supporting purchases from MP’s planned 10X magnet facility, a $150 million loan for heavy rare-earth separation and a $1 billion construction-financing commitment from JPMorgan Chase Funding and Goldman Sachs Bank USA.
If China Rare Earth Group acquires Shenghe, MP could therefore have indirect economic exposure on its shareholder register linked to a Chinese state-owned rare-earth company while simultaneously maintaining a much larger strategic investment relationship with the US government.
The proportions matter. Shenghe’s reported 3.1% interest is far smaller than the potential 15% represented by the US government’s preferred equity and warrant structure, and there is no evidence from the reported talks that China Rare Earth Group would gain management control or strategic rights over MP Materials.
How much has MP Materials changed since the US government partnership began?
MP’s second-quarter 2026 results show rapid progress toward selling more processed materials. Revenue increased 89% to $108.5 million, while price-protection agreement income added another $17.6 million. NdPr production rose 41% to 840 metric tonnes and sales increased 127% to 1,006 tonnes.
Adjusted EBITDA improved to positive $28.5 million from a $12.5 million loss a year earlier, although the company still recorded a GAAP net loss of $20.3 million. Cash and short-term investments had also increased substantially as MP funded its downstream expansion.
The company is now developing its 10X magnet manufacturing campus in Northlake, Texas, involving more than $1.25 billion of planned company investment. Once commissioned, the facility is expected to help lift MP’s total US magnet manufacturing capacity to approximately 10,000 tonnes annually.
MP has also secured a new long-term American aerospace and defence customer for separated gadolinium and launched Project Swarm to aggregate rare-earth magnet demand across the drone industry. Those moves show how the company is deliberately building customers outside its former China-linked concentrate model.
Does the possible Shenghe acquisition change MP Materials’ operations today?
No operational change has been announced. MP continues operating Mountain Pass, expanding separation capacity and building magnet facilities in Texas under its existing management and corporate structure.
A transaction involving Shenghe would first change ownership of a shareholder, not ownership of MP itself. Whether the resulting indirect holding triggers additional regulatory scrutiny would depend on the exact transaction structure, applicable law and any rights attached to the shares.
The distinction is especially important because rare-earth companies now operate within highly sensitive international supply chains. A headline about Chinese state ownership can sound more consequential than the actual corporate rights associated with a minority equity position.
Investors should therefore focus on concrete developments: whether China Rare Earth Group signs a binding agreement, whether Shenghe’s MP stake is retained, whether any regulatory authority reviews the holding and whether MP itself discloses a material consequence.
What does the situation reveal about the global rare-earth supply chain?
It illustrates how difficult it is to separate supply chains that were built over decades of international integration. MP Materials is now a centrepiece of US efforts to produce rare-earth magnets domestically, yet part of its shareholder history still reflects an earlier period when Chinese processing expertise was integral to Mountain Pass economics.
China continues to dominate many stages of rare-earth separation and magnet manufacturing, while the United States, Australia and other countries are investing heavily in alternatives. Building mines alone is not enough because separated oxides, metals, alloys and finished magnets all require specialised industrial capacity.
MP’s strategy is to internalise more of those stages. Its recent financial improvement, Pentagon-backed magnet expansion and downstream customer agreements provide evidence that this process is progressing, even though the business remains in a capital-intensive ramp.
The Shenghe discussions consequently do not redefine MP Materials. They expose how the old rare-earth supply chain and the emerging one remain financially connected in unexpected ways.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.