
Afcons Infrastructure Limited (NSE: AFCONS, BSE: 544280) has secured engineering, procurement and construction contracts worth approximately ₹3,469 crore for the Jewar Link Expressway and an underground section of the Lucknow Metro Phase-1B project. Announced on 29 October 2026, the awards take fresh orders secured during FY27 to ₹19,438 crore, representing a substantial recovery in contract acquisition following a difficult previous financial year. The developments strengthen the Mumbai-based infrastructure contractor’s exposure to two major public infrastructure programmes in Uttar Pradesh, spanning airport connectivity and urban rail transportation. However, with quarterly profitability under pressure and the shares trading near their 52-week lows, the commercial question is whether the expanding project portfolio can produce stronger revenue, cash flow and margins.
The two contracts arrive at a consequential point for Afcons, whose first-quarter FY27 results showed that a sizeable order book does not necessarily translate into immediate earnings growth. Consolidated total income declined 20.3% year on year during the June quarter, while profit after tax fell 77.9%. The company’s latest awards therefore improve its future workload, but their financial contribution will depend on project mobilisation, construction progress, billing milestones and the eventual collection of receivables.
What does Afcons Infrastructure’s ₹2,086 crore Jewar Link Expressway contract mean for airport connectivity in Uttar Pradesh?
The larger of the two contracts has been awarded by the Uttar Pradesh Expressways Industrial Development Authority for construction of the 24.5-kilometre Jewar Link Expressway. The engineering, procurement and construction contract is valued at approximately ₹2,086 crore, excluding goods and services tax. The project involves developing a six-lane, access-controlled greenfield expressway with provision for future expansion to eight lanes.
The planned corridor will strengthen connectivity around Noida International Airport at Jewar by linking the Yamuna Expressway and Ganga Expressway networks. These connections are intended to improve access between the airport and surrounding passenger, commercial and freight corridors. Afcons will be responsible for delivering a substantial civil infrastructure asset rather than operating the airport or deriving direct revenue from aviation activity.
The distinction is commercially relevant because the contract’s economics depend primarily on construction execution rather than future airport passenger numbers. Higher regional traffic may strengthen the project’s long-term economic rationale, but Afcons’ contracted revenue will arise from fulfilling the construction agreement and its associated billing provisions. The airport’s development could support demand for surrounding infrastructure, although such wider investment opportunities are separate from the ₹2,086 crore award.
For Afcons, the expressway adds to its surface transportation portfolio, which accounted for ₹10,324 crore, or approximately 24%, of its reported pending order book at 30 June 2026. It also reinforces the contractor’s position in complex transportation infrastructure, where project delivery requires coordination across engineering, procurement, site access and construction scheduling. The actual margin contribution will depend on the commercial terms, cost management and progress against contractual milestones, none of which can be inferred from the headline award value alone.
Why is the ₹1,383 crore Lucknow Metro underground contract strategically different from the Jewar Expressway award?
The second award covers a 6.52-kilometre underground stretch of Lucknow Metro Phase-1B, with an approximate contract value of ₹1,383 crore. Afcons said it had received a notice of award from Uttar Pradesh Metro Rail Corporation Limited for the design and construction of the underground section. The scope includes seven underground stations, associated civil and architectural works, utility infrastructure, fire safety systems and connectivity between underground and elevated sections.
Unlike the Jewar Expressway, the Lucknow Metro package involves a more concentrated urban construction environment. Underground stations and connecting infrastructure require careful integration of excavation, structural engineering, utility interfaces and passenger safety provisions. Construction sequencing can be especially important because access limitations, underground conditions and interactions with existing urban infrastructure may influence how quickly work progresses.
Afcons has an established presence in underground metro engineering, providing a relevant operational foundation for the new contract. At the end of June 2026, underground and elevated metro projects accounted for ₹8,905 crore, or approximately 21%, of its pending order book. The Lucknow award builds on that specialised segment rather than representing an entirely new business line.
The two Uttar Pradesh awards also introduce different execution and cash-flow characteristics into the portfolio. Surface road construction and underground metro development require different equipment, project-management capabilities and construction schedules. Their combination broadens workload across established competencies, although diversification does not eliminate the possibility of delays or higher-than-planned costs.
How significant are Afcons Infrastructure’s ₹19,438 crore FY27 order wins compared with its existing order book and annual revenue?
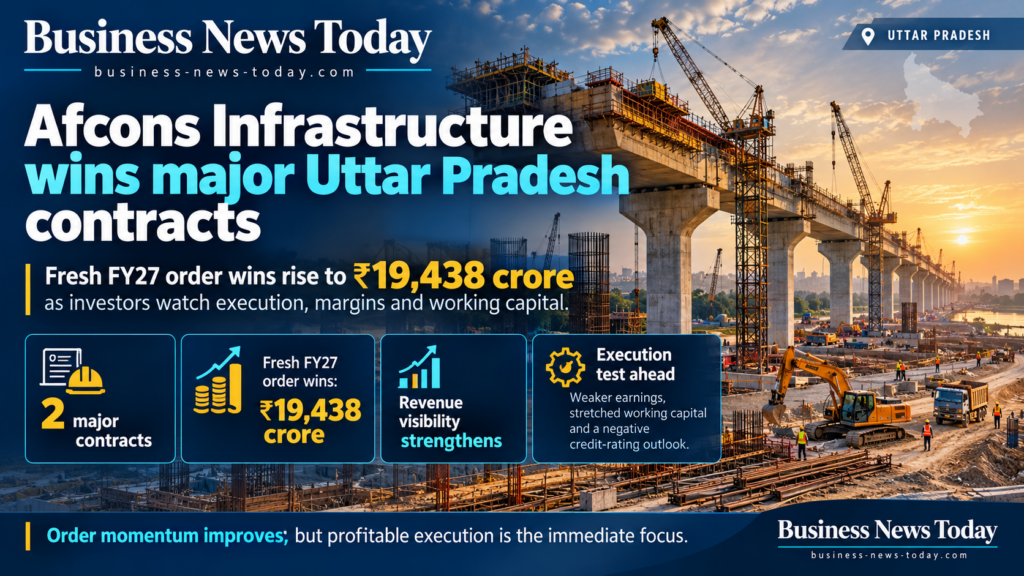
Afcons’ latest announcement puts fresh orders secured during FY27 at ₹19,438 crore, including the Jewar Expressway and Lucknow Metro contracts. The two new awards represent approximately 17.8% of that disclosed financial-year order inflow. They also amount to roughly 28.2% of the ₹12,322 crore consolidated total income reported for FY26, illustrating the scale of the newly secured construction workload relative to the previous year’s business.
That comparison should not be confused with an immediate revenue addition. Engineering, procurement and construction contracts generally generate revenue over their execution periods, subject to progress and applicable accounting requirements. The ₹3,469 crore headline value consequently represents a contractual workload rather than revenue already recognised or cash already received.
The improvement in new business acquisition is nevertheless substantial. Afcons reported fresh order inflows of ₹4,125 crore during FY26, when slower ordering activity and delays in converting potential projects affected business momentum. The ₹19,438 crore secured during the current financial year is approximately 4.7 times that previous full-year intake, even though FY27 remains in progress.
At 30 June 2026, Afcons reported a pending order book of ₹43,290 crore, equivalent to approximately 3.5 times FY26 consolidated total income. The backlog gives the contractor considerable potential work visibility, but revenue conversion also depends on the proportion of projects that have entered active construction, the pace of execution and the timing of customer approvals.
It would be incorrect to calculate a new current order book simply by adding all FY27 order wins to the June backlog. The reported June figure already incorporated contracts secured earlier in the financial year, while construction progress, contract adjustments and subsequent awards can change the outstanding balance. A refreshed pending order book in the next financial results will provide a more reliable measure of how the contract pipeline has evolved.
Why has Afcons Infrastructure’s financial performance weakened despite its substantial construction order book?
Afcons’ financial results explain why the latest orders carry greater significance than a routine contract announcement. Consolidated total income declined from ₹13,023 crore in FY25 to ₹12,322 crore in FY26, a reduction of 5.4%. Adjusted EBITDA, as defined by the company, declined from ₹1,662 crore to ₹1,439 crore, while the corresponding margin narrowed from 12.8% to 11.7%.
Profitability deteriorated more sharply. Consolidated profit after tax fell from ₹487 crore in FY25 to ₹251 crore in FY26, a decline of 48.5%. The final quarter was particularly weak, with Afcons reporting a net loss of approximately ₹89 crore and an EBITDA margin of 6.1%.
The June 2026 quarter showed a sequential recovery but remained considerably weaker than the corresponding period of the previous financial year. Total income fell to ₹2,727 crore from ₹3,419 crore a year earlier, while EBITDA declined 41% to ₹263 crore. The EBITDA margin narrowed from 13% to 9.6%, and profit after tax decreased from ₹137 crore to approximately ₹30 crore.
The June-quarter profit represented an improvement from the March-quarter loss, but the year-on-year comparison indicated that underlying operating momentum had not yet returned to earlier levels. Afcons’ extensive construction backlog provided future revenue opportunities, although the financial statements showed that project volume and profitability were moving at different speeds.
Management has previously identified project execution delays, labour availability constraints and slower progress at certain construction sites as factors affecting performance. The commercial consequences can extend beyond postponed revenue recognition, because delayed work may reduce utilisation of equipment and personnel while fixed operating expenses continue.
The new contracts can support a subsequent recovery in activity, but their immediate contribution will be limited by the time required to mobilise resources and progress through construction milestones. A sustained earnings improvement will therefore require higher executable workloads alongside better absorption of operating costs and more effective project delivery.
Can the new contracts improve Afcons Infrastructure’s working capital position after CRISIL revised its rating outlook to negative?
Working capital represents another important dimension of the latest contract awards. On 19 August 2026, CRISIL Ratings revised the outlook on Afcons Infrastructure’s long-term facilities and non-convertible debentures from stable to negative while reaffirming the long-term rating at CRISIL AA-. The agency attributed the outlook revision to weaker operating performance and increased working capital intensity, including delayed collection of receivables and a build-up of contract assets.
According to CRISIL Ratings, Afcons’ net working capital increased to 139 days during FY26 from 117 days in FY25. Total debt rose to approximately ₹3,529 crore at 31 March 2026 from ₹2,230 crore a year earlier. The credit agency also identified certification delays, slower project progress and payment-related constraints among factors affecting the working capital cycle.
The negative outlook is not equivalent to a downgrade of the AA- rating. It does, however, identify the financial indicators that must improve for the existing credit profile to become more secure. The timing and reliability of receivable collections, operating cash generation and debt levels are consequently central to evaluating the benefit of new construction orders.
Newly awarded EPC contracts may provide access to mobilisation advances, depending on their individual terms. Such advances can support early-stage expenditure on equipment, materials, labour and site establishment before significant project billings are generated. CRISIL previously indicated that advances expected from recently secured projects could improve Afcons’ liquidity, although those estimates should not automatically be attributed to the two contracts announced on 29 October.
Afcons retained financial resources to manage its obligations. CRISIL reported cash and cash equivalents of approximately ₹900 crore at 31 March 2026, along with unutilised fund-based working capital facilities of about ₹1,200 crore at the end of June. The agency also identified potential liquidity support from undrawn mobilisation advances.
The distinction between available financial flexibility and realised operating cash flow remains important. A contractor can have a large order book and substantial banking facilities while still facing cash-flow pressure if certification and collection cycles lengthen. For Afcons, the most valuable improvement would be a combination of faster project execution and more timely conversion of work performed into cash receipts.
What does the Afcons Infrastructure share price near its 52-week low reveal about investor expectations?
The stock market has remained cautious despite Afcons’ stronger order acquisition during FY27. The shares closed at ₹211.66 on the National Stock Exchange of India on 29 October 2026, after touching a 52-week low of ₹203.60 during that session. The share price had declined approximately 53.5% over the preceding year, illustrating the extent of the deterioration in market valuation.
During morning trading on 30 October, Afcons shares were quoted around ₹207.19 at approximately 10:47 a.m. IST, down 2.1% from the previous close. The stock remained close to its recent low despite the substantial contract announcement made after the preceding trading session. That movement should not be attributed exclusively to the orders, as broader market conditions and existing concerns over earnings and working capital can also influence trading.
The company’s market capitalisation at the quoted intraday price was approximately ₹7,620 crore. This was below the ₹19,438 crore of fresh FY27 orders disclosed by management, although comparing market capitalisation with contract values does not establish that a stock is undervalued. Construction orders contain substantial execution costs and are fulfilled across multiple reporting periods, whereas equity valuation reflects expectations for future profits, cash flow, capital requirements and financial risk.
The gap between expanding orders and subdued equity performance suggests that stronger contract acquisition has not yet been sufficient to restore investor confidence in the earnings trajectory. The market response is consistent with a preference for demonstrated improvement in project execution and cash generation rather than relying solely on additional contract wins.
For a sustained valuation recovery, Afcons would need to demonstrate that its increased workload is producing higher revenue recognition, better margins and a healthier working capital cycle. The next quarterly results will offer a near-term opportunity to assess whether those indicators are beginning to move in the same direction.
How could the Jewar Expressway and Lucknow Metro projects strengthen Afcons Infrastructure’s competitive position?
The Uttar Pradesh awards support Afcons’ strategy of participating in technically demanding infrastructure projects where established construction capabilities, specialist equipment and execution experience can influence competitiveness. The expressway adds surface transportation work, while the metro award expands its underground urban infrastructure portfolio. Both projects sit within infrastructure categories in which Afcons already has an operating track record.
The awards also reinforce the role of public infrastructure spending in generating construction opportunities. Airport access roads and metro systems involve long-term transport planning, coordination among public agencies and substantial engineering commitments. They can create meaningful demand for experienced contractors, although the financial attractiveness of individual projects depends on bidding discipline and contract execution.
Afcons’ wider portfolio includes road infrastructure, bridges, tunnels, marine facilities, underground transportation and industrial construction across domestic and international markets. This breadth provides opportunities to deploy specialist capabilities across different project categories and geographies. It also requires management to allocate equipment, engineering personnel and financial resources among contracts with varying construction conditions and payment cycles.
At the end of June, surface transportation and underground and elevated metro projects together represented approximately 45% of the pending order book. The new awards reinforce two already significant segments, rather than materially changing the company’s fundamental business profile.
The economic contribution of these contracts will be better understood once mobilisation progresses and construction milestones begin producing measurable revenue. Stronger competitive positioning should ultimately be reflected in sustainable margins and repeatable project execution, rather than contract wins viewed in isolation.
Why will Afcons Infrastructure’s November 2026 results be the next test of its recovery strategy?
Afcons Infrastructure has scheduled a board meeting for 4 November 2026 to consider its unaudited standalone and consolidated financial results for the quarter and half-year ended 30 September. The results will cover a period preceding the two Uttar Pradesh contracts, so they should not be expected to capture meaningful revenue from the newly announced projects. Their value lies instead in showing whether the existing portfolio has begun delivering the operational improvement anticipated earlier in FY27.
Management previously indicated that execution activity was expected to strengthen during the second half of the financial year. The September-quarter results, accompanying order-book disclosures and management commentary should provide evidence of whether the project portfolio was becoming more productive ahead of that expected acceleration.
Revenue growth alone will not provide a complete assessment. EBITDA margins, finance costs, debt levels and working capital developments will be equally important because the previous slowdown affected both earnings and cash conversion. An improvement in project activity accompanied by continued receivable accumulation would represent a less convincing recovery than one supported by healthier cash flow.
Investors will also be able to evaluate progress towards Afcons’ previously indicated FY27 order inflow ambition of approximately ₹30,000 crore. With fresh orders already reaching ₹19,438 crore, the latest awards have strengthened the company’s position against that objective. Achieving additional contract wins would expand future workload, although the pace at which the existing order book becomes executable remains a separate consideration.
Afcons Infrastructure’s ₹3,469 crore Uttar Pradesh contract announcement has strengthened its position in two important infrastructure segments and provided further evidence of a recovery in new-order acquisition. The unresolved commercial issue is whether this stronger pipeline can reverse the decline in earnings and ease the working capital pressures identified during FY26 and the June quarter.
A more convincing recovery would emerge if the November results demonstrate improving project execution, stabilising margins and progress in converting outstanding contract assets and receivables into cash. Those indicators, followed by actual mobilisation and billing progress on the Jewar Expressway and Lucknow Metro contracts, will determine whether the larger order portfolio translates into durable financial improvement.
Key takeaways from Afcons Infrastructure’s ₹3,469 crore Jewar Expressway and Lucknow Metro order wins
- Afcons Infrastructure Limited secured two Uttar Pradesh EPC contracts worth approximately ₹3,469 crore on 29 October 2026.
- The ₹2,086 crore Jewar Link Expressway contract covers a 24.5-kilometre access-controlled corridor serving Noida International Airport connectivity.
- The ₹1,383 crore Lucknow Metro Phase-1B award involves 6.52 kilometres of underground infrastructure and seven stations.
- Fresh FY27 order wins have reached ₹19,438 crore, substantially exceeding the ₹4,125 crore of orders secured during the whole of FY26.
- The pending order book stood at ₹43,290 crore at 30 June 2026, before subsequent construction activity and contract additions changed the balance.
- Consolidated Q1 FY27 total income declined 20.3% year on year, while profit after tax fell 77.9% to approximately ₹30 crore.
- CRISIL Ratings revised its long-term rating outlook to negative in August 2026 while reaffirming the AA- rating, citing operating and working capital pressures.
- Afcons shares remained close to their 52-week lows during morning trading on 30 October, despite the stronger order pipeline.
- The company’s 4 November quarterly results will provide the next significant evidence on execution, margins, debt and cash conversion.
- The commercial benefits of the new contracts will depend on successful mobilisation, construction progress and timely conversion of completed work into billings and cash receipts.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.