

Trilogy Metals Inc. (NYSE American: TMQ; TSX: TMQ) has executed definitive agreements for a US$35.6 million strategic equity investment by the U.S. Department of War, completing the most important documentation step before a transaction expected to close in September 2026. The government will obtain approximately 10% of Trilogy on a non-diluted basis through a combination of newly issued shares and shares purchased from South32, while penny-priced warrant and call-option rights could expand the government’s eventual economic position to approximately 17.5%. Proceeds associated with both halves of the transaction are required to flow into Ambler Metals LLC, the 50/50 Trilogy-South32 joint venture that owns the Upper Kobuk Mineral Projects in northwestern Alaska.
The financing is small compared with the capital required to build Trilogy’s flagship Arctic copper-zinc project, but its strategic importance extends far beyond the US$35.6 million headline amount. Trilogy’s latest feasibility economics estimate approximately US$1.18 billion of initial capital for Arctic, together with a post-tax net present value of US$1.11 billion at an 8% discount rate and a 22.8% post-tax internal rate of return. The government investment therefore covers only about 3% of the project’s estimated initial construction requirement, meaning the real value lies in policy alignment, infrastructure support and potential de-risking rather than direct funding of the mine itself.
Washington’s participation is directly linked to the revival of the proposed 211-mile Ambler Access Project, which would connect the isolated mining district to the Dalton Highway. The Department of War describes the district as strategically important for copper, cobalt, germanium and other minerals used across defence systems, advanced electronics, data centers and industrial infrastructure. The government estimates the broader Ambler development could support more than 2,730 construction jobs, approximately 500 long-term mining jobs and more than US$1.1 billion of Alaska state revenue, although those outcomes remain dependent on permitting, financing and eventual mine development.
How is the $35.6m Trilogy Metals investment structured?
The government will invest approximately US$17.8 million directly in Trilogy Metals by purchasing 8,215,570 units at US$2.17 each. Every unit contains one common share and three-quarters of a ten-year warrant, with each full warrant exercisable at US$0.01 once either Phase 1 of the Ambler Road is completed or Trilogy undergoes a change of control. Trilogy is required to reinvest the entire US$17.8 million of direct proceeds into Ambler Metals.
A second approximately US$17.8 million payment will go to South32 in exchange for another 8,215,570 existing Trilogy shares currently owned by the diversified miner. South32 will also grant the government a ten-year call option over another 6,161,678 Trilogy shares at US$0.01 each, exercisable under the same Ambler Road completion or change-of-control conditions. South32 has committed to reinvesting the full cash proceeds it receives into Ambler Metals, meaning the entire US$35.6 million transaction is ultimately directed toward the Upper Kobuk programme even though half of the equity changes hands through an existing shareholder.
On closing, the government will hold approximately 16.43 million Trilogy shares across the two transaction legs, representing about 10% of the company on a non-diluted basis. If all penny-priced warrant and call-option rights later become exercisable and are exercised, the additional exposure would amount to approximately 12.32 million shares, creating the potential 17.5% combined economic position described by the Department of War.
Why are the one-cent warrants economically more important than their exercise price suggests?
The US$0.01 exercise price makes the warrants and call options economically similar to contingent additional equity rather than conventional market-priced options. Their value depends primarily on whether the triggering event occurs, especially completion of Phase 1 of the Ambler Road, rather than on Trilogy’s stock needing to rise above a high strike price. If the road milestone is achieved while Trilogy remains a viable company, the government would have the ability to acquire millions of additional shares at a nominal cost.
This creates a powerful incentive alignment around infrastructure development. The government’s direct 10% ownership exists at closing, while another substantial block of economic exposure becomes accessible once the district’s critical access road reaches the specified stage. Trilogy shareholders therefore receive government capital and political alignment today while accepting meaningful potential dilution later if one of the project’s most important infrastructure bottlenecks is resolved.
Using Trilogy’s July-reported share count of approximately 172.75 million shares as a historical reference, the 12.32 million contingent shares would equal roughly 7.1% of that pre-transaction share base. The actual percentage at the time of any exercise could differ because additional shares may be issued before then, but the calculation demonstrates why the contingent securities deserve more attention than their one-cent strike price might initially suggest.
Why is the Ambler Road so important to the value of Trilogy’s mineral projects?
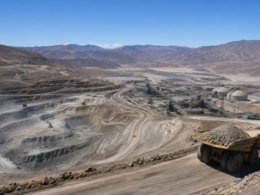
The Upper Kobuk Mineral Projects are located in a remote part of northwestern Alaska without conventional road access to the broader transportation network. Trilogy and South32 can delineate mineral resources and advance engineering without the road, but commercial mining becomes substantially more difficult when concentrates, equipment, fuel and supplies cannot move efficiently between the district and existing infrastructure. The proposed Ambler Access Project would provide an approximately 211-mile industrial-use-only connection to the Dalton Highway.
The road has therefore been one of the central external risks surrounding the Arctic and Bornite projects for years. Government revival and approval of the project materially changes the development pathway because mine engineering can increasingly be aligned with a defined infrastructure concept instead of assuming an uncertain future transport solution. Trilogy says federal and state permitting schedules for Arctic now establish a pathway toward a Record of Decision by September 2028, although that timetable remains subject to agency review and other permitting requirements.
The Department of War has explicitly connected its investment with the road’s national-security significance. That connection does not guarantee that every permit, financing requirement or legal challenge will be resolved favourably, but it materially increases federal alignment around infrastructure that is essential to developing a domestic source of copper, cobalt and other critical minerals.
How attractive are the economics of Trilogy’s Arctic project?
The latest feasibility study outlines a 13-year mine plan producing approximately 149 million pounds of copper annually together with significant zinc, lead, gold and silver by-products. On a 100% project basis, initial capital is estimated at US$1.177 billion, while total life-of-mine capital costs reach approximately US$1.719 billion including sustaining and closure expenditures. Post-tax NPV is estimated at US$1.108 billion using an 8% discount rate, with a 22.8% internal rate of return and 3.1-year payback period under the study assumptions.
Those numbers indicate a potentially economic project but also demonstrate why the US$35.6 million government investment should not be confused with construction financing. Trilogy owns only 50% of Ambler Metals, with South32 holding the other half, and the joint venture would still need to assemble a much larger package of equity, debt, offtake financing or strategic capital before Arctic could be built. The government investment primarily finances exploration, engineering and infrastructure-development work needed to move the district closer to a stage where construction financing becomes realistic.
Commodity sensitivity remains another major factor because copper, zinc, lead, gold and silver prices influence project value. The feasibility study’s NPV and IRR depend on assumptions around metal prices, operating costs, treatment charges, transport costs and the Ambler Road toll structure, meaning future economics can improve or deteriorate materially before a construction decision is reached.
Why is Bornite strategically important even though Arctic is further advanced?
The Upper Kobuk district is not a one-project story. Arctic is the higher-grade polymetallic project currently progressing through a defined permitting pathway, while the adjacent Bornite project contains significant copper mineralization together with cobalt and germanium potential. The Department of War specifically highlighted copper, cobalt and germanium when announcing the investment, demonstrating that government interest extends beyond the metals contained in the Arctic feasibility case alone.
That distinction matters because cobalt and germanium are strategically sensitive materials with important defence and advanced-electronics applications. A district capable of supporting multiple commodities can potentially justify shared road and infrastructure investment more easily than a single isolated mine, while exploration success at Bornite could extend the economic life and strategic relevance of the region beyond Arctic’s initial 13-year mine plan.
The broader UKMP land package spans approximately 190,929 hectares and remains underexplored outside the best-known Arctic and Bornite deposits. The US$35.6 million investment is specifically intended to support additional exploration, engineering and infrastructure development, giving the joint venture capital to test whether the district can support a larger long-term resource base.
Does the government investment solve Trilogy Metals’ financing problem?
It materially improves Trilogy’s liquidity position but does not eliminate future funding requirements. At May 31, Trilogy had approximately US$38.8 million of cash and US$38.3 million of adjusted working capital, while management said existing liquidity was sufficient to fund at least the following twelve months and the remaining corporate budget. Trilogy’s fiscal 2026 share of the Ambler Metals budget was US$17.5 million, with US$17 million funded by the time of the July quarterly filing.
The new US$17.8 million direct cash injection would increase Trilogy’s resources, although those proceeds must be invested in Ambler Metals rather than retained for unrestricted corporate use. South32’s matching reinvestment effectively doubles the project-level funding flowing into the joint venture, giving UKMP approximately US$35.6 million of new development capital if the transaction closes as expected.
Future requirements remain much larger because advancing Arctic through final permitting, detailed engineering and construction would require orders of magnitude more capital. Trilogy itself has acknowledged that additional financing beyond its near-term liquidity horizon may ultimately be required, with possible sources including equity, debt, convertible securities or other capital-market structures.
What control rights does the U.S. government receive beyond equity ownership?
The Department of War will have the right to designate an independent third-party director to Trilogy’s board until October 6, 2028 and to appoint a non-voting board observer while it holds at least eight million common shares. These governance rights give the government visibility into corporate strategy and project progress without converting the company into a government-controlled enterprise.
Trilogy has also agreed to a significant debt covenant. From closing until the earlier of January 1, 2029 or a change of control, the company cannot incur more than US$1 billion of aggregate third-party borrowing without prior written approval from the Department of War. The covenant is striking because it gives the government a direct influence over major financing decisions during the period when Arctic and the Ambler Road are expected to move through critical development milestones.
The US$1 billion threshold is high relative to Trilogy’s current corporate balance sheet but close to the US$1.177 billion initial capital estimate for Arctic. That does not mean the covenant automatically governs all project-level Ambler Metals financing in exactly the same manner, but it illustrates how closely the government’s strategic capital is being paired with oversight around future leverage.
Why is Washington taking equity instead of offering only a grant or loan?
Equity allows the government to participate economically if the mineral district becomes substantially more valuable. A grant would provide project support without upside, while a conventional loan would generate interest but could place repayment pressure on a pre-production mining company years before meaningful mine cash flow begins. The Trilogy structure gives Washington direct ownership and additional contingent equity exposure while directing the invested capital toward development of strategically important domestic mineral resources.
The approach is consistent with a broader U.S. policy shift toward direct industrial investment in critical-material supply chains. The Department of War announced several other strategic-equity and financing commitments during August, including investments related to rare earths and domestic alumina, suggesting that government ownership is increasingly being used as an industrial-policy tool rather than reserved for exceptional corporate rescues.
For Trilogy shareholders, that policy alignment has clear value because the largest risks around Arctic have historically involved infrastructure, permitting and capital rather than geological discovery alone. Government ownership does not remove those risks, but it places a major federal stakeholder directly inside the economic outcome of the project.
What remains unresolved after definitive agreements are signed?
The transaction has not yet closed and remains subject to customary closing conditions, with Trilogy expecting completion during September 2026. Even after closing, the government investment only advances exploration, engineering and infrastructure development rather than authorizing mine construction. Arctic still requires completion of federal and state permitting, the Ambler Road must advance through its own development process and a much larger construction financing package must eventually be assembled.
The most useful comparison is between the US$35.6 million strategic investment and Arctic’s US$1.177 billion initial capital estimate. The government funding equals only around 3% of that construction requirement, making it financially insufficient to build the mine but potentially highly influential in reducing the political and infrastructure risks that determine whether larger investors will provide the remaining capital.
That is why the definitive agreement matters more than its size alone. Washington is not simply writing a cheque to another exploration company; it is taking direct ownership, securing additional penny-priced equity rights, obtaining governance access and tying future upside to progress on the road needed to unlock an entire Alaskan mineral district.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.