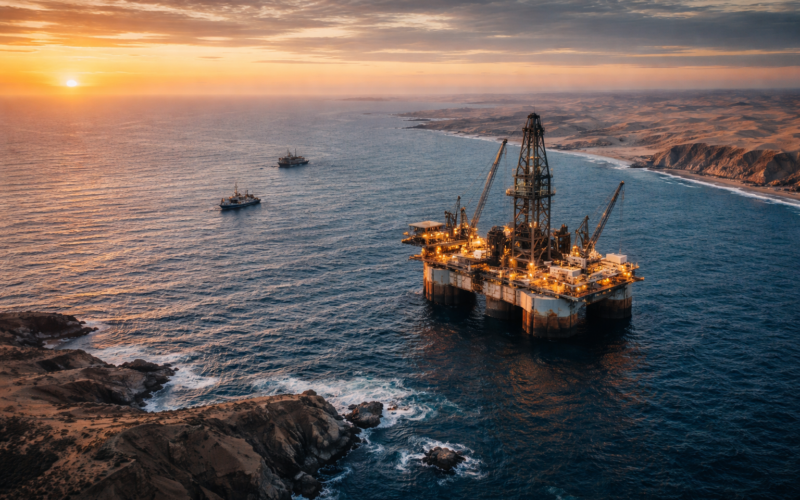
Transocean Ltd. (NYSE: RIG) has secured a two-year binding Letter of Award from Oil and Natural Gas Corporation Limited for the Dhirubhai Deepwater KG2 ultra-deepwater drillship in India, adding approximately $300 million of contract value and giving the rig a pathway to remain employed into early 2031 if all options are exercised. The programme is expected to begin in the first quarter of 2027 and includes two additional years of priced options. The disclosed $300 million firm value includes additional services and mobilisation fees, making it inappropriate to treat the headline amount as a pure drilling dayrate multiplied by contract days.
The award is commercially meaningful because Transocean entered August with approximately $6.7 billion of contracted backlog, excluding a separate conditional $1 billion Equinor agreement awaiting licence-partner approvals. On that base, the ONGC award is equivalent to roughly 4.5% of Transocean’s August 5 reported firm backlog before taking account of any other subsequent changes.
What does ONGC get from the Dhirubhai Deepwater KG2 contract?
Dhirubhai Deepwater KG2 is an ultra-deepwater drillship capable of operating in water depths of as much as 12,000 feet. The rig entered service in 2010 and has previously worked in both India and Brazil, including a period in which it set a world water-depth drilling record while operating for Reliance Industries Limited in Indian waters.
For Oil and Natural Gas Corporation Limited, the two-year term secures access to a high-specification floating rig at a time when offshore operators globally have been competing for modern deepwater equipment. The binding Letter of Award precedes the final contract documentation but establishes the principal commercial commitment and expected first-quarter 2027 start.
How significant is the $300m award for Transocean’s backlog?
Transocean reported $6.7 billion of backlog at August 5 after adding five firm fixtures worth approximately $292 million since its previous fleet report. Those contracts included work for Deepwater Conqueror, Deepwater Proteus, Deepwater Skyros, Transocean Norge and Transocean Equinox. The ONGC award announced two weeks later is slightly larger by itself than that entire five-fixture incremental package.
The comparison demonstrates why a two-year programme for a single high-specification drillship can be financially meaningful to an offshore contractor. Floating rigs carry large fixed operating and capital costs, so maintaining utilisation over multi-year periods can be more valuable than securing short contracts at temporarily higher rates if those contracts leave lengthy idle intervals between campaigns.
Transocean also has a conditional agreement with Equinor valued at about $1 billion for Transocean Enabler, Transocean Encourage and Transocean Endurance. If approved by the relevant licence partners, the Equinor programme plus the new ONGC award would represent approximately $1.3 billion of prospective or newly awarded work beyond the $6.7 billion backlog reported on August 5.
Why do the two years of priced options matter almost as much as the firm term?
The firm ONGC programme is expected to run for two years from the first quarter of 2027. Exercising both additional years could keep Dhirubhai Deepwater KG2 working in India into early 2031, extending employment visibility across roughly four years rather than forcing Transocean to remarket the asset after the initial programme.
Options are not guaranteed backlog and should not be valued as firm revenue until exercised. They can nevertheless have substantial strategic value because the customer and contractor establish an agreed commercial framework for extending work without starting a completely new procurement process. If ONGC’s drilling programme expands or wells take longer than initially anticipated, retaining the same drillship can also reduce mobilisation and crew-transition disruption.
What does the award reveal about India’s ultra-deepwater drilling market?
India has been attempting to increase domestic oil and gas exploration as declining mature-field production leaves the country heavily dependent on imported crude and LNG. Deepwater basins off India’s east coast remain a major part of that strategy, but the technical demands require high-specification drilling units, specialised subsea equipment and experienced service contractors.
Transocean already has long operating history in India. Dhirubhai Deepwater KG1 recently completed work for ONGC and has been scheduled for a Reliance Industries Limited programme after contract preparation, while KG2 now has a new ONGC pathway from 2027. Transocean’s fleet data therefore point to India becoming a sustained ultra-deepwater market for the contractor rather than a one-off deployment destination.
How strong is Transocean’s financial position as backlog grows?
Transocean reported second-quarter contract drilling revenue of $966 million, adjusted EBITDA of $312 million and free cash flow of $212 million. Revenue efficiency was 97%, while the company posted net income of $170 million. Those figures indicate that improving rig utilisation and higher-specification contracts are increasingly converting into cash flow, although offshore drilling remains a capital-intensive business with substantial financing requirements.
The backlog provides visibility but does not remove execution risk. Rigs must maintain mechanical reliability, mobilisation work must remain on schedule and customers must proceed with planned drilling campaigns. Contract extensions and options are particularly sensitive to drilling results, commodity prices and operator capital budgets.
Did the $300m ONGC award move Transocean shares?
Transocean shares rose 2.91% to $6.01 on August 20, the day the company announced the ONGC award, on trading volume of more than 36 million shares. The stock closed at $5.995 on August 21, down 0.25% for the session but still about 4.1% above its August 14 close of $5.76.
A single contract cannot explain all short-term price movement, particularly when crude markets and offshore-services sentiment are also influential, but the timing indicates a constructive initial market response. The more durable valuation question is whether Transocean can continue adding long-duration work at economic rates while converting backlog into free cash flow.
The ONGC agreement strengthens that case because it combines a meaningful $300 million firm commitment with options that could provide employment through early 2031. For a drillship owner, four potential years of utilisation are often more strategically valuable than the headline contract amount suggests.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.