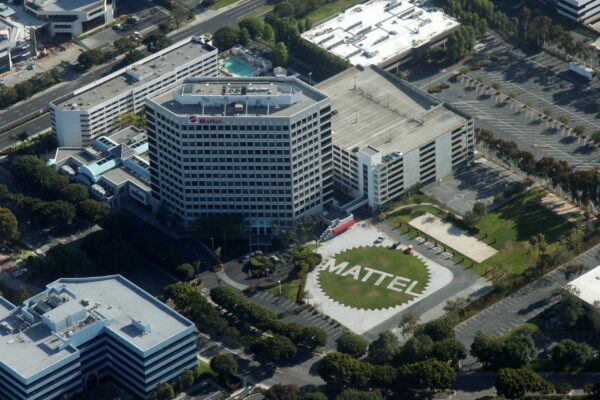
Mattel, Inc. (NASDAQ: MAT) has appointed former Amgen Chief Financial Officer Peter Griffith as Chief Financial Officer and a member of its board effective October 20, adding a second major leadership change only weeks after Roger Lynch became Chairman and Chief Executive Officer. Griffith succeeds Paul Ruh, who ceased serving as CFO on October 19 and will remain as Executive Advisor through December 31 to support the transition. The appointment comes after second-quarter net sales increased 10% to $1.13 billion while operating income dropped to $11 million from $79 million a year earlier, exposing a widening gap between top-line momentum and profitability. Griffith therefore joins Mattel at a point where financial leadership must do more than protect the balance sheet because the company is simultaneously investing in toys, entertainment, digital games, intellectual-property expansion and shareholder returns.
Why has Mattel recruited Peter Griffith only weeks after changing its chief executive?
Mattel’s latest finance appointment needs to be viewed alongside its unusually concentrated executive transition. Roger Lynch officially began as Chief Executive Officer on October 12 after Ynon Kreiz stepped down earlier in the month, and Griffith now becomes CFO little more than a week later. The new CEO and CFO will consequently develop their working relationship while also taking responsibility for a strategy largely designed under the previous leadership team.
Griffith brings experience that extends beyond conventional accounting and financial reporting. He served as Amgen’s Chief Financial Officer from 2020 until August 2026, overseeing financial strategy during a period that included major acquisitions, research investment and expansion of manufacturing capacity. Before Amgen, he spent more than two decades at EY, where his responsibilities included corporate development, finance, treasury and international strategic transactions, after earlier working in investment banking.
Mattel has also appointed Griffith directly to the board, giving him a broader governance role than a finance executive reporting only through management. That structure puts capital allocation, acquisitions, technology spending and strategic transactions closer to board-level decision-making at a time when Mattel is attempting to generate more value from intellectual property beyond physical toys.
The leadership pairing is therefore notable because Lynch also arrives with a media and technology background from Condé Nast rather than a traditional toy-company career. Mattel is effectively putting an executive experienced in media and digital transformation alongside a CFO whose background includes biotechnology, private equity, investment banking and corporate development. The combination suggests the next stage of Mattel’s strategy may place greater emphasis on disciplined investment around intellectual property rather than treating toy volumes as the sole measure of growth.
What do Mattel’s latest financial results reveal about the problem Peter Griffith inherits?
Mattel’s second-quarter results contained a striking divergence between revenue and earnings. Net sales increased 10% to $1.13 billion, or 9% in constant currency, demonstrating continued demand across parts of the portfolio. Gross margin, however, declined 270 basis points to 48.2%, while adjusted gross margin fell 260 basis points to 48.6%.
Operating income dropped to $11 million from $79 million in the prior-year quarter, while adjusted operating income declined to $39 million from $96 million. Mattel recorded a net loss of $18 million compared with net income of $53 million a year earlier, and adjusted earnings per share fell to $0.01 from $0.21. Those figures make margin recovery one of the clearest financial priorities for the new CFO.
The problem is not simply that expenses increased. Mattel operates a seasonal business with significant exposure to product mix, freight, sourcing costs, tariffs, retailer inventory decisions and promotional spending. Revenue growth can therefore fail to produce equivalent earnings growth if the incremental sales carry weaker margins or if cost inflation absorbs the benefit.
Griffith will need to help management determine which parts of the portfolio deserve additional investment and which activities generate insufficient returns. Mattel’s increasingly broad entertainment strategy makes that exercise more complicated because the company is no longer allocating capital only among physical toy brands. Films, digital games, consumer products, licensing and direct-to-consumer initiatives all compete for management attention and financial resources.
How does Mattel’s push beyond toys change the job facing its new CFO?
Mattel’s strategic ambition is to convert franchises such as Barbie, Hot Wheels, UNO, Masters of the Universe and Matchbox into broader intellectual-property businesses. The company has identified content, licensing, digital games and other experiences as potential higher-margin growth areas that can complement physical products. That creates opportunities to generate revenue from brands without carrying the same inventory and manufacturing exposure associated with traditional toys.
The economics of those businesses vary considerably. Licensing can produce attractive returns because third parties often fund much of the underlying production, while self-published games require development, customer acquisition and ongoing product investment. Film projects can create major brand visibility but also involve complex production and distribution economics depending on Mattel’s financial participation.
Mattel acquired the remaining 50% interest in mobile-games studio Mattel163 during the first half of 2026 for approximately $74.8 million net of acquired cash. The company has also launched its first self-published mobile game and placed another game into soft launch. Those investments demonstrate that digital expansion is moving beyond licensing brands to external developers.
Griffith therefore inherits a portfolio where capital needs to be compared across businesses with very different risk profiles. Investment in a new toy line may have relatively short inventory and retail feedback cycles, while entertainment and gaming projects can consume capital for years before their commercial outcome becomes clear. The finance organisation will increasingly need to establish return thresholds that allow Mattel to exploit its brands without spending merely to demonstrate that every intellectual property can exist across every medium.
Why does Peter Griffith’s capital-allocation background matter after Mattel spent heavily on buybacks?
Mattel entered 2026 with an aggressive shareholder-return programme. The board authorised a new $1.5 billion share-repurchase programme in February, and Mattel had spent approximately $300 million buying back shares during the first six months of the year. The company said in August that it continued to expect approximately $400 million of repurchases during 2026.
Those buybacks have occurred alongside investment in operations and digital expansion. Mattel spent approximately $125.8 million on capital expenditures during the first six months and another $74.8 million to acquire the remaining interest in Mattel163. Cash and equivalents consequently declined to approximately $523.9 million at June 30 from $1.24 billion at the end of 2025.
The fall in cash should not automatically be interpreted as financial distress because Mattel deliberately deployed capital through repurchases, investment and acquisition activity. It does, however, make prioritisation increasingly important. Every dollar used for buybacks is unavailable for acquisitions, debt reduction or internal investment unless operating cash generation replenishes the balance sheet.
Griffith’s experience at Amgen included financial management during large strategic transactions and substantial research investment, making capital allocation one of the clearest transferable parts of his background. Mattel’s challenge is different from biotechnology, but the underlying financial question is similar: how much capital should be committed to projects whose payoff may arrive several years later while still protecting flexibility for unexpected opportunities?
What does Peter Griffith’s compensation package reveal about Mattel’s expectations?
Mattel has structured Griffith’s compensation around both cash and long-term equity. His annual base salary is $1.3 million, with a target annual incentive equal to 100% of salary and the possibility of reaching as much as 200% beginning with the 2027 performance year. He will also receive a $1.4 million cash signing bonus.
The equity component is more consequential. Griffith is receiving a performance-based restricted-stock-unit award with a grant-date fair value of $3.3 million that depends partly on Mattel’s relative total shareholder return over three years. Vesting requires Mattel to achieve relative shareholder returns of at least the 55th percentile against S&P 500 constituents, subject to the terms of the award.
He will additionally receive $1 million of prorated 2026 restricted stock units, $2.5 million of 2027 restricted stock units and a further $2.5 million of 2027 performance stock units. The structure gives Griffith significant financial exposure to longer-term shareholder outcomes rather than rewarding only annual accounting performance.
That alignment is particularly relevant given Mattel’s current strategic breadth. A finance chief could improve near-term margins by cutting investment aggressively, but doing so might undermine entertainment, digital or brand-development initiatives with greater long-term potential. Conversely, spending heavily on growth projects can destroy shareholder value if expected returns never materialise. The equity structure creates an incentive to navigate that tension over several years rather than optimise one reporting period.
How does Paul Ruh’s exit differ from an abrupt CFO departure?
Paul Ruh ceased serving as CFO on October 19 but is remaining with Mattel as Executive Advisor through December 31. Mattel’s filing says his departure did not result from a disagreement with the company over operations, policies or practices, which is important because sudden finance departures can otherwise raise questions around reporting or governance.
Ruh will continue receiving his existing $950,000 annual base salary during the advisory period and remain eligible for the company’s 2026 incentive plan under his existing participation level. His continuing presence gives Griffith access to the outgoing finance chief through the year-end transition.
That overlap should reduce the operational risk of changing finance leadership ahead of a period that is particularly important for toy companies. The fourth quarter includes holiday demand and significant retailer activity, while finance teams also prepare year-end reporting, planning and budgeting. Changing CFOs in October would be considerably more disruptive without a structured transition.
The appointment should therefore be understood primarily as a strategic leadership reset rather than evidence of a disclosed accounting dispute. Griffith still needs to establish his priorities, but Mattel has provided continuity around the mechanics of the handover.
Why does Mattel’s October share-price recovery raise expectations for the new management team?
Mattel shares closed at $16.88 on October 19, down 1.86% for the session. The stock remained well below its 52-week high of $22.48 but had recovered materially from the $13.26 closing level recorded on September 18, representing an increase of roughly 27% over about a month.
Much of that period contained significant corporate developments, including the departure of Kreiz, Lynch’s appointment and broader speculation around Mattel’s strategic direction. It would be too strong to attribute the recovery to any single event because equity markets were simultaneously processing operating performance, leadership changes and external strategic interest.
The valuation nevertheless places greater attention on execution. Mattel’s market has already shown that investors can rapidly reassess the stock when expectations around leadership or strategic optionality change. Sustaining a higher valuation will require operating evidence rather than management appointments alone.
The October 19 closing price was recorded before Griffith formally began serving as CFO on October 20, so it should not be described as a market verdict on his performance. The next quarterly financial update and 2027 guidance will provide more useful indicators of how the new CEO-CFO team intends to approach margins, capital allocation and strategic investment.
What are the biggest financial decisions facing Roger Lynch and Peter Griffith together?
The first is profitability. Mattel needs to demonstrate that revenue expansion can once again produce stronger operating income rather than being absorbed by weaker gross margin and higher costs. Pricing, sourcing, product mix and operational efficiency will therefore remain central to the financial agenda.
The second is capital allocation. Mattel has substantial share-repurchase authorisation remaining while simultaneously building digital capabilities, pursuing entertainment projects and investing in its portfolio. Lynch and Griffith will need to determine whether buybacks continue at their existing pace as new growth opportunities compete for capital.
The third is intellectual-property monetisation. Mattel’s strategy assumes brands can generate value across more than toys, but investors will increasingly demand evidence that films, games, licensing and experiences produce attractive financial returns. Visibility into project economics may become more important as those businesses become a larger part of corporate strategy.
Finally, the new leadership team needs to preserve balance-sheet flexibility. Mattel’s franchise portfolio creates optionality, but optionality has the most value when management retains enough financial capacity to pursue opportunities during periods of weak consumer demand or market disruption. Griffith’s experience across finance, acquisitions and corporate development gives him a significant role in setting those boundaries.
What will prove that Mattel’s new CFO is improving financial execution?
Gross margin provides one of the clearest near-term measures. Mattel‘s second-quarter revenue growth was overshadowed by the 270-basis-point decline in reported gross margin, so stabilisation or improvement would show that stronger sales are beginning to translate more effectively into earnings.
Operating income and free cash generation will provide additional evidence. Revenue growth has limited shareholder value if the company needs progressively more capital to generate each dollar of additional sales. Improved operating leverage would strengthen the argument that Mattel’s brand-centric strategy can scale financially.
Investors should also watch the allocation of cash among repurchases, acquisitions, digital investment and other strategic uses. Griffith’s appointment becomes particularly consequential if Mattel begins making larger transactions or materially changes the pace of its share-buyback programme.
The leadership reset has now put a new chief executive and a new chief financial officer in place within days of each other. That creates a cleaner line of accountability going into 2027. Mattel no longer needs to prove that its brands can attract consumers across toys and entertainment; the next test is whether Lynch and Griffith can turn that brand strength into more consistent margins, disciplined investment and sustainable cash returns.
What are the key takeaways from Mattel appointing Peter Griffith as CFO?
- Peter Griffith becomes Mattel Chief Financial Officer and a board director effective October 20, 2026.
- Griffith previously served as Amgen Chief Financial Officer from 2020 through August 2026.
- Paul Ruh ceased serving as CFO on October 19 and will remain Executive Advisor through December 31.
- Mattel says Ruh’s departure was not caused by a disagreement over company operations or policies.
- Roger Lynch began serving as Mattel CEO on October 12 after succeeding Ynon Kreiz.
- Second-quarter Mattel sales increased 10% to approximately $1.13 billion.
- Operating income fell to $11 million while adjusted operating income declined to $39 million.
- Gross margin decreased 270 basis points to 48.2%.
- Mattel had $523.9 million of cash at June 30 after spending on share repurchases, capital investment and the Mattel163 acquisition.
- Griffith’s priorities will include margin recovery, capital allocation, digital investment and balancing shareholder returns against longer-term IP expansion.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.