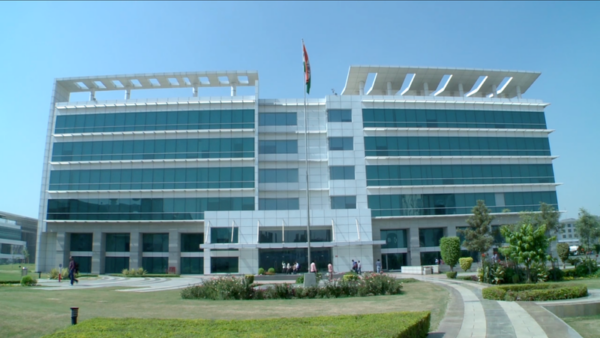
Juniper Hotels Limited (NSE: JUNIPER) has approved the proposed acquisition of the 287-room Novotel Imagicaa hotel in Khopoli, Maharashtra, from Imagicaaworld Entertainment Limited (NSE: IMAGICAA) for ₹248 crore, adding an operating hospitality asset in the strategically important Mumbai-Pune corridor while allowing the seller to redirect capital toward its higher-margin amusement and entertainment businesses.
The transaction will be structured as a slump sale of the hotel undertaking as a going concern and values the property at approximately ₹86 lakh per room. Juniper Hotels and Imagicaaworld Entertainment Limited have entered into a binding memorandum of understanding, although completion remains subject to definitive agreements, shareholder and regulatory approvals and other customary conditions. The companies are targeting completion by March 31, 2027.
The market initially viewed the transaction more favourably for the buyer than the seller. Juniper Hotels shares gained more than 2% in early trading on September 17 and touched ₹219.07 on the National Stock Exchange, while Imagicaaworld Entertainment shares fell as much as 4.3% to ₹50.70 as investors weighed the immediate cash proceeds against the loss of recurring hotel revenue.
Why is Juniper Hotels paying ₹248 crore for Novotel Imagicaa?
Novotel Imagicaa is an established operating property rather than a greenfield hotel requiring years of construction and development spending. The hotel has 287 rooms and occupies approximately 11 acres in Khopoli, with a built-up area of about 280,000 square feet. Its facilities include restaurants, meeting areas, banquet infrastructure and recreational amenities, giving Juniper Hotels an asset capable of contributing revenue and cash flow after completion rather than waiting for a lengthy development cycle.
The location is another important part of the acquisition rationale. Novotel Imagicaa sits adjacent to the Imagicaa Theme Park and Water Park and is positioned between the large Mumbai and Pune metropolitan markets. That gives the property access to leisure guests visiting the entertainment destination as well as weddings, corporate events, conferences and other meetings, incentives, conferences and exhibitions demand.
Juniper Hotels also sees opportunities to improve the existing property rather than simply operate it in its present form. The company has indicated that additional banquet facilities and an eventual repositioning toward the upper-upscale segment could increase the hotel’s revenue potential. Those initiatives could allow Juniper Hotels to lift room rates, attract higher-value events and broaden demand beyond visitors whose primary purpose is attending the adjacent parks.
What does the ₹86 lakh-per-room valuation tell investors?
The ₹248 crore purchase consideration works out to approximately ₹86 lakh for each of the hotel’s 287 rooms. Per-key valuations are commonly used in hotel transactions because they allow investors to compare acquisition costs across properties of different sizes, although land value, location, brand, age, ancillary facilities and redevelopment opportunities can make direct comparisons imperfect.
In this case, Juniper Hotels is acquiring more than the guest rooms. The transaction includes an approximately 11-acre hospitality site and substantial built infrastructure in a leisure destination that already attracts visitors from two of India’s largest urban markets. An operating hotel also removes much of the construction and opening risk associated with building a comparable property from the ground up.
The acquisition therefore fits Juniper Hotels’ broader strategy of owning hospitality real estate where the company sees scope to improve operating performance and underlying asset value. The company is already a major owner of Hyatt-affiliated properties in India, including Grand Hyatt Mumbai and Andaz Delhi, and has been expanding through both development projects and portfolio additions.
Why is Imagicaaworld Entertainment selling a hotel next to its own theme park?
Imagicaaworld Entertainment Limited is presenting the transaction as a capital-allocation decision rather than a retreat from destination hospitality. The company intends to use the proceeds to strengthen its balance sheet and invest in its core amusement park portfolio, including expansion into new geographies, new attractions at existing parks and further investment in indoor entertainment concepts.
The margin difference between the businesses helps explain the strategy. Imagicaaworld Entertainment has said its parks operate at EBITDA margins of approximately 40% to 45%, compared with roughly 25% to 30% for the hotel business. Selling the lower-margin hospitality asset could therefore improve the group’s overall margin mix if the released capital can be reinvested successfully into higher-return entertainment projects.
Importantly, Imagicaaworld Entertainment does not expect the relationship between the hotel and the adjacent parks to disappear after the sale. The companies intend to preserve the operational synergies between Novotel Imagicaa and the wider entertainment destination, meaning hotel guests can continue to form an important source of multi-day visitors for the parks even though the property will have a different owner.
Why did Juniper Hotels shares rise while Imagicaaworld shares fell?
Juniper Hotels shares climbed more than 2% in early trading following the announcement, reaching an intraday high of ₹219.07 compared with the previous close of ₹214.32. The stock had already gained around 13% over the preceding month, although it remained approximately 12% lower for 2026 at the time of the announcement.
The positive initial reaction suggests investors see benefits in acquiring a functioning hotel at a recognised leisure destination with potential for further repositioning. Juniper Hotels avoids the long gestation period associated with a new hotel development while adding exposure to a corridor linking Mumbai and Pune, two markets capable of generating leisure, wedding, corporate and weekend travel demand.
Imagicaaworld Entertainment shares moved in the opposite direction, falling as much as 4.3% to ₹50.70 during September 17 trading. The reaction highlights the trade-off embedded in the sale: Imagicaaworld receives ₹248 crore of capital and can focus more heavily on higher-margin entertainment activities, but it also gives up ownership of an established asset capable of generating recurring hospitality revenue.
Could Juniper Hotels extract more value from the Novotel Imagicaa property?
The potential upside rests partly on asset management. Juniper Hotels has indicated that it will evaluate additional banquet space and opportunities to reposition the hotel at a higher market level. Banqueting can be particularly valuable for large destination hotels because weddings, corporate gatherings and social events generate revenue across rooms, food and beverage and event facilities rather than relying solely on overnight accommodation.
The property’s proximity to the Imagicaa parks also creates an unusual demand profile. Families visiting from Mumbai, Pune and other regional markets can convert single-day park visits into overnight or weekend stays, while the hotel can use the entertainment complex as an attraction that differentiates it from conventional business or resort properties in the region.
If Juniper Hotels can improve pricing, events revenue and occupancy while preserving the relationship with the adjacent parks, the ₹248 crore acquisition could become more valuable than a straightforward purchase of an existing 287-room hotel. The key execution challenge will be achieving those improvements without disrupting the customer proposition that currently connects the property with the wider Imagicaa destination.
What needs to happen before the Novotel Imagicaa acquisition closes?
The transaction is not yet a completed asset sale. Juniper Hotels and Imagicaaworld Entertainment Limited have entered into a binding memorandum of understanding, but definitive transaction documents still need to be executed. Applicable statutory, regulatory, lender and shareholder approvals must also be obtained before ownership can transfer.
The companies are targeting completion by March 31, 2027. Until then, investors will be watching the final transaction agreements, financing arrangements and any additional details on Juniper Hotels’ planned capital expenditure after the acquisition.
The deal ultimately gives both companies a different strategic benefit. Juniper Hotels gains an immediately operating hospitality asset with redevelopment and positioning potential in the Mumbai-Pune corridor, while Imagicaaworld Entertainment converts a lower-margin hotel into capital that can be redeployed toward amusement parks and indoor entertainment. Whether both sides create value will depend on what happens after the ₹248 crore changes hands: Juniper must improve the hotel’s economics, while Imagicaaworld must earn attractive returns on the capital it releases.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.