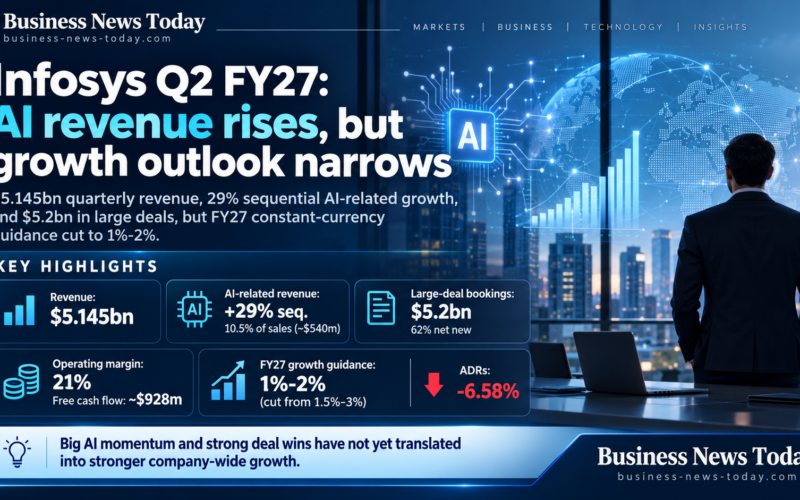
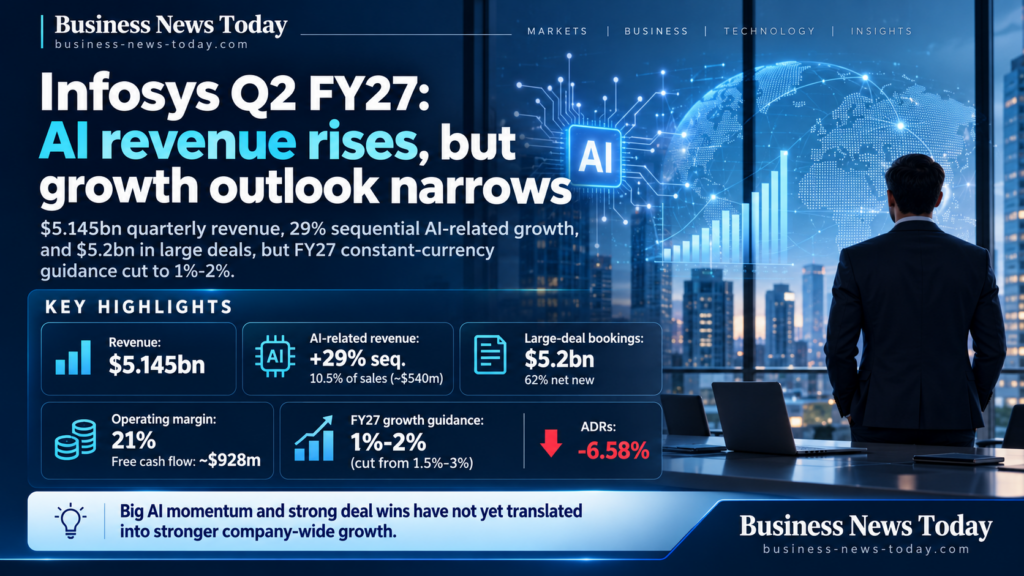
Infosys Limited (NSE: INFY; BSE: 500209; NYSE: INFY), the Bengaluru-headquartered technology consulting and IT services company, reported second-quarter financial year 2027 revenue of $5.145 billion, alongside 29% sequential growth in artificial intelligence-related revenue and $5.2 billion in large-deal bookings. Announced on October 23, 2026, the results showed operating margin remaining at 21%, while management reduced its full-year constant-currency revenue growth outlook to 1% to 2% from the previous range of 1.5% to 3%. Infosys American depositary receipts fell 6.6% during the subsequent US trading session, highlighting investor concern that accelerating AI-related business may not translate into stronger company-wide growth. The results expose a central challenge for large technology services providers: capturing new enterprise AI spending while customers reduce discretionary projects, renegotiate pricing and demand a greater share of automation-driven productivity gains.
Why did Infosys reduce its fiscal 2027 revenue guidance despite stronger AI revenue and large-deal bookings?
Infosys reported 1.5% year-on-year and 1.2% sequential revenue growth in constant currency during the September quarter. The figures indicate modest underlying expansion despite a substantially larger increase in rupee-denominated revenue, which rose 10.7% year on year to ₹49,244 crore. Currency movements and differences between reporting bases explain why domestic-currency financial growth appears considerably stronger than the underlying constant-currency performance.
Management lowered its fiscal 2027 constant-currency revenue growth forecast to 1% to 2%, reducing the midpoint from 2.25% to 1.5%. The 75-basis-point reduction indicates that the company expects weaker revenue conditions than those incorporated into its previous annual outlook. Importantly, the revised guidance is not a forecast of declining total revenue, but it does imply slower expansion than management previously anticipated.
The company identified continued caution among enterprise customers, particularly in North America, where demand has been affected by reduced discretionary spending and changes in technology priorities. Retail and technology-sector customers have been especially selective about project expenditure, while the adoption of artificial intelligence is influencing the economics of established services. These conditions can delay the conversion of signed contracts into recognised revenue.
Infosys also reported large-deal total contract value of $5.2 billion, with approximately 62% described as net new business. The bookings included a transaction valued at more than $2 billion, indicating that the company remains capable of securing substantial enterprise transformation commitments. However, contract value represents services scheduled across future periods rather than revenue that will necessarily appear immediately in quarterly financial results.
A large multiyear agreement may require extensive transition and implementation work before reaching its expected delivery scale. Revenue also depends on the timing of customer expenditure, contractual pricing and operational milestones. Consequently, strong deal bookings and reduced near-term revenue guidance can coexist without indicating that either disclosure is necessarily inconsistent.
How much of Infosys’s $5.145 billion quarterly revenue now comes from artificial intelligence services?
Artificial intelligence-related services accounted for 10.5% of Infosys’s quarterly revenue, compared with a sequential growth rate of 29% for the category. Applying the disclosed percentage to total revenue of $5.145 billion implies approximately $540 million in quarterly AI-related revenue. This calculation illustrates the category’s commercial scale, although it should not be interpreted as a separately audited segment result.
If that quarterly contribution were simply multiplied by four, it would represent an annualised amount of approximately $2.16 billion. Such an annualisation is not a company forecast and assumes no change in customer demand, revenue classification or business mix. Its value is primarily as a reference for understanding how substantial AI-related services have become within the wider organisation.
The faster-growing category encompasses activities associated with enterprise AI adoption, including data engineering, application integration, automation and technology transformation. Customers may purchase these services as part of broader programmes rather than through separately identified AI contracts. Infosys’s reported category therefore reflects commercial activity linked to AI adoption, not necessarily a new standalone software business with independent subscription economics.
The contrast with company-wide growth suggests that some legacy services are expanding more slowly or facing pressure as customers redirect spending. Artificial intelligence can reduce labour requirements for selected software development, support and business-process activities, potentially lowering the amount customers are willing to pay for traditional delivery models. Infosys must capture sufficient value from new services to compensate for any reduction in existing work.
This transition may also change pricing arrangements. Enterprise clients increasingly seek agreements tied to measurable business outcomes rather than the number of people assigned to an engagement. Such contracts can reward efficient technology delivery, but they also shift more commercial responsibility toward providers when productivity improvements are shared with customers.
Can Infosys preserve its 21% operating margin while customers demand AI productivity savings?
Infosys reported operating profit of ₹10,330 crore, compared with ₹9,353 crore during the corresponding quarter last year. Operating margin remained at 21%, broadly unchanged from the previous year and slightly below the 21.1% recorded in the June quarter. The performance indicates that cost management and business mix have so far helped the company maintain profitability despite subdued constant-currency revenue growth.
Net profit increased 6.2% year on year to ₹7,823 crore, while earnings per share advanced 8.7% to ₹19.32. The difference between earnings growth and revenue growth in constant currency illustrates why investors must examine profitability alongside headline sales. However, currency movements, taxation and other financial factors also affect reported earnings comparisons.
Free cash flow reached approximately $928 million during the quarter, equivalent to 113.3% of net profit under the company’s disclosed calculation. Strong cash conversion provides flexibility to finance technology investment, employee development and shareholder distributions without depending entirely on external capital. Infosys also announced an interim dividend of ₹26 per share, subject to the disclosed entitlement and payment timetable.
Management retained its full-year operating margin guidance of 20% to 22%. That decision indicates confidence in the company’s ability to manage costs even though revenue growth expectations have weakened. However, future margins will depend on pricing pressure, employee utilisation, wage costs and the investment required to develop AI capabilities.
The economics of artificial intelligence services may become particularly important as the business mix changes. Automation can improve delivery productivity, but customers may negotiate contracts that transfer part of those savings to them. Infosys’s financial advantage will depend on whether it can use its technology investments to improve operating efficiency faster than service pricing declines.
What does Infosys’s $5.2 billion large-deal pipeline reveal about North American enterprise spending?
The quarter’s $5.2 billion in large-deal bookings represented substantial growth from the approximately $3.1 billion reported in the corresponding period last year. The presence of a single agreement exceeding $2 billion demonstrates that major enterprises continue committing to long-duration technology transformation even while reducing selected discretionary projects. Large transactions may also involve the consolidation of services previously supplied by several vendors.
The North American market remains particularly important because it accounts for more than half of Infosys’s revenue. The region experienced a 1.5% decline in the latest quarter, according to contemporary earnings reporting, reflecting the impact of weaker technology and retail spending. This creates geographical exposure to changes in US enterprise investment, even as financial services and selected other industries continue purchasing technology services.
Infosys’s recently announced expansion of its collaboration with Truist Financial Corporation illustrates another form of enterprise opportunity. The partnership supports the development of an AI-oriented global capability centre in Hyderabad, bringing together technology operations, talent and transformation services. Such arrangements can deepen customer relationships, but their financial value depends on the scope of services and the extent to which work becomes incremental rather than replacing existing contracts.
Large outsourcing and transformation contracts increasingly involve complex migration requirements. Transition expenses may arise before the full anticipated revenue is recognised, potentially influencing short-term margins. The commercial value of strong bookings will therefore become clearer as Infosys reports subsequent revenue conversion and profitability.
Why did Infosys American depositary receipts fall sharply even though Indian shares closed almost unchanged?
Infosys shares closed at ₹1,153.80 on the National Stock Exchange of India on October 23, advancing approximately 0.04% during the session. The company’s results were announced after the regular Indian trading session, meaning the domestic closing price did not fully capture the market’s response to the published earnings and revised guidance.
The company’s New York-listed American depositary receipts subsequently closed at $12.35, declining 6.58% from $13.22 in the preceding US session. The timing difference is essential when interpreting the reaction because comparing the two markets without accounting for the announcement schedule could create a misleading impression of conflicting investor sentiment. The US decline coincided with the guidance reduction and concerns about weaker technology services demand.
Indian shares had also been trading substantially below their reported 52-week high of ₹1,728. The October 23 closing price remained above the corresponding low of approximately ₹980, while the stock had experienced a partial recovery during the preceding month. The latest earnings announcement therefore arrived against an already challenging longer-term valuation environment.
The results present two different financial narratives. Infosys is securing large enterprise contracts and expanding AI-related business rapidly, but these developments have not yet produced a comparable improvement in overall constant-currency growth. Investors appear to be assigning greater weight to the lower annual outlook than to the strength of the AI category.
Infosys has demonstrated that it can participate meaningfully in enterprise AI adoption while maintaining operating margins and cash generation. The next measurable test will be whether its $5.2 billion deal pipeline and growing AI-related services translate into stronger North American revenue and an improved company-wide growth trajectory. Sustained sequential growth and continued margin stability would provide more convincing evidence of commercial recovery than another increase in AI revenue alone.
Key takeaways from Infosys Q2 FY27 results, AI revenue growth and reduced earnings guidance
- Infosys reported quarterly revenue of $5.145 billion.
- Constant-currency revenue increased 1.5% year on year and 1.2% sequentially.
- AI-related revenue grew 29% sequentially and contributed 10.5% of sales.
- Large-deal bookings reached $5.2 billion, with approximately 62% classified as net new.
- Fiscal 2027 constant-currency growth guidance was reduced to 1% to 2%.
- Operating margin remained stable at 21%.
- Quarterly net profit increased 6.2% to ₹7,823 crore.
- Free cash flow reached approximately $928 million.
- Infosys American depositary receipts fell 6.58% after the earnings announcement.
- Revenue conversion from large deals and stronger North American demand will be important evidence of recovery.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.