Generac Holdings Inc. (NYSE: GNRC) surged 18.3% to $207.23 on September 17 after disclosing a long-term supply agreement with Amazon.com covering backup generators for Amazon data centres. Initial deliveries scheduled for 2027 and 2028 are expected to total approximately $2.4 billion, while a warrant agreement can vest progressively as cumulative Amazon payments to Generac reach as much as $8 billion. The shares held virtually all of that gain on September 18, closing at $207.44.
The deal is potentially transformative because Generac has historically been associated primarily with residential and commercial backup generators rather than hyperscale data centres. Artificial-intelligence infrastructure is changing that perception: enormous computing campuses require reliable backup power measured in tens or hundreds of megawatts, giving industrial power equipment an increasingly direct link to AI capital spending.
How large is the $2.4 billion Amazon commitment relative to Generac?
Generac generated about $4.2 billion of revenue during 2025, so $2.4 billion of initial deliveries across 2027 and 2028 is equivalent to more than half of one recent year’s revenue.
Spread evenly across those two years, the initial Amazon programme would average roughly $1.2 billion annually before considering any additional purchases. That alone would be large enough to make data centres one of Generac’s most important end markets.
The longer-term structure could be considerably bigger. Amazon received a warrant covering up to 1,693,745 Generac shares at an exercise price of approximately $200.93. A portion vested immediately, while the remainder vests in stages as Amazon makes aggregate qualifying payments of up to $8 billion for backup generators.
This does not guarantee $8 billion of future sales. The warrant mechanism creates incentives around higher cumulative purchasing, but actual orders depend on Amazon’s data-centre expansion and other contractual conditions.
Still, moving from $2.4 billion of committed initial deliveries to a framework accommodating $8 billion illustrates the scale of opportunity Generac is positioning for.
Why does Amazon need so many generators if data centres normally connect to the electricity grid?
Hyperscale computing facilities cannot tolerate lengthy interruptions. AI workloads involve enormous amounts of expensive computing hardware and mission-critical services, so operators need backup generation capable of supporting facilities when utility power fails or becomes unstable.
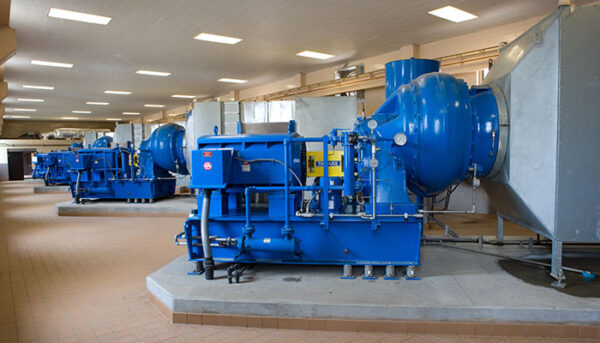
The physical size of new data centres is also expanding. Individual campuses increasingly consume electricity comparable with industrial facilities or small cities, which means backup-power requirements are moving beyond the smaller generator categories historically associated with commercial buildings.
Generac has already invested in larger megawatt-class systems and acquired manufacturing capacity to expand output. The Amazon agreement effectively validates that strategy by linking future production to one of the world’s largest cloud and AI infrastructure developers.
Power availability has become one of the constraints on artificial-intelligence infrastructure expansion. That moves companies supplying generators, switchgear, transformers, cooling equipment and electrical systems closer to the centre of the AI investment cycle.
Why did Generac give Amazon warrants as part of the transaction?
Warrants align the customer with the supplier’s long-term growth. Amazon can acquire Generac shares at roughly $200.93 if vesting conditions are satisfied, meaning Amazon benefits financially if Generac’s equity value increases while Amazon becomes a larger customer.
Only 307,954 warrant shares vested immediately. The remainder is tied to cumulative payments received from Amazon and affiliates, giving Generac a direct commercial offset to future dilution.
At the September 18 closing price of $207.44, the warrant exercise price sits close to the market price after the deal rally. That is very different from granting a deeply discounted option that immediately transfers substantial value to the customer.
Dilution could still reach roughly 1.7 million shares if the full warrant ultimately vests and is exercised. Investors should therefore compare future dilution against the profit produced by potentially billions of dollars of additional Amazon purchases.
If the programme approaches the $8 billion vesting threshold, the incremental earnings opportunity would likely matter far more than the share issuance itself.
Does the Amazon deal fundamentally change Generac’s growth narrative?
It broadens it substantially. Generac built its reputation around homeowners and businesses seeking resilience against power outages. That market remains important and can benefit from aging grids, extreme weather and electrification.
Data centres create a second structural growth engine with very different customer economics. Contracts are larger, customers are more concentrated and technical requirements are greater, but hyperscalers have enormous capital budgets.
Before the Amazon disclosure, Generac had already described large-megawatt data-centre power as a major opportunity and was expanding manufacturing capacity. The new agreement converts part of that opportunity from a presentation slide into contracted demand.
The danger is customer concentration. A programme large enough to move consolidated revenue significantly also makes execution against one customer more important. Production delays, changing data-centre designs or shifts in Amazon’s infrastructure plans could therefore affect expectations dramatically.
Is the 18% Generac rally already pricing in too much AI optimism?
The September 17 close of $207.23 remained far below Generac’s roughly $296 52-week high despite the enormous one-day move. That means the Amazon deal repaired part of a previous valuation decline rather than pushing the stock immediately into uncharted territory.
The share price also finished well below its $231.89 intraday high on announcement day. Investors initially pushed Generac up by more than 30% before the stock settled at an 18% gain, suggesting substantial disagreement over how much future profit should be capitalised immediately.
That caution is reasonable. Investors know $2.4 billion of deliveries is expected, but margins, production investment and the pace of additional Amazon purchasing will determine economic value.
Generac has nevertheless acquired something difficult to replicate: a flagship hyperscale customer validating its move into large data-centre power. The next question is whether other cloud and AI operators follow.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.