Diageo plc (LSE: DGE) reported first-quarter fiscal 2027 net sales of $4.931 billion, an increase of 1.2% from $4.875 billion a year earlier, as organic sales growth returned despite continued weakness in North America. The British spirits and beer producer reported organic net sales growth of 1.4%, although the figure falls to 0.6% after excluding the contribution of East African Breweries Limited. The November 5, 2026, update represents an early test of Chief Executive Officer Dave Lewis’s restructuring programme.
The results offered some encouragement after an extended period of weak consumer demand and pressure on premium spirits sales. Diageo’s performance exceeded market expectations for a decline in organic revenue, while the North American business performed less poorly than analysts had anticipated. Shares responded positively, with the company’s United States-listed depositary securities advancing approximately 2.6% during the November 5 session.
However, the financial improvement remains modest. Organic volume growth excluding East African Breweries Limited was negative 0.1%, while price and product mix contributed 0.7 percentage points. Management also maintained its forecast for broadly flat full-year organic sales and approximately $2 billion in free cash flow, compared with $3.2 billion in fiscal 2026.
Why is Diageo’s 1.4% organic sales growth less convincing than it initially appears?
Diageo’s first-quarter results show reported net sales growth of 1.2% and organic growth of 1.4%. The difference reflects adjustments for currency movements, disposals and other factors affecting comparisons. However, the more important distinction concerns the contribution of East African Breweries Limited to the consolidated organic result.
East African Breweries Limited contributed approximately 0.8 percentage points to Diageo’s organic sales growth. Excluding that business, group organic revenue increased just 0.6%, supported by a 0.7% improvement in price and product mix against a 0.1% decline in volumes. The figures suggest that the underlying business has broadly stabilised without delivering a convincing volume-led recovery.
This distinction matters because a sustainable recovery in consumer beverages generally benefits from improving demand as well as pricing. Revenue can increase when customers purchase more expensive products or when a company raises prices, but the strategy becomes harder to sustain if consumption volumes continue declining. Diageo must therefore demonstrate that the improvement eventually extends to the quantity of products sold.
The group’s trading performance was also uneven across regions. Latin America and the Caribbean and Asia-Pacific delivered mid-single-digit organic growth, while India and Europe, the Middle East and Africa reported low-single-digit increases. These results indicate that Diageo’s international portfolio continues providing growth opportunities despite weakness in its largest market.
For investors, the latest figures represent progress from a difficult trading environment rather than proof of a completed turnaround. The company’s future results need to show both stronger underlying volumes and an improved contribution from markets currently under pressure.
Why does North America remain Diageo’s most important turnaround challenge?
Diageo reported a mid-single-digit organic net sales decline in North America during the first quarter. Reuters reported a 3.6% decrease, considerably less severe than the 6.7% decline anticipated in a company-compiled analyst survey. The smaller-than-expected contraction helped support the positive investor reaction despite the region remaining in negative territory.
North America is strategically important because of its scale and its role in the premium spirits market. Diageo’s brands compete across whisky, tequila, vodka and other categories where consumer spending, distributor inventory and changing consumption preferences influence sales. Weakness in the market can materially affect the group’s growth and profitability even when other regions are performing better.
Management expects North American organic sales to decline by a mid-single-digit percentage across fiscal 2027, assuming that the broader market contracts by approximately 3%. This forecast indicates that the company is planning for continued pressure rather than an immediate return to growth. It also makes market-share improvement a particularly important measure of management’s progress.
Diageo is seeking to strengthen competitiveness through portfolio, pricing and operating changes. These actions may improve the company’s position relative to rivals, but the results will depend on whether consumers respond to the revised offering. More competitive prices can help restore sales volumes while simultaneously putting pressure on revenue per unit and margins.
The challenge is therefore to balance market-share recovery with profitability. Aggressive discounting might lift near-term volumes without improving economic returns, while maintaining premium pricing in a weakening market risks further losses of customers. Diageo’s ability to find that balance will be central to judging its turnaround.
Can stronger whisky and Guinness sales offset pressure in other categories?
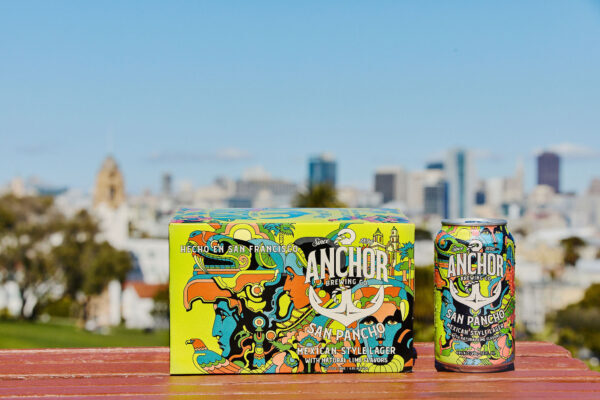
Diageo highlighted growth in whisky, Guinness and Smirnoff ready-to-drink products during the quarter. These categories provide exposure to different consumer preferences, consumption occasions and geographic markets. Their performance demonstrates the importance of Diageo’s diversified brand portfolio at a time when some spirits categories are under pressure.
Guinness provides a different growth profile from premium tequila or other distilled spirits. Beer consumption, brand engagement and distribution economics are influenced by factors that do not always move in line with the broader premium spirits market. Stronger performance in one category can therefore offset weakness elsewhere, although it cannot automatically compensate for declines in a large regional business.
Whisky remains important because Diageo operates across a wide range of international markets and price points. Demand can vary between established markets and developing consumer economies, while premium products are more sensitive to discretionary spending. The company must continually balance growth ambitions against inventory management, particularly for products requiring long production and ageing cycles.
Ready-to-drink products provide another potential opportunity through convenient formats and different purchasing occasions. However, growth within selected brands does not necessarily establish that the overall portfolio has returned to strong demand. Investors need to evaluate category performance alongside consolidated volumes, pricing and margins.
Diageo’s latest trading update suggests that brand diversification remains valuable, but the company has not yet demonstrated a broad-based acceleration. Future disclosures will need to establish whether stronger categories can maintain momentum while weaker businesses recover.
How will Diageo’s restructuring affect operating profit and free cash flow?
Diageo maintained its forecast for low- to mid-single-digit organic operating profit growth in fiscal 2027. The outlook includes expected benefits from two savings initiatives: an approximately $850 million operating-framework programme and a separate $150 million supply-chain programme. Management expects around 40% of the first programme’s savings and 25% of the second programme’s savings to contribute during the financial year.
These plans suggest that cost reduction will be an important driver of earnings improvement while organic revenue remains broadly flat. Operating efficiencies can strengthen margins, but their ultimate value depends on whether the company can implement them without damaging production reliability, distribution or brand investment. Savings targets also need to be distinguished from actual cash savings already realised.
The company expects approximately $850 million in exceptional cash costs associated with its operating-framework and supply-chain initiatives during fiscal 2027. Consequently, its free-cash-flow guidance stands at approximately $2 billion, compared with $3.2 billion in fiscal 2026, excluding cash proceeds from the East African Breweries Limited transaction. The projected reduction is substantial despite management’s expectation of improving underlying operating profit.
Diageo also expects capital expenditure of approximately $1.25 billion, compared with $1.2 billion in the preceding financial year. The company must therefore support ongoing investment while absorbing restructuring expenditure and managing its debt obligations. A successful turnaround would eventually produce higher recurring free cash flow after exceptional implementation costs decline.
The distinction between accounting benefits and cash requirements is particularly important. Restructuring can improve future operating profit while temporarily weakening cash generation, especially when severance, systems changes and other implementation expenses are concentrated in the initial period. Investors should track both the achievement of savings and the cash spent delivering them.
What role will asset disposals play in Diageo’s balance-sheet recovery?
Diageo expects its adjusted net debt-to-EBITDA ratio to finish fiscal 2027 around the midpoint of its target range of 2.5 to 3 times. However, that expectation assumes successful completion of the East African Breweries Limited and Royal Challengers Bengaluru transactions. The forecast is consequently conditional rather than a guaranteed debt-reduction outcome.
The Royal Challengers Bengaluru transaction involves the proposed disposal of the cricket franchise held through Diageo’s Indian subsidiary, United Spirits Limited. The transaction forms part of a broader effort to concentrate capital and management attention on core beverage operations. Because the deal was announced earlier in 2026, the November trading update does not represent a newly announced sale.
The anticipated disposal proceeds could strengthen the balance sheet, but asset sales are not equivalent to recurring operating cash generation. Once businesses are sold, their future earnings and cash contributions may also cease to form part of the consolidated group. The financial impact therefore depends on transaction proceeds, completion costs, debt reduction and the earnings relinquished.
For shareholders, the key question is whether a leaner Diageo can improve organic growth and operating efficiency after portfolio rationalisation. Stronger leverage metrics achieved through disposals would provide financial flexibility, but a more durable recovery requires improvement in the underlying beverages business.
Diageo’s first-quarter update represents a modest step towards stabilisation rather than a decisive reversal of its challenges. Investors welcomed better-than-expected sales, but negative North American growth, weak volumes and substantial restructuring costs remain important concerns. The strongest evidence of a successful turnaround will come from sustained volume recovery, market-share improvement and free cash flow rising after the restructuring programme progresses.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.