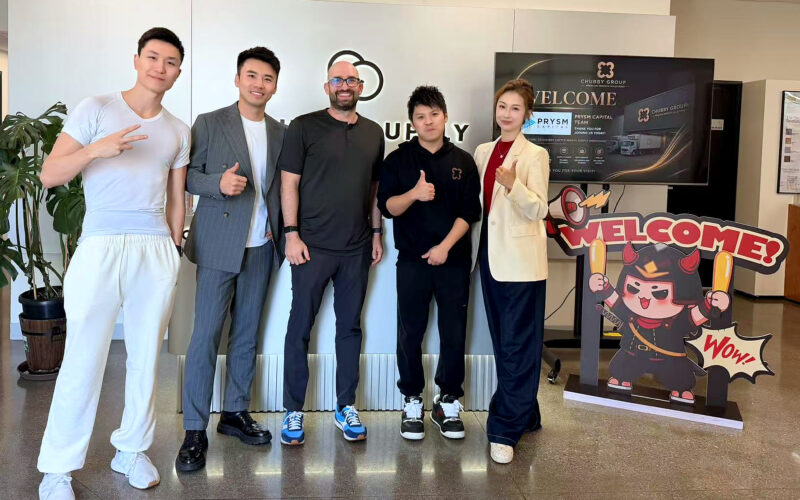
Chubby Group, the Los Angeles-based restaurant operator behind Chubby Cattle, Wagyu House, The X Pot and NIKU X, announced on October 15, 2026, that it had completed a $50 million Series A financing led by Prysm Capital at a $500 million valuation while advancing a proposed acquisition of 47 GEN Korean BBQ restaurants and four development sites. The restaurant transaction, valued at up to $100 million, involves GEN Restaurant Group, Inc. (NASDAQ: GENK), which signed a binding letter of intent with Chubby Group after receiving unanimous board approval on October 14. Chubby plans to transfer the restaurants into its operating network over 12 months, bringing additional locations into its vertically integrated sourcing, restaurant development and customer loyalty operations. GEN Restaurant Group intends to retain ownership of its brand and consumer packaged goods business while reducing restaurant lease obligations and receiving a convertible term note as part of the transaction. The proposed combination could reshape two Asian dining businesses, although the acquisitions remain subject to definitive agreements, regulatory approvals and operational transfers, while the financial value ultimately realized by GEN will depend on the final consideration and payment arrangements.
How does Chubby Group’s $50 million Series A financing support its restaurant expansion strategy?
The Series A represents Chubby Group’s first institutional financing round and introduces Prysm Capital as a financial partner during a period of rapid restaurant portfolio expansion. The company previously relied on operating cash flow and funding from its founders, local operating partners, supply chain partners and family offices. According to management, more than $90 million had already been invested across its restaurants and supply chain before the latest financing. The new capital increases financial flexibility as Chubby prepares to integrate additional restaurants, expand procurement capabilities and develop new locations.
Chubby Group has disclosed a $500 million valuation associated with the financing, but its announcement does not explicitly establish whether that figure represents a pre-money or post-money equity valuation. If the figure were post-money and the entire $50 million were invested as ordinary equity on equivalent economic terms, the financing would imply approximately 10% ownership for the new investors. That is only an illustrative calculation, not a disclosed ownership percentage, because the company has not published the share structure or financing terms. The valuation should also not be confused with the $100 million consideration contemplated for GEN’s restaurant operations.
Prysm Capital’s involvement is commercially relevant because Chubby is pursuing growth across several restaurant formats rather than operating a single concept. The company’s portfolio includes premium dining, Korean barbecue, hot pot and fast-casual businesses, with more than 70 operating locations across over 25 brands. Chubby also plans to develop 30 new Mr. Chubby and Chubby Bowls restaurants during 2027, creating additional demands on construction, staffing, supply chain and corporate infrastructure. The Series A funding is intended to support those activities, although the company has not disclosed a detailed allocation between acquisitions, new openings and supply chain development.
Matt Roberts, co-founder and partner at Prysm Capital, identified Chubby’s combination of restaurant operations, sourcing, design and loyalty infrastructure as central to the investment rationale. The investor also described Chubby as having expanded from 20 to approximately 70 locations while remaining profitable. However, the announcement does not provide audited financial statements, net profit figures or operating margins. The profitability claim therefore offers useful management context without establishing the level or sustainability of earnings.
What does the $100 million GEN Korean BBQ transaction actually include, and when could it close?
The proposed acquisition covers operations at 47 GEN Korean BBQ restaurants across the United States, together with four development sites. The companies have signed a binding letter of intent, with GEN Restaurant Group’s board approving the arrangement unanimously. They are targeting the completion of definitive transaction documentation within approximately 30 days of the October 14 announcement. However, closing remains subject to outstanding conditions, including restaurant license transfers, lease assignments, regulatory approvals and final agreements.
The transfer of restaurant operations is expected to proceed in four phases over 12 months rather than through a single immediate handover. Chubby Group is targeting the first 12 locations for November 1, 2026, subject to the necessary arrangements being completed. The company plans to finance restaurant conversions and associated construction work using its own capital. GEN Restaurant Group will retain operating profits from individual locations until those restaurants are transferred, creating a staged financial transition.
The headline transaction value of up to $100 million implies approximately $2.13 million per restaurant if divided equally among the 47 locations. However, this is only a simplified calculation, not a disclosed purchase price for each restaurant. The agreement also covers development sites, operating rights, future payments and other contractual obligations that may affect how consideration is allocated. Individual restaurant values could differ substantially depending on sales, profitability, location and lease commitments.
GEN Restaurant Group’s disclosures indicate that consideration involves a term note receivable, introducing an important difference between the announced transaction value and cash immediately available to the seller. The precise allocation of consideration, payment schedule and final contractual protections have not been fully disclosed. The ultimate economic value could also be affected by conditions attached to individual restaurant transfers. The transaction therefore remains a proposed financial and operational restructuring rather than a completed $100 million cash acquisition.
The relationship between the companies predates the latest announcement. Earlier in 2026, GEN Restaurant Group transferred four underperforming restaurants into an existing joint venture with Chubby Cattle, retaining a 49% interest while Chubby held 51%. That collaboration provided practical experience working with selected GEN locations before the larger transaction was proposed. It also means the latest acquisition should not be treated as the beginning of an entirely new commercial relationship.
Why does the $1.5 billion equity conversion valuation differ from Chubby Group’s new $500 million valuation?
One of the most consequential financial features involves GEN Restaurant Group’s proposed ability to convert an unpaid balance of its term note into Chubby Group equity at a $1.5 billion valuation. The conversion would be optional under the announced structure and would become relevant only to the extent that an unpaid balance remains eligible for conversion. This creates potential exposure to Chubby’s future equity value rather than requiring GEN to rely exclusively on scheduled note repayments. The terms also introduce uncertainty because the final value of such a conversion depends on the contractual provisions and Chubby’s future financial position.
The $1.5 billion conversion valuation is three times the $500 million valuation announced alongside Prysm Capital’s investment. However, the comparison does not establish that Chubby’s equity has already appreciated threefold or that the convertible note will generate a gain for GEN shareholders. The two figures relate to different transactions and economic arrangements, and the announcement does not provide sufficient information to establish their precise valuation bases. A contractual conversion price can differ materially from the equity valuation established in a financing round.
For GEN Restaurant Group, receiving a note instead of immediate cash introduces repayment and counterparty considerations. The economic outcome depends on whether Chubby makes the required payments, whether any unpaid amount becomes convertible and what that equity might eventually be worth. GEN’s announcement also identifies guarantees and collateral supporting the payments as relevant considerations, although the detailed protections have not been published. Investors should therefore distinguish the announced transaction consideration from cash already received or independently established fair value.
The arrangements are also relevant to Chubby Group’s capital allocation. A transaction involving deferred consideration may provide more flexibility than one requiring the entire price to be funded at closing, potentially preserving capital for restaurant conversions and expansion. However, deferred payment obligations remain financial commitments even when they do not immediately consume cash. The company’s ability to meet those obligations will depend on operating cash generation, financing capacity and the performance of the enlarged restaurant network.
How could Chubby Group’s supply chain and Chubby Club membership improve the economics of 47 acquired restaurants?
Chubby Group’s operating model relies on greater control over food procurement, restaurant design, construction and customer engagement. Rather than depending exclusively on suppliers delivering individual prepared meat cuts, the company says it purchases whole cattle and chickens and operates direct seafood sourcing arrangements. Ingredients can then be distributed across multiple restaurant formats, allowing different cuts and products to be matched with different menus. Management believes this approach supports food quality and purchasing efficiency as the number of restaurants increases.
The model could become more valuable as Chubby adds locations with significant recurring demand for meat and other ingredients. A larger restaurant network may support greater procurement volumes, more predictable supply requirements and improved utilization of distribution infrastructure. However, realizing those benefits requires efficient logistics, consistent food safety practices and sufficiently high restaurant sales to absorb central operating costs. Greater vertical integration can improve control while simultaneously increasing the complexity of procurement and inventory management.
Chubby plans to relaunch acquired restaurants either as GEN X, a wagyu-focused evolution of the existing Korean barbecue format, or as other Chubby Club restaurant concepts. The company intends to preserve elements of the dining experience familiar to GEN customers while introducing its own ingredient sourcing, interiors and customer benefits. That approach could allow it to capture existing demand without undertaking the customer acquisition effort associated with building entirely new restaurants. Nevertheless, a successful conversion depends on whether existing diners respond positively to the revised menu, pricing and restaurant identity.
Chubby has reported that previous transformations of GEN locations produced revenue increases of up to six times at individual units. The figure is a company-reported maximum outcome, not an average improvement across all converted restaurants. The announcement does not identify the underlying locations, periods, starting revenue figures or investment required to achieve those results. Extrapolating the same increase across 47 restaurants would therefore be unsupported.
Customer retention is another part of the strategy. Chubby says its Chubby Club membership programme has approximately 450,000 members, with benefits spanning participating restaurant concepts and delivery channels. The company can potentially use that customer relationship to promote newly acquired locations and encourage repeat visits across its portfolio. However, the disclosure does not identify active monthly members, average spending, retention rates or the financial contribution of the loyalty programme.
Why is GEN Restaurant Group selling its restaurants to concentrate on packaged Korean food?
The proposed sale represents a major strategic change for GEN Restaurant Group, which developed its business around all-you-can-eat Korean barbecue restaurants. GEN now intends to retain ownership of the GEN brand while concentrating on consumer packaged foods, including ready-to-cook marinated meat products distributed through supermarkets and warehouse clubs. The company expects to retain approximately three restaurants for training, staffing and product development rather than continuing to operate a nationwide dining network. This would substantially reduce its direct exposure to restaurant-level staffing, occupancy and operating costs.
GEN’s latest reported financial results help explain the commercial rationale. Second-quarter 2026 revenue increased 1.2% year over year to $55.7 million, but comparable restaurant sales declined 9.3%. The company recorded a $5.2 million operating loss and a $4.6 million net loss, compared with losses of $1.9 million and $1.7 million, respectively, a year earlier. Restaurant-level adjusted EBITDA declined from approximately $9 million to $6.3 million, indicating pressure on operating profitability despite some sequential improvement.
The balance sheet also illustrates the financial implications of maintaining a large leased restaurant estate. GEN reported $5.9 million in cash and cash equivalents at June 30, alongside approximately $24 million of outstanding debt and a working capital deficit of $41.7 million. Its proposed transaction is expected to reduce approximately $160 million of restaurant lease liabilities over the transition, subject to the final transfer arrangements. Management also expects the transaction to support repayment of outstanding debt, although those outcomes have not yet been realized.
Any lease liability reduction must be evaluated alongside the accounting treatment of the transferred restaurant operations and associated right-of-use assets. Removing a lease obligation does not automatically increase shareholder equity by the same amount because both sides of the balance sheet may change. Additionally, the timing of lease releases will depend on landlords, contract assignments and the final transfer structure. More definitive financial disclosures will be necessary to quantify the net balance-sheet effect.
GEN’s packaged foods business offers a different growth model that does not require the company to construct a restaurant for every new customer market. During the second quarter, the business reported a 341% sequential increase in consumer packaged goods revenue, with June sales exceeding $2 million. The company had secured access to nearly 2,000 supermarket and warehouse club locations, including commitments from more than 100 Costco warehouses. Distribution agreements with United Natural Foods and C&S Wholesale Grocers also provided a framework for broader market access.
Management estimated a forward 12-month packaged foods revenue run rate of $35 million to $40 million based on retail placements and the sales pipeline available at the time. That figure remains a company estimate rather than contracted annual revenue or an independently validated forecast. Actual performance will depend on product sell-through, repeat purchasing, gross margins and the economics of wholesale distribution. The shift could create a less capital-intensive business, but packaged food operations still require inventory investment, marketing, manufacturing capacity and reliable retail relationships.
Can Chubby Group’s projected $400 million in 2026 sales support its larger restaurant ambitions?
Chubby Group reports that its systemwide restaurant revenue increased from approximately $1.5 million in 2016 to $233 million in 2025. Management is projecting $400 million in systemwide sales for 2026, equivalent to approximately 71.7% growth over the previous year if achieved. These figures suggest substantial expansion across its restaurant portfolio, but systemwide sales are not necessarily equivalent to consolidated corporate revenue. Revenue generated by partner-operated or otherwise differently structured restaurants may not all be recognized directly by Chubby Group.
The company expects to reach approximately 100 locations by the end of 2026, excluding any assumption that all 47 proposed GEN restaurant transfers will be completed immediately. The acquisition could subsequently enlarge its operating footprint considerably, depending on the pace of transfers, closures and conversions. Additional openings planned for 2027 would create further opportunities for revenue growth but also require substantial execution across real estate, staffing and supply chain operations. The company has not disclosed a comprehensive capital expenditure budget or projected return on investment for its expansion programme.
Industry demand provides a potentially supportive environment. Chubby Group cited Euromonitor International research indicating that Asian full-service and limited-service restaurant sales outside Asia-Pacific grew at an 11% compound annual rate between 2020 and 2025, compared with 7% for the overall restaurant industry. These historical figures suggest stronger category growth over that period, but they do not establish equivalent future growth across the United States or guarantee performance for individual concepts. Restaurant operators must still contend with consumer spending pressure, food inflation, labour costs and intense competition.
Chubby’s acquisition strategy could provide a faster route to market than developing entirely new restaurants, particularly when acquiring locations with established customer traffic and existing infrastructure. However, changing restaurant concepts may require substantial renovation expenditure, additional training and menu adjustments. The proposed transaction also introduces greater geographic and operational complexity. The company will need to demonstrate that its supply chain and management infrastructure can support a substantially larger network without weakening restaurant-level economics.
What does GEN Restaurant Group’s share-price reaction reveal about the proposed $100 million transaction?
GEN Restaurant Group shares closed at $1.69 on October 14, 2026, increasing 16.55% from the previous session’s $1.45 close. The stock traded as high as approximately $2.53 intraday before retreating sharply from that level, while trading volume exceeded 56 million shares. The unusual activity coincided with the announcement of the binding letter of intent, suggesting heightened market attention, although the price movement cannot be attributed exclusively to one factor. The substantial intraday reversal also demonstrates that a positive initial response did not translate into sustained trading near the session’s highest price.
The transaction introduces competing considerations for GEN shareholders. A completed transfer could materially reduce the company’s operating complexity and lease exposure while leaving it with the Korean packaged foods business and a financial claim against Chubby Group. At the same time, GEN would surrender much of its existing restaurant revenue base and become more dependent on the commercial performance of its packaged food products. The final financial outcome also depends on the enforceability, timing and realizable value of the transaction consideration.
Management has identified possible future uses of proceeds, including debt repayment, business reinvestment, dividends and share repurchases. These remain prospective capital allocation options rather than approved distributions or completed debt reductions. The financial flexibility available for those purposes will depend on how much cash GEN receives, when the note is repaid and what obligations remain after restaurant transfers. Shareholders will also need updated financial statements showing the continuing business separately from transferred restaurant operations.
The next milestones are unusually concrete. The companies are targeting definitive closing arrangements within approximately 30 days of October 14, followed by the first planned 12-location transfer around November 1 and subsequent phases over the following year. Successful execution would provide evidence that restaurant leases, operating responsibilities and related contractual arrangements can move to Chubby as intended. Any delay, reduction in consideration or difficulty transferring leases could materially alter the expected benefits.
For Chubby Group, the combined financing and acquisition proposal offers an opportunity to expand its restaurant portfolio while making greater use of its centralized sourcing and customer loyalty infrastructure. For GEN Restaurant Group, the proposed transaction provides a route towards becoming a packaged foods-focused company with less direct restaurant exposure. The central financial question is whether the announced consideration can be converted into realizable value while Chubby improves the acquired restaurants’ operating performance. The strongest evidence will come from completed transfers, disclosed payment terms, actual restaurant profitability and the performance of GEN’s retained packaged foods business.
What are the key takeaways from Chubby Group’s financing and proposed GEN Korean BBQ acquisition?
- Chubby Group announced a $50 million Series A financing led by Prysm Capital at a reported $500 million valuation.
- The company signed a binding letter of intent to acquire operations at 47 GEN Korean BBQ restaurants and four development sites in a transaction valued at up to $100 million.
- The proposed acquisition remains subject to definitive agreements, lease and license transfers, and regulatory approvals.
- Chubby intends to take over the restaurants in four phases over 12 months, initially targeting 12 locations around November 1, 2026.
- GEN Restaurant Group would retain ownership of the GEN brand and packaged foods business, with Chubby receiving a perpetual brand license.
- The transaction includes a term note that may be convertible into Chubby equity at a $1.5 billion valuation, subject to the contractual conditions.
- GEN expects the transaction to reduce substantial restaurant lease liabilities, although the final accounting and financial effects remain unresolved.
- Chubby reported $233 million in 2025 systemwide revenue and projects $400 million for 2026, while planning further restaurant openings.
- GEN’s packaged foods division reported strong sequential growth, providing the commercial rationale for its proposed strategic transformation.
- Completed transfers, note repayments, restaurant profitability and packaged foods revenue will determine whether the transaction creates lasting economic value.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.