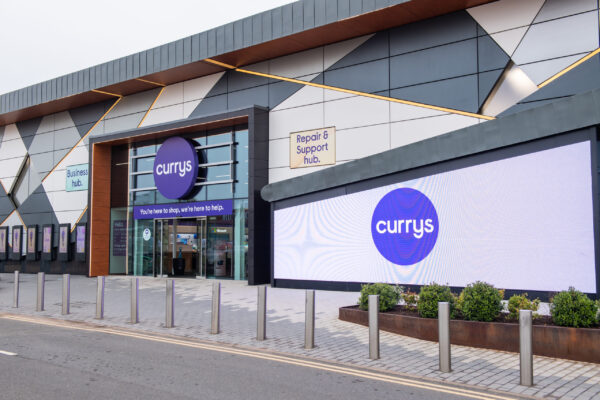


AO World plc (LSE: AO), a Bolton-based online electricals retailer selling major domestic appliances, mobile products and technology services across the United Kingdom, expects first-half group revenue to increase 5.5% and profit before tax to rise by more than 20% to approximately £21.5 million. The company also completed its acquisition of specialist photography retailer Jessops from Peter Jones CBE using existing cash resources, adding cameras and optical technology to a portfolio already expanded through musicMagpie. AO World expects more than £200 million of liquidity headroom at the half-year after paying a £10 million dividend and completing roughly half of its ongoing £10 million share-buyback programme.
The shares moved in the opposite direction to the headline profit trend, trading around 89.7p during September 24 compared with a 93p close the previous day, a decline of roughly 3.5%. That reaction appears to reflect caution around the unchanged full-year profit outlook and a tougher second-half comparison rather than a deterioration in H1 trading. AO World explicitly said planned ERP investment and a more challenging comparative environment mean the stronger first half will not automatically translate into higher full-year guidance.
Why has AO World profit grown much faster than revenue?
AO World expects revenue growth of roughly 5.5% but profit before tax growth above 20%, indicating meaningful operating leverage. Management credited continued operational improvements in Mobile and musicMagpie, while its broader efficiency programme has allowed a greater proportion of incremental sales to reach profit.
The company is also targeting a profit-before-tax margin above 5% as its next strategic milestone. Reaching that level would require a combination of higher sales density, better gross margins, disciplined fulfilment costs and greater contribution from ancillary services such as membership, protection products, recommerce and mobile.
The H1 profit run rate suggests progress, but the unchanged full-year outlook is important. Management is signalling that some of the first-half gain will be reinvested through its ERP programme and other strategic initiatives rather than flowing entirely into near-term earnings.
That approach can create greater long-term value if the investments improve customer data, inventory management and operating efficiency. Investors, however, are being asked to accept a slower immediate earnings payoff despite a strong H1.
What does Jessops add to AO World beyond another retail brand?
Jessops gives AO World an established position in specialist cameras and optical equipment, a category that sits adjacent to consumer electronics but requires product knowledge and a different customer base. AO World plans to use its larger traffic base, scale and operating infrastructure to expand the acquired business over the next 12 months.
The acquisition also includes Camera Jungle, Jessops’ recommerce operation. That business is strategically complementary to musicMagpie because both involve acquiring, assessing and reselling used consumer technology. Combining expertise in recommerce could potentially improve procurement, pricing, logistics and customer acquisition across categories.
The financial consideration was not disclosed in the trading statement, which limits investors’ ability to calculate the acquisition multiple or immediate return on invested capital. What is clear is that AO World funded the transaction from existing cash rather than new debt or equity, reducing financing risk.
Jessops therefore needs to be judged through future revenue, profit contribution and cash return rather than the strategic narrative alone. The opportunity is to use AO World’s digital distribution and scale to make a specialist retailer more productive than it could be as a standalone business.
Is AO World’s £200 million liquidity headroom being used aggressively enough?
The expected liquidity headroom is substantial, particularly after AO World paid a £10 million dividend and completed around £5 million of its current £10 million buyback. That demonstrates strong cash generation and gives management capacity to invest while continuing shareholder returns.
The company is clearly using part of that balance-sheet flexibility to broaden its addressable market. Jessops follows the acquisition and operational improvement of musicMagpie and supports a strategy of owning more categories that fit AO World’s infrastructure and membership proposition.
The risk is acquisition creep. Retailers can destroy value by buying businesses simply because capital is available, especially if the categories have weak margins or require operating capabilities far removed from the core. Jessops appears strategically adjacent, but investors need evidence that AO World can generate returns higher than simply returning more capital to shareholders.
Why did AO shares fall despite the positive H1 statement?
The market had already pushed AO World shares above 93p during September before the update, and the unchanged full-year profit guidance likely limited the upside from a strong first-half performance. The share price was around 89.7p during September 24 trading, down about 3.5% from the previous close.
That response is not necessarily inconsistent with the business performing well. Investors price future earnings, and management explicitly warned that H2 faces tougher comparatives and planned investment. A stronger-than-expected H1 without a change to the FY27 outcome can therefore result in profit-taking rather than another rerating.
The half-year results due on November 24 should provide more detail on margins, cash conversion and the contribution from Mobile and musicMagpie. Investors will also look for initial guidance on Jessops integration and whether the acquisition alters medium-term revenue ambitions.
For now, AO World is showing that its core model can generate earnings faster than sales, while the balance sheet supports acquisitions and shareholder returns simultaneously. The next valuation question is whether Jessops and other adjacent categories enhance that model or merely make the group larger.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.