AML3D Limited (ASX: AL3) reported FY26 revenue of A$12.5 million, an increase of 70%, as its United States defence strategy moved from technology validation toward a growing installed base of ARCEMY metal additive-manufacturing systems. The company achieved positive EBITDA of A$608,000 during the second half of FY26, its first profitable half-year, although the full financial year remained EBITDA-loss-making. ASX classified the August 31 results announcement as price-sensitive.
Forward contracted work provides an even stronger comparison with the historical revenue number. AML3D finished FY26 with A$16.8 million of work rolling into FY27, up from A$9 million a year earlier and equivalent to about 1.34 times the entire FY26 revenue base. The global sales pipeline stood at an estimated A$78 million at June 30.
AML3D’s unaffected closing reference is A$0.135 on August 28, when the shares gained 8%. The stock had already risen from A$0.09 on August 21 to A$0.135, a 50% gain over the following five sessions, including a 35% surge on August 25. Because the August 31 market session remained incomplete when the results were prepared, the Friday close is the appropriate reference rather than a partial Monday move.
How important is AML3D’s A$16.8 million FY27 order book relative to its current scale?
The A$16.8 million rollover is approximately A$4.3 million larger than AML3D’s total FY26 revenue. If every order were recognised during FY27, which should not automatically be assumed because delivery timing differs among contracts, the existing backlog alone would mathematically represent 34% more revenue than AML3D generated during the entire year just completed.
The company’s order book reached an intra-year peak of A$29 million during FY26, comprising A$20 million of new orders plus A$9 million carried forward. That demonstrates both the scale of contract wins and the fact that order values convert into revenue across multiple reporting periods rather than immediately.
The sales pipeline is larger again. A$78 million represents more than six times FY26 revenue, although pipeline opportunities carry a fundamentally different level of certainty from contracted work. Conversion rates, procurement timelines and customer qualification can all change, especially in defence programs where technical standards and budget approvals often lengthen sales cycles.
Why is the United States Navy becoming central to AML3D’s financial model?
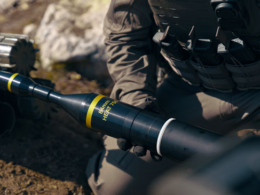
AML3D has deployed or secured contracts for 14 ARCEMY systems within the United States Navy’s Maritime Industrial Base supply chain from a standing start in 2023, while another two systems have been ordered for high-value American industrial manufacturing. The technology uses AML3D’s patented Wire Additive Manufacturing process, combining robotic welding, software and materials engineering to produce large metal components.
The model is designed to address a strategic supply-chain problem. Naval construction and maintenance programs require specialised metal parts traditionally manufactured through forging, casting and machining, often with long lead times. Additive manufacturing can produce selected components closer to the point of need and potentially reduce dependence on constrained traditional manufacturing capacity.
AML3D also secured a A$2.6 million contract for replacement components used on United States Navy submarines, expanded into the Tennessee Valley Authority and FasTech, and progressed a feasibility program involving BAE Systems in the United Kingdom. Defence relationships now extend across Australia, the United States and United Kingdom, the three AUKUS countries.
That diversification matters because the company’s valuation thesis becomes more robust if ARCEMY moves from one procurement channel into multiple defence, aerospace, energy and industrial customers. Conversely, heavy reliance on United States Navy-linked spending would leave AML3D exposed to program timing and government procurement cycles.
Can AML3D fund its A$17 million capacity expansion without another equity financing?
AML3D ended June with approximately A$26.7 million of cash and plans around A$17 million of new investment, including A$12 million to double United States manufacturing capacity and A$5 million for a United Kingdom or European Technology Centre. The planned expansion equals about 64% of the year-end cash balance, leaving a simple residual of nearly A$10 million before considering operating cash flows, customer receipts and other capital commitments.
The company also has a A$2.24 million Australian next-generation manufacturing technology program under way. Because not all investment necessarily occurs upfront or from the June cash balance alone, subtracting the capital programs from cash is not a forecast of AML3D’s eventual liquidity. It does, however, show that the balance sheet is substantially better placed to support global growth than when the company depended more heavily on periodic equity injections.
The strategic question is whether capacity investment precedes demand by the right amount. Doubling United States manufacturing capacity makes sense if defence orders continue converting, but underutilised facilities can depress returns if the A$78 million pipeline converts more slowly than management expects.
Why did AL3 rally before the FY26 results were released?
AML3D shares had already advanced 50% between August 21 and August 28. The strongest move came on August 25, when the stock jumped 35%, followed by volatile trading that left it at A$0.135 before the FY26 announcement.
Investors had received several operational developments before the annual numbers, meaning the market already had evidence of accelerating defence adoption. The FY26 result nevertheless provides a more useful financial confirmation because it shows that the order momentum is translating into reported revenue and that the second half crossed into positive EBITDA.
The distinction between half-year and full-year profitability remains important. AML3D has not yet demonstrated sustained annual profit, and the next phase includes significant investment to expand manufacturing capacity internationally. FY27 therefore becomes the period in which contracted orders need to generate enough gross profit and cash to show that scale can improve economics rather than merely top-line growth.
With existing orders already greater than FY26 revenue, AML3D enters the year with materially stronger visibility than before. The most useful measure of progress will now be how much of that A$16.8 million converts on schedule and whether the A$78 million pipeline produces repeat orders without requiring another major increase in the cost base.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.