

Hamburg-based energy technology company 1KOMMA5° has secured €70 million from existing and new investors in a financing round that values the business at $1.35 billion, giving the clean-energy unicorn additional capital as it pushes deeper into software-driven household energy management.
The October 12 financing brings Japanese cleantech investor Marunouchi Innovation Partners into the shareholder base. The strategic significance extends beyond the €70 million itself because 1KOMMA5° is considering an expansion into the United States, while management sees the Japanese investor’s experience in U.S. energy investments as potentially useful if that plan advances.
The company is simultaneously preparing to invest more than €100 million in its Heartbeat AI business during 2027. That planned investment should not be confused with the latest financing amount. The €70 million represents the newly disclosed funding round, while the larger Heartbeat AI figure describes planned spending on the energy-management platform next year.
Why has 1KOMMA5° secured another €70m instead of moving directly toward an IPO?
1KOMMA5° has been building toward the public markets for several years, but management has not committed to an immediate listing. The company previously postponed U.S. IPO ambitions amid uncertainty around American renewable-energy and trade policies, demonstrating how quickly the economics of an international clean-energy listing can change when regulation and capital markets move in different directions.
Chief executive and co-founder Philipp Schröder has now indicated that the company is again considering entry into the United States. Performance during 2027 is expected to influence when, or whether, management ultimately proceeds with a U.S. initial public offering.
That distinction is important. 1KOMMA5° is not currently announcing an IPO, filing a prospectus or providing a listing timetable. The financing instead gives the company additional flexibility to develop Heartbeat AI, continue expanding its operating business and potentially establish a stronger U.S. presence before making a public-market decision.
For investors, that can be strategically valuable. A business approaching an IPO from a position of stronger revenue, profitability and software adoption may command a different valuation from one entering public markets primarily because it needs access to capital.

What does the $1.35bn valuation say about investor expectations?
The latest transaction values 1KOMMA5° at $1.35 billion, keeping the company firmly above the $1 billion threshold it first crossed in 2023. The valuation increase comes at a time when investors have become more selective toward capital-intensive clean-energy businesses, making the company’s combination of hardware revenue, energy software and operating profitability central to the investment case.
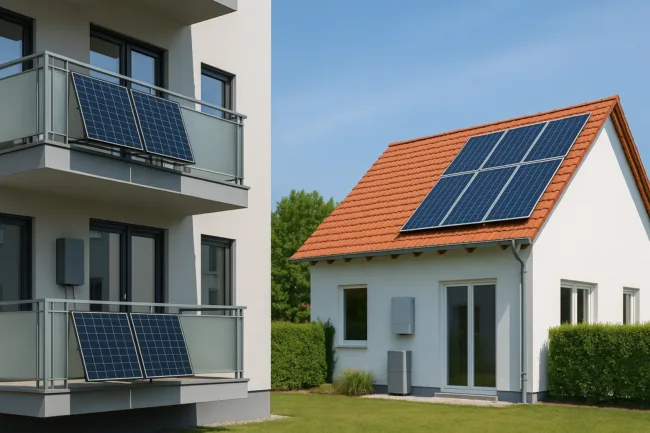
1KOMMA5° differs from a pure software startup because a significant part of its business comes from installing and selling physical energy systems. Its offering spans photovoltaic systems, batteries, heat pumps, air conditioning systems and electric-vehicle charging infrastructure, with Heartbeat AI intended to connect and optimize those assets.
That model creates both advantages and complexity. Hardware installations can generate substantial revenue and give the company an installed base through which software can be distributed, but physical operations also tend to involve lower margins, working-capital requirements and greater execution complexity than pure subscription software.
The valuation therefore increasingly depends on whether Heartbeat AI can improve the quality of the revenue mix over time. If software and energy-market services become a larger contributor to earnings, 1KOMMA5° could begin to resemble a technology-enabled energy platform rather than primarily an installer with proprietary software.
How quickly is 1KOMMA5° growing ahead of the new investment?
The company said in September that organic revenue increased 30% year over year during the first nine months of 2026. Management maintained its full-year target of approximately $750 million, equivalent to roughly €700 million under the exchange-rate assumptions it used at the time, and expected full-year growth of between 35% and 40%.
The hardware business was also expected to generate approximately €40 million of EBITDA during 2026. That figure is management guidance rather than a completed full-year result, but it is important because profitability provides a different backdrop for the latest financing than would a business relying entirely on external capital to sustain operations.
1KOMMA5° also said its global order intake reached €100 million during August. Its Heartbeat AI division reached an annualized revenue run rate of around €30 million during the same month, which the company described as almost double the year-earlier level.
Annualized run rate should not be treated as actual annual revenue. It indicates the revenue pace implied by a particular period if sustained, meaning future results could be higher or lower depending on customer additions, cancellations, pricing, usage and energy-market conditions.
Why is Heartbeat AI becoming central to the 1KOMMA5° investment story?
Heartbeat AI is designed to coordinate distributed household energy assets including solar panels, batteries, heat pumps, air conditioning systems and electric-vehicle chargers. The software can determine when electricity should be consumed, stored or supplied to the market based on variables including electricity prices and available generation.
That creates a broader business opportunity than simply selling household equipment. As increasing numbers of homes produce electricity themselves while also operating flexible loads such as batteries, electric vehicles and heat pumps, the value of coordinating those assets can rise alongside the amount of renewable generation on the grid.
1KOMMA5° said earlier this year that Heartbeat AI had aggregated more than 1 gigawatt of controllable flexibility capacity. That figure refers to flexible capacity connected through the virtual power plant and should not be interpreted as 1 gigawatt of electricity generation owned by 1KOMMA5°.
The distinction is commercially important. The company does not need to own all the underlying physical assets to potentially extract value from coordinating them. If Heartbeat AI can manage a growing network of customer-owned equipment, software and energy-market activities could scale differently from the installation business that initially built the customer base.
Can Heartbeat AI become a meaningful software business rather than an add-on to hardware?
This is arguably the most important question embedded in the $1.35 billion valuation. 1KOMMA5° said in September that it was spending more than €35 million annually on research and development within the software and AI division, financed from operating cash flow.
Management now intends to invest more than €100 million in Heartbeat AI during 2027. The company has not indicated that the entire amount will come directly from the new €70 million financing, so the two figures should be treated separately.
The scale of the planned spending suggests management wants Heartbeat AI to become more than a feature designed to improve hardware sales. The company is opening the platform to existing systems and equipment supplied by third parties, potentially expanding the addressable market beyond customers that originally purchased their energy equipment from 1KOMMA5°.
That approach could be decisive. A closed ecosystem would largely tie software growth to the company’s ability to sell and install new hardware. An interoperable platform capable of controlling millions of existing systems could create a substantially larger software and energy-services opportunity.
How large could the 1KOMMA5° virtual power plant become?
The company said Heartbeat AI had surpassed 1 gigawatt of controllable flexibility capacity by May 2026, approximately double the level reported a year earlier. Management has set a target of reaching 20 gigawatts by 2030.
That 20-gigawatt figure remains a company target, not current operating capacity. Reaching it would require substantial expansion in connected systems, customer adoption, compatible hardware and access to electricity markets across multiple jurisdictions.
The economics would also depend on more than installed capacity. A virtual power plant creates value through the ability to shift consumption, storage and electricity flows at economically useful times. Revenue opportunities can therefore be influenced by market volatility, tariff structures, grid rules, smart-meter availability and the commercial terms under which customers share in the value created.
Nevertheless, the expansion from 500 megawatts reported in 2025 to more than 1 gigawatt in 2026 provides evidence that the network is scaling. Whether the company can maintain anything close to that pace as the base becomes larger will be one of the important operating metrics to watch.
Why does the new Japanese investor matter for a possible US expansion?
Marunouchi Innovation Partners is particularly relevant because 1KOMMA5° is reassessing the United States after previously shelving IPO ambitions there. Management has indicated that the investor’s familiarity with energy investments in the U.S. market could provide useful experience as the company evaluates entry.
A U.S. launch would give 1KOMMA5° exposure to one of the world’s largest markets for residential energy equipment, but it would also expose the company to a significantly different policy, utility and competitive landscape. Solar economics, electricity tariffs, incentives, permitting requirements and grid structures vary substantially across states.
That means success in Germany cannot simply be extrapolated into the United States. The company would need to determine where the combination of household electricity prices, solar penetration, batteries, electric vehicles and regulatory flexibility creates the strongest commercial opportunity for Heartbeat AI.
Investor interest appears to be encouraging management to examine that possibility again, but the company has not yet committed to a U.S. market launch. Any resulting expansion should therefore remain framed as a strategic option rather than an established operating plan.
Could the latest financing make a future 1KOMMA5° IPO more attractive?
The financing provides additional runway, but the more important development may be the operating progress occurring alongside it. A company capable of approaching the public markets with organic revenue growth, profitable hardware operations and a rapidly expanding software business would present a more balanced investment case than a conventional clean-energy growth company dependent on continuous capital injections.
Management’s approximately $750 million revenue target for 2026 provides a substantial revenue base relative to the $1.35 billion private-market valuation. Direct valuation multiples based on that figure should still be used cautiously because the target remains management guidance and because revenue from equipment installation carries very different economics from software revenue.
That mix will likely matter enormously in any eventual IPO. Public investors could assign a higher multiple to recurring software and energy-management earnings than to installation revenue, particularly if Heartbeat AI demonstrates attractive margins and durable customer retention.
The key valuation question is therefore not simply how quickly total revenue grows. It is whether an increasing portion of 1KOMMA5°’s economic value comes from software, virtual-power-plant services and automated energy trading rather than from selling and installing physical equipment.
What are the biggest risks behind 1KOMMA5°’s expansion strategy?
Regulation remains one of the most important variables. Household energy economics depend heavily on electricity pricing, grid rules, renewable-energy incentives and mechanisms governing how consumers are compensated for electricity supplied to the system.
1KOMMA5° believes changes to Germany’s feed-in framework could increase demand for intelligent energy management because customers would have stronger incentives to optimize when electricity is consumed or sold. That represents management’s strategic interpretation of the regulatory change rather than a guaranteed outcome.
Execution risk is also substantial. The company operates across seven markets and employs around 3,000 people, while simultaneously managing physical installations, financing programmes, software development, energy-market activities and possible geographic expansion.
A move into the United States would add another layer of complexity. It could materially expand 1KOMMA5°’s addressable market, but it could also increase spending before the company establishes sufficient customer density to generate attractive returns.
Is 1KOMMA5° becoming an AI company or still primarily an energy business?
The answer may increasingly be both. The company’s revenue base remains heavily connected to physical electrification products, but Heartbeat AI is becoming the layer intended to link those products into a coordinated energy platform.
That distinction explains why the latest €70 million financing is more strategically interesting than the headline funding number alone. Investors are backing a company that already has hundreds of millions of euros of targeted annual revenue while simultaneously attempting to create a higher-value software business from the installed infrastructure beneath it.
The $1.35 billion valuation therefore represents a bet on execution across two business models. 1KOMMA5° must continue making its hardware and installation operations profitable while demonstrating that Heartbeat AI can scale into an increasingly independent source of recurring revenue and energy-market value.
If that transition succeeds, the company could approach a future IPO with a materially different profile from the clean-energy installer it began as in 2021. If software adoption disappoints, investors may instead value the business primarily on the economics of its hardware operations.
The next year should make that distinction clearer. With more than €100 million of Heartbeat AI investment planned for 2027, a possible U.S. entry under consideration and management explicitly linking future IPO timing to performance, 1KOMMA5° is entering a period in which its software ambitions will increasingly have to show up in measurable financial results.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.