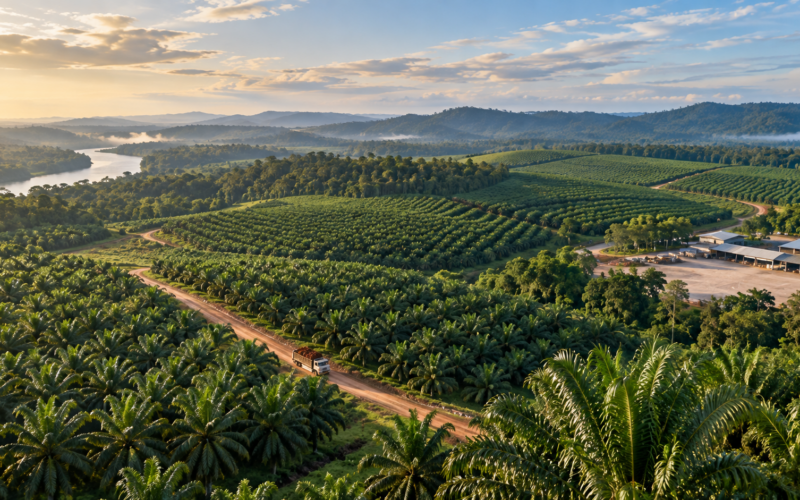
M. P. Evans Group PLC (AIM: MPE) has created a potential expansion path of more than 3,000 planted hectares at its Kota Bangun operation in East Kalimantan, giving investors a much larger development story than the headline US$2 million acquisition price initially suggests. The sustainable palm-oil producer acquired PT Kalimantan Wahana Berjaya, which controls 776 planted hectares and up to 450 hectares of additional plantable land, while separately securing initial rights over the adjacent 3,600-hectare Long Nah parcel. Surveys indicate roughly 2,000 hectares of Long Nah could be developed for oil palm.
The market reacted positively. M. P. Evans shares were quoted around 1,890p on September 10, up 5.82%, while trading on September 11 included transactions around 1,900p. That price action is important because the announcement arrived only days before the company’s scheduled September 14 interim results, meaning investors were simultaneously assessing new growth expenditure and the financial capacity available to fund it.
Why is a US$2 million acquisition potentially much more important for M. P. Evans?
The US$2 million purchase price applies to PT Kalimantan Wahana Berjaya rather than the entire future development programme. M. P. Evans estimates that rehabilitating, planting and bringing both the acquired area and Long Nah into maturity could require total investment of US$20 million to US$25 million over time. The company expects that programme to lift the planted area at Kota Bangun by more than 3,000 hectares.
That means the real investor question is not whether US$2 million is material to a company approaching a £1 billion equity valuation. It plainly is not. The significance is that a relatively modest upfront purchase has created access to a larger contiguous expansion opportunity that can be developed within an existing operating region.
M. P. Evans estimated development costs of approximately US$7,000 to US$8,000 per planted hectare. That provides investors with an unusually useful capital-intensity benchmark because future production can eventually be compared with the cost of bringing those hectares into operation. The economics will ultimately depend on yields, crude palm-oil pricing, replanting requirements and the speed with which the new hectares mature.
Can M. P. Evans fund the Kota Bangun expansion without weakening shareholder returns?
The group enters the expansion from a comparatively strong financial position. M. P. Evans reported 2025 revenue of US$371 million, gross profit of US$142.2 million, operating cash generation of US$161.5 million and a year-end net cash surplus of US$87.5 million. Earnings per share reached 161.3p and the normal dividend increased to 60p per share.
Those figures put the projected US$20 million to US$25 million expansion commitment into perspective. Even though development expenditure will be spread over time and cash generation can change with commodity prices, the planned capital requirement represents a manageable fraction of recent annual operating cash flow. That is important because plantation growth becomes less attractive if it forces a company to interrupt dividends, issue equity or take on excessive borrowing.
M. P. Evans has also been buying back shares during 2026, indicating that management has been balancing organic investment, acquisitions and shareholder distributions rather than directing all available cash toward expansion. The September acquisition therefore appears less like a balance-sheet stretch and more like an attempt to deploy capital into additional producing acreage while the group retains financial flexibility.
How much could the additional planted area change M. P. Evans’ production base?
M. P. Evans ended 2025 with planted hectarage under management exceeding 70,000 hectares. Adding more than 3,000 hectares at Kota Bangun would therefore represent a meaningful, though not transformational, expansion of the group’s planted footprint.
The value emerges gradually because newly planted palms take time to mature, while some of the 776 existing hectares require rehabilitation or replanting. This is consequently not an acquisition investors should treat as an immediate earnings step-change. It is better viewed as a multi-year extension of the production pipeline that can help offset ageing acreage elsewhere and support future crop growth.
The location may also matter operationally. Expansion around an existing project can potentially allow infrastructure, management, logistics and processing assets to be shared more efficiently than would be possible with an entirely new geographically isolated estate. The company has not quantified those potential synergies in the announcement, so investors should avoid assuming savings that have not been disclosed.
Why did M. P. Evans shares respond so strongly to the Kota Bangun announcement?
The approximately 5.8% September 10 share-price rise looks large relative to a US$2 million transaction, suggesting investors may have focused on the strategic acreage rather than the acquisition price alone. The announcement effectively added a visible development runway to a company already generating substantial cash, while limiting the immediate balance-sheet burden.
Timing probably also contributed to the reaction. M. P. Evans is due to release first-half results on September 14, meaning shareholders will soon receive updated production, pricing, profitability and cash data with which to assess the acquisition.
The next catalyst is therefore unusually close. If interim cash generation remains strong, investors may view the Kota Bangun development programme as comfortably fundable alongside dividends and buybacks. If margins or cash conversion weaken materially, however, a US$20 million to US$25 million development commitment may receive more scrutiny. The acquisition gives M. P. Evans additional growth optionality; the coming results will help determine how cheaply that optionality can be financed.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.