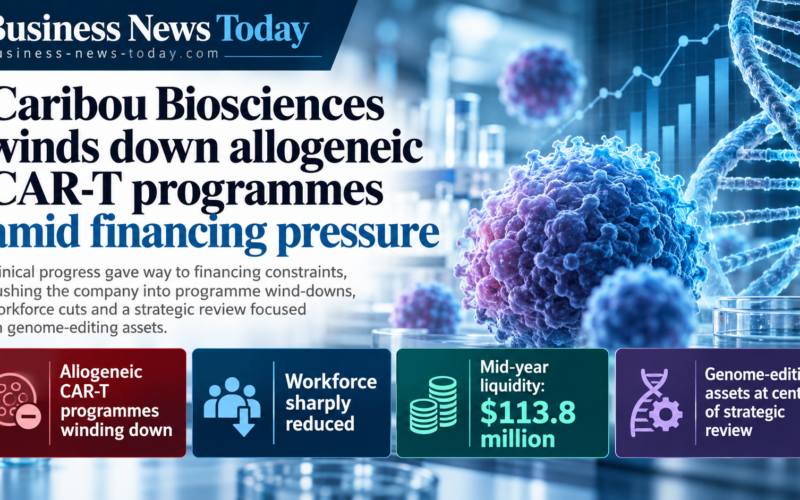
Caribou Biosciences, Inc. (Nasdaq: CRBU), the Berkeley-based CRISPR genome-editing biotechnology company, is discontinuing clinical development of vispa-cel and CB-011 while pursuing a merger, acquisition or other strategic transaction. The board approved a substantial workforce reduction that will leave only a limited number of employees to execute a potential transaction and wind down operations, with most affected staff expected to depart during the fourth quarter of 2026. A California WARN filing separately identifies 87 jobs at Caribou Biosciences’ Berkeley location as affected by a permanent closure effective December 7. The decision is particularly consequential because Caribou Biosciences had $113.8 million of cash, cash equivalents and marketable securities at June 30 and said vispa-cel was ready to move toward a pivotal trial after alignment with the U.S. Food and Drug Administration on phase 3 design.
Caribou Biosciences expects approximately $15 million to $19 million of restructuring expenses. Roughly $10 million to $11 million is expected to cover severance, continued healthcare and related employment costs, while another $5 million to $8 million is associated with winding down the ANTLER and CaMMouflage clinical trials. Additional costs could still arise from leases, contract terminations, intellectual-property agreements and potential impairments.
The company has engaged Wedbush Securities to explore strategic alternatives but has not established a timetable or guaranteed that a transaction will occur. That leaves shareholders facing a familiar late-stage biotechnology equation in which cash, intellectual property and clinical data can become worth more than the operating business that generated them. The unusually difficult part is that Caribou Biosciences is not abandoning an obviously failed clinical programme but withdrawing because management concluded that the financing required to advance allogeneic CAR-T had become too difficult to secure responsibly.
Why is Caribou Biosciences ending development when vispa-cel was ready for a pivotal trial?
Vispa-cel had advanced sufficiently for Caribou Biosciences to reach regulatory alignment on the design of a phase 3 study in relapsed or refractory B-cell non-Hodgkin lymphoma. Moving into a pivotal programme, however, would require substantially more capital for clinical sites, manufacturing, regulatory work and organisational support before any potential commercial revenue could emerge. Biotechnology financing conditions can therefore become a decisive development constraint even when clinical progress remains scientifically encouraging.
The problem is particularly acute for allogeneic CAR-T because the category requires investors to fund not only clinical development but a manufacturing model intended to produce off-the-shelf cellular medicines at reliable commercial scale. Public biotechnology valuations have made repeated equity financing more dilutive, while investors increasingly favour programmes with shorter timelines to decisive clinical or regulatory events. Caribou Biosciences concluded that the financing environment no longer supported responsible advancement of both programmes.
That changes the investment question from whether vispa-cel or CB-011 could work to whether another company values the underlying programmes enough to continue them. A strategic buyer with a stronger balance sheet, complementary manufacturing capabilities or an existing cell-therapy portfolio could evaluate the assets differently from a standalone small-cap biotech dependent on external capital markets.
How significant is the 87-job Berkeley closure relative to Caribou Biosciences’ workforce?
Caribou Biosciences reported 97 full-time employees as of February 27, 2026, with the majority located in Berkeley. The 87 positions subsequently identified in the California WARN record therefore illustrate the scale of the latest contraction, although the February workforce figure should not be treated as an exact October headcount denominator because hiring and departures could have occurred in the intervening months. The SEC filing confirms that only a limited number of employees are expected to remain once the phased workforce reduction is substantially complete.
This is also not Caribou Biosciences’ first employment reset. The company had already implemented workforce reductions in July 2024 and April 2025 as biotechnology financing tightened and management concentrated spending on priority clinical programmes. The October decision goes much further because development of the company’s two remaining allogeneic CAR-T programmes is now being discontinued rather than merely prioritised.
For employees, the transition effectively changes Caribou Biosciences from a clinical development organisation into a transaction and wind-down organisation. Scientific, clinical and operational capabilities that were built to move programmes through development become less necessary once management’s central task shifts toward preserving cash, closing trials and finding value for remaining assets.
What does Caribou Biosciences’ $113.8 million cash position mean for strategic alternatives?
Cash becomes strategically important because Caribou Biosciences is reducing future development spending before its balance sheet is exhausted. That gives the board more negotiating flexibility than a biotechnology company forced to pursue a transaction with only a few months of liquidity remaining. It also means potential counterparties will evaluate both the company’s assets and the cash that could accompany a merger or other transaction.
The restructuring costs reduce that headline liquidity, while trial wind-down expenses, lease commitments and transaction costs will continue consuming cash. Caribou Biosciences has also warned that additional charges cannot yet be estimated reliably, so the eventual residual value available for a transaction will be lower than the June 30 cash figure. Preserving that residual cash pool is one reason rapid workforce reduction becomes economically rational once the board decides not to advance the pipeline itself.
There is no guarantee the strategic review results in a transaction that improves shareholder value. Biotechnology strategic reviews can end in reverse mergers, asset sales, licensing deals, liquidation or no transaction at all, and the relative value depends heavily on the quality of interested counterparties and how quickly cash burn is contained.
What does CRBU’s collapse say about how the market values the remaining Caribou assets?
Caribou Biosciences shares closed at approximately $0.46 on October 9 after falling sharply following the strategic-review announcement. The stock was down about 62% from its October 2 close and approximately 68% from September 9, leaving CRBU only slightly above its 52-week low of roughly $0.44 and far below the approximately $3.54 high. The market is therefore assigning substantial probability to value destruction during the wind-down or to a transaction that captures only a fraction of the company’s historical development value.
That reaction is notable because the June cash balance is large relative to the company’s depressed equity valuation. A cash balance above market capitalisation does not automatically create an arbitrage because restructuring costs, liabilities, operating burn and transaction expenses can consume much of the difference. Investors also cannot assume that clinical intellectual property has a readily realisable value simply because significant capital has already been invested in it.
The market’s response nevertheless underscores the severity of the financing problem. A programme can retain scientific potential while its equity value collapses if investors believe the cost and time required to reach commercialisation exceed what the standalone company can finance.
What does Caribou Biosciences’ retreat signal for the wider allogeneic CAR-T sector?
Autologous CAR-T products have demonstrated that engineered cell therapy can deliver major clinical benefits, but the manufacturing model remains personalised, expensive and operationally complicated. Allogeneic developers have sought to solve that problem using donor-derived cells capable of becoming more standardised off-the-shelf products. The commercial promise is large, but the development risk remains high because durability, immune rejection, safety and manufacturing consistency all need to compete against increasingly effective autologous therapies and other treatment modalities.
Caribou Biosciences’ decision suggests financing risk should now be treated alongside clinical risk when assessing the sector. A programme can reach a technically meaningful stage yet still fail to attract enough capital to fund the next clinical transition. That could encourage consolidation around better-capitalised companies capable of carrying several expensive cell-therapy programmes simultaneously.
The strategic review may therefore determine whether Caribou’s science disappears, changes ownership or becomes part of a larger platform. The workforce reduction is the immediate corporate event, but the deeper industry issue is whether promising allogeneic CAR-T assets can still obtain the capital required to cross the expensive gap between early clinical evidence and registrational development.
What are the key takeaways from Caribou Biosciences’ CAR-T shutdown and workforce reduction?
- Caribou Biosciences is discontinuing further development of both vispa-cel and CB-011 while evaluating strategic alternatives.
- Most affected employees are expected to leave during the fourth quarter, with only a limited team retained for transaction and wind-down work.
- A California WARN record lists 87 positions at Caribou’s Berkeley location in connection with a permanent closure effective December 7.
- Caribou had 97 full-time employees as of February 27, showing the exceptional scale of the latest restructuring.
- Restructuring expenses are currently estimated at $15 million to $19 million, before certain lease, contract and impairment costs.
- Vispa-cel had reached a pivotal-ready stage with regulatory alignment on a phase 3 study design.
- Caribou held $113.8 million of cash, cash equivalents and marketable securities at June 30, making preservation of residual cash central to strategic value.
- CRBU has lost more than 60% over roughly five trading sessions and is trading near its 52-week low.
- The retreat highlights financing risk as a potentially decisive constraint for capital-intensive allogeneic CAR-T developers.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.