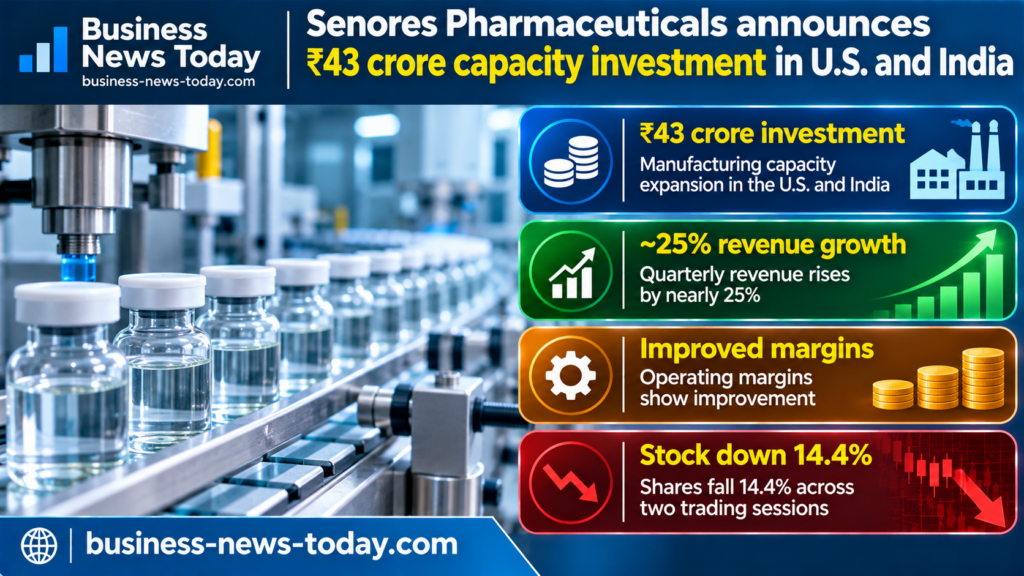
Senores Pharmaceuticals Limited (NSE: SENORES, BSE: 544319) has announced a ₹43 crore manufacturing expansion programme across three subsidiaries in the United States and India, targeting completion by March 2027. The Ahmedabad-based pharmaceutical manufacturer plans to increase combined annual production capacity at its Havix Group Inc. and Apnar Pharma Private Limited facilities from 1.7 billion units to 3.2 billion units, alongside a separate prefilled-syringe manufacturing line. The announcement on 29 October 2026 accompanied second-quarter FY27 results showing consolidated revenue growth of 24.9% and EBITDA growth of approximately 38%, supported by stronger regulated-market sales and improved operating margins. However, Senores shares declined approximately 14.4% across the 29 and 30 October trading sessions, despite the company’s reported earnings growth and additional manufacturing commitments. The divergence places renewed attention on whether product commercialisation, capacity utilisation and operating cash generation can sustain the company’s expansion strategy.
The capacity programme comes as Senores increases its presence in regulated pharmaceutical markets, particularly the United States, while expanding manufacturing capabilities in Gujarat. The existing facilities covered by the latest announcement have disclosed utilisation of approximately 50% to 70%, meaning their proposed expansion is not simply a response to fully exhausted manufacturing capacity. Senores is instead positioning itself for anticipated demand from an expanding portfolio of approved products, customer manufacturing relationships and new distribution channels, with the financial returns depending on how effectively those opportunities become commercial sales.
How will Senores Pharmaceuticals’ ₹43 crore investment expand manufacturing capacity in the United States and India?
The largest manufacturing capacity addition in absolute terms involves Havix Group Inc., Senores’ United States subsidiary operating pharmaceutical manufacturing facilities in Atlanta, Georgia. Havix plans to increase annual capacity from 1.2 billion units to 2 billion units through an estimated ₹18 crore investment. The 800-million-unit addition represents an approximately 66.7% increase over the currently disclosed capacity.
In India, Apnar Pharma Private Limited will undertake a larger proportional expansion at its manufacturing facility in Vadodara, Gujarat. The subsidiary plans to increase annual capacity from 500 million units to 1.2 billion units, adding 700 million units at an estimated cost of ₹20 crore. This represents a 140% increase in its existing disclosed manufacturing capacity, making Apnar the most aggressive of the two projects in percentage terms.
Together, these facilities would have nominal annual capacity of approximately 3.2 billion units following the proposed investments, compared with 1.7 billion units currently. The combined increase of 1.5 billion units represents approximately 88.2% capacity growth. These are aggregate manufacturing unit counts across two facilities, however, and should not be interpreted as identical or interchangeable pharmaceutical output across every formulation and dosage form.
The third investment involves Ratnatris Pharmaceuticals Private Limited, which is adding a prefilled-syringe manufacturing line with capacity for approximately 2.7 million units annually. The estimated investment is ₹5 crore, bringing the three disclosed projects to a combined ₹43 crore. Prefilled syringes represent a distinct pharmaceutical delivery format, so their manufacturing capacity should be assessed separately from the larger-volume production increases at Havix and Apnar.
Senores expects the proposed expansions to be completed by the end of March 2027. The disclosure identifies internal accruals and initial public offering proceeds as the intended financing sources for the Havix and Apnar capacity additions. The announced expenditure therefore represents a defined manufacturing investment programme, although the company has not provided product-level revenue forecasts or expected returns specifically attributable to the three projects.
Why is Senores Pharmaceuticals expanding production when existing facilities are operating at only 50% to 70% utilisation?
The disclosed capacity utilisation range introduces an important commercial question behind the expansion strategy. Senores indicated that existing utilisation at the Havix and Apnar facilities is approximately 50% to 70%, suggesting that the manufacturing network retains unused nominal capacity before the proposed additions. Unlike an expansion undertaken at a plant operating close to its maximum output, this investment appears to be based substantially on expectations for future product commercialisation and customer demand.
Pharmaceutical manufacturing capacity cannot always be evaluated through a single aggregate utilisation figure. Different products may require specific production lines, batch sizes, validation procedures, packaging formats or regulatory approvals. A facility can therefore report unused overall capacity while facing constraints in the manufacturing lines required for particular products, although Senores has not disclosed the detailed line-by-line bottlenecks behind the latest programme.
The company’s expanding portfolio provides some evidence supporting a forward-looking capacity decision. Senores reported 64 approved abbreviated new drug applications, or ANDAs, covering 207 product strengths at the end of September 2026. Only 23 of those ANDAs, representing 54 strengths, had been commercialised, leaving a substantial number of approved applications awaiting market introduction.
Additional manufacturing capacity could help Senores accommodate the planned launches without relying exclusively on its existing production configurations. It may also provide flexibility when negotiating contract development and manufacturing relationships with pharmaceutical customers. However, regulatory approval of a product does not establish its eventual sales volume, market share or manufacturing profitability.
The company’s decision consequently creates a distinction between production readiness and commercial demand. The additional facilities could improve its ability to support a larger product portfolio, but higher installed capacity may initially reduce overall utilisation percentages unless manufacturing volumes increase alongside commissioning.
The most relevant measure will be the actual output and profitability achieved after the expansion becomes operational. Senores’ ability to match product launches with customer orders, market access and efficient production scheduling will determine whether the 88.2% increase in aggregate manufacturing capability translates into corresponding commercial growth.
What do Senores Pharmaceuticals’ Q2 FY27 results reveal about revenue growth, profitability and operating leverage?
Senores delivered its highest reported quarterly revenue and EBITDA during the three months ended 30 September 2026. Consolidated revenue from operations increased 24.9% year on year to ₹192.3 crore from ₹153.9 crore. EBITDA rose approximately 38.3% to ₹57.7 crore from ₹41.7 crore, exceeding revenue growth and lifting the EBITDA margin to 30% from 27.1%.
The approximately 290-basis-point improvement in operating margin indicates stronger operating profitability during the period. Gross margin increased to 65.4% from 62.9%, suggesting an improvement in the relationship between revenue and direct production costs. The results support the commercial value of Senores’ product mix and regulated-market activities, although the precise contribution of individual products to the improvement was not separately disclosed.
Consolidated profit after tax increased from approximately ₹30.1 crore to ₹36.6 crore, representing growth of about 22%. Profit growth was therefore slower than EBITDA growth, despite the stronger operating performance. Depreciation increased from ₹8.1 crore to ₹10.3 crore, finance costs rose from ₹6.2 crore to ₹8.8 crore, and other income declined from ₹13.2 crore to ₹8.9 crore.
These movements help explain why higher operating profitability did not translate into an equivalent increase in net earnings. The reported profit after tax margin moderated from approximately 19.5% to 19%, even as the EBITDA margin expanded. The divergence is relevant because Senores is entering another investment cycle in which additional fixed assets and financing commitments could affect future depreciation and interest expenses.
The first-half results demonstrated a stronger cumulative operating trend. Revenue increased 30% to ₹372.5 crore, while EBITDA rose 58.2% to ₹111.4 crore. The first-half EBITDA margin reached 29.9%, compared with 24.6% in the corresponding period of FY26.
Profit after tax increased to ₹67 crore from ₹51.3 crore, representing growth of approximately 31%. This was a meaningful improvement, although still below the rate of EBITDA expansion. The company’s ability to sustain the operating margin while managing financing costs and investment expenditure will influence how much of its expected revenue growth reaches the bottom line.
Why is Senores Pharmaceuticals’ regulated-market business central to the manufacturing expansion strategy?
Regulated markets have become the principal source of revenue and earnings for Senores Pharmaceuticals. During Q2 FY27, regulated-market revenue increased 27.9% year on year to ₹136.7 crore from ₹106.9 crore. The business generated approximately 71% of consolidated revenue during the first half of FY27, making it the dominant contributor to the group’s operating performance.
The regulated-market segment reported first-half revenue of ₹264.5 crore, an increase of 34.3% from ₹196.9 crore. Management disclosed an EBITDA margin of approximately 42% for the business during the period, substantially above the consolidated EBITDA margin of 29.9%. The margin differential reflects the commercial importance of Senores’ regulated-market pharmaceutical portfolio and its potential contribution to consolidated profitability.
The emerging-market business also expanded, although at a lower margin. Revenue increased 21.2% during the September quarter to ₹38.4 crore, while first-half revenue rose 25.3% to ₹76 crore. Management reported an EBITDA margin of approximately 9% for emerging markets during the first half.
The difference between the two segments means that the geographical and product composition of future revenue can materially affect group earnings. Additional sales from regulated-market products with favourable manufacturing economics could contribute more strongly to EBITDA than an equivalent increase in lower-margin segments. Conversely, a shift towards products or channels carrying higher distribution, compliance or development costs could limit incremental margin benefits.
The manufacturing investments at Havix and Apnar are particularly relevant to the regulated-market strategy because both facilities support production capabilities for international pharmaceutical markets. Their commercial contribution will depend on the products manufactured, applicable regulatory requirements, customer commitments and pricing arrangements.
The strategic opportunity is broader than producing additional units. Senores is attempting to combine pharmaceutical product development, manufacturing capacity and access to distribution channels in regulated markets. Successful integration across these activities could strengthen its earnings profile, but the benefits depend on product-level execution rather than installed manufacturing capacity alone.
Can Senores Pharmaceuticals convert 64 approved ANDAs and its expanding product pipeline into stronger manufacturing demand?
Senores’ regulated-market product portfolio has expanded rapidly over the past year. The number of approved ANDAs increased from 34 at the end of September 2025 to 64 at September 2026, representing an increase of approximately 88%. The current approvals cover 207 individual product strengths, including products already commercialised and those awaiting launch.
Of the 64 approved ANDAs, 23 had been commercialised by the end of September 2026. The remaining 41 approved ANDAs correspond to 153 product strengths that had not yet been launched, according to the company’s investor presentation. This creates a meaningful commercialisation pipeline, although individual product strengths should not be treated as independent drug approvals.
During Q2 FY27, Senores commercialised three additional strengths under existing ANDAs and obtained approval for one new ANDA and three supplemental ANDAs. The company also reported a development pipeline comprising 41 molecules with 130 unique strengths. That pipeline represents potential future products at different stages of development rather than an already approved or revenue-generating portfolio.
Management expects to commercialise 13 ANDAs covering 41 strengths through the United States government channel during the second half of FY27. If those launches proceed as anticipated, they could increase manufacturing requirements and help absorb existing and additional capacity. Actual revenue will depend on product availability, procurement arrangements, order volumes and pricing.
Senores has also expanded its contract development and manufacturing activities. The company reported 19 commercialised partner ANDAs with 46 corresponding strengths at the end of September 2026, compared with 13 ANDAs and 16 strengths a year earlier. This business provides another route through which manufacturing capacity can support external pharmaceutical customers rather than solely the company’s own product portfolio.
The interaction between owned products and third-party manufacturing is central to the expansion economics. Owned products may provide differentiated commercial opportunities, while contract manufacturing can support production volumes and capacity utilisation. The profitability of each arrangement depends on its contractual structure, manufacturing complexity and customer economics.
How could Zoraya Pharmaceuticals and Amerisyn change Senores’ access to the United States pharmaceutical market?
Senores is also developing distribution capabilities that could increase its access to customers in the United States. Its investment in Zoraya Pharmaceuticals LLC is intended to strengthen direct commercialisation through established sales and distribution channels. The business represents a move towards greater participation in downstream marketing rather than relying entirely on conventional third-party arrangements.
Separately, Amerisyn LLC provides Senores with a strategic joint venture platform focused on United States federal pharmaceutical procurement. The venture is intended to pursue opportunities involving government purchasing arrangements, including channels serving veterans and defence-related healthcare requirements. These channels have specific procurement, contractual and compliance requirements, making participation different from ordinary commercial pharmaceutical distribution.
The initiatives could improve Senores’ ability to commercialise products manufactured through its existing United States and Indian facilities. However, access to a distribution platform or eligibility to participate in procurement programmes does not guarantee contract awards, product demand or a particular level of revenue.
Management indicated that Zoraya and Amerisyn were expected to begin contributing to revenue during the second half of FY27, with a broader ramp-up anticipated over the following 12 months. The company also stated that initial setup and operating expenditure associated with these initiatives affected EBITDA before corresponding revenue contributions emerged.
This creates a useful test for the next two reporting periods. If the new channels generate meaningful sales, Senores could demonstrate that its commercial expansion is supporting the manufacturing investment programme. If revenue development is slower than anticipated, the group may continue carrying additional operating expenditure while waiting for the distribution businesses to scale.
The financial significance will therefore depend on actual product launches, customer acquisition and profitable order fulfilment. Distribution access and increased manufacturing capacity are complementary investments, but the eventual commercial return requires both to operate effectively.
Does Senores Pharmaceuticals have sufficient financial flexibility to fund the ₹43 crore expansion alongside its broader investment programme?
Senores plans to fund the announced capacity additions through internal accruals and IPO proceeds, according to its exchange disclosure. The company’s latest investor presentation shows that ₹418.83 crore of the ₹500 crore allocation under its revised IPO proceeds utilisation schedule had been used by 30 September 2026. The remaining ₹81.17 crore was allocated to specified outstanding objectives rather than representing unrestricted cash available for any purpose.
Among the unutilised allocations were ₹23.32 crore for Apnar’s existing manufacturing expansion at Vadodara and ₹17.48 crore for expansion of Havix’s oral solid dosage manufacturing facility in Atlanta. These allocations are relevant to the latest capacity programme, although the disclosed IPO funding categories should not automatically be counted as additional investments on top of the newly announced ₹43 crore. The relationship between the allocations and project expenditure must be assessed within the company’s funding disclosures.
At 30 September, consolidated borrowings stood at approximately ₹394.5 crore, comprising ₹212.9 crore of non-current borrowings and ₹181.6 crore of current borrowings. This compared with total borrowings of approximately ₹327.1 crore at the end of March 2026. The increase of roughly ₹67.4 crore indicates that financial liabilities expanded during the first half of FY27 as Senores continued investing in its business.
Cash and cash equivalents declined to ₹18 crore from ₹45.6 crore over the same period. Other bank balances stood at ₹82.7 crore, although their availability and intended use should not be assumed to be identical to unrestricted operating cash. The group also reported total equity of approximately ₹1,031.5 crore at September 2026, compared with ₹964.5 crore in March.
Operating cash generation provides a more direct measure of the relationship between earnings and funding requirements. Senores reported ₹38.5 crore of cash generated from operations before income tax during H1 FY27, compared with ₹31.4 crore a year earlier. After income tax payments, net cash generated from operating activities stood at ₹29.2 crore, against ₹24.2 crore during H1 FY26.
The improvement in cash generation was positive, but it remained considerably below the ₹67 crore of reported first-half profit after tax. Working capital movements absorbed ₹84.7 crore during the period, compared with ₹43.5 crore in the previous year. Net cash used in investing activities reached ₹112.2 crore, while financing activities generated a net inflow of ₹55.4 crore.
These figures show that Senores is funding several stages of business development simultaneously, including manufacturing investment, product development and commercial expansion. The ₹43 crore capacity programme is modest relative to the group’s overall asset base, but its returns must be considered alongside continuing expenditure on regulatory filings, acquisitions and new distribution initiatives.
What does the September 2026 USFDA inspection at Apnar Pharma mean for its planned capacity increase?
Regulatory compliance remains an essential consideration for pharmaceutical manufacturing facilities supplying regulated markets. Senores disclosed that the United States Food and Drug Administration completed an inspection of Apnar Pharma Private Limited’s Vadodara facility between 7 and 11 September 2026. The inspection concluded with one minor procedural observation related to good manufacturing practices, according to the company’s notification.
Senores stated that Apnar would submit its response within the stipulated timeframe. The disclosure did not establish the final closure of the observation, and an inspection’s completion should not be confused with a separate regulatory determination on every future manufacturing activity.
The latest investor presentation identifies Apnar as a manufacturing business serving regulated markets, with existing approvals and infrastructure capable of supporting additional dosage-form manufacturing. Its proposed capacity expansion therefore sits within an established regulated manufacturing operation rather than a newly created pharmaceutical facility.
Nevertheless, additional manufacturing lines require appropriate qualification, validation and regulatory compliance before products can be supplied to applicable markets. Construction completion does not automatically establish commercial readiness for every product intended to use expanded capacity.
For Senores, the manufacturing programme’s success will depend partly on the ability to maintain regulatory compliance while introducing additional production capabilities. Progress on product qualifications and the absence of material compliance-related disruption would support the intended commercial ramp-up.
Why did Senores Pharmaceuticals shares decline 14.4% despite rising profits and new capacity investments?
Senores shares experienced substantial selling pressure during the final two trading sessions of October. The stock closed at ₹1,219.20 on the National Stock Exchange of India on 29 October, down approximately 7.9% from the previous close of ₹1,324.30. It declined another 7% on 30 October to close at ₹1,133.90, producing a cumulative two-session fall of approximately 14.4%.
The decline occurred around the publication of the Q2 FY27 financial results and the manufacturing expansion announcement, but the available evidence does not establish that the announcements alone caused the movement. The stock had traded at substantially higher levels earlier in the year, leaving its valuation sensitive to changing expectations about earnings growth and the timing of future commercial returns.
At the 30 October close, Senores had a market capitalisation of approximately ₹5,220 crore. The shares were roughly 29% below their August 2026 52-week high of about ₹1,599, although they remained substantially above their March low of approximately ₹706. The recent decline therefore occurred after a period in which the stock had delivered considerable gains over a longer investment horizon.
Trading activity also increased materially. Approximately 23.17 lakh shares changed hands on the National Stock Exchange during the 30 October session, compared with roughly 10.74 lakh shares on 29 October. The higher turnover indicates unusually concentrated trading activity around the reporting period, but it does not establish a uniform interpretation of the company’s prospects among market participants.
The operational results present competing considerations. Revenue growth, improved gross margins and stronger EBITDA support the argument that Senores’ regulated-market strategy is producing commercial progress. At the same time, net profit growth lagged operating earnings growth, borrowings increased and operating cash generation remained below reported profit.
The manufacturing expansion adds another dimension because existing utilisation has not yet approached full nominal capacity. A larger production base could support additional product launches and customer relationships, but it also increases the importance of converting approved products into sustainable manufacturing demand.
The share-price reaction does not establish that the expansion is commercially unattractive. It indicates that improving financial results and additional capacity commitments have not been sufficient to prevent a sharp near-term decline in the equity valuation. A stronger investment case would require evidence that the company’s growing portfolio can sustain earnings, cash flow and returns on deployed capital.
Can Senores Pharmaceuticals achieve its FY27 growth guidance while expanding manufacturing and commercial operations?
Senores management has maintained an FY27 outlook for revenue growth of approximately 30% to 40% and profit after tax growth of 50% to 60%. The targets are supported by expectations for additional regulated-market product launches, expansion of commercialisation channels and contributions from newly established businesses. They remain management forecasts rather than assured financial outcomes.
The first-half performance provides partial support for those targets. Revenue increased 30%, reaching the lower end of the annual growth guidance, while profit after tax rose approximately 31%. Achieving the higher full-year profit growth target would require a stronger contribution during the second half, supported by improved sales, product mix, operating leverage or other earnings factors.
Management has indicated that the second half of FY27 is expected to be considerably stronger than the first, partly because of anticipated product commercialisation and contributions from Zoraya and Amerisyn. The company also continues to invest in research and development, with R&D expenditure amounting to approximately 11% of first-half revenue. These activities support the future product pipeline but also require ongoing financial commitments.
The planned March 2027 completion of the manufacturing expansions introduces a separate timeline. Capacity additions commissioned near the end of the financial year may have limited opportunity to contribute significantly to FY27 revenue. Their larger commercial impact could emerge in subsequent reporting periods, depending on commissioning, regulatory requirements and the pace of customer demand.
The near-term earnings outlook should therefore be assessed primarily through the existing manufacturing base, approved-product launches and commercial distribution initiatives. The new capacity programme could reinforce the following phase of growth, but the relationship between capital expenditure and incremental earnings will become clearer only after production volumes and utilisation are disclosed.
Senores Pharmaceuticals has delivered substantial revenue growth, stronger operating margins and a considerably larger approved-product portfolio, creating a credible basis for expanding its manufacturing capabilities. The ₹43 crore investment will nearly double the combined nominal unit capacity at Havix and Apnar, while adding a separate prefilled-syringe production line through Ratnatris. However, the simultaneous increase in manufacturing capacity, commercial commitments and borrowing requirements makes disciplined execution essential to preserving profitability.
The next measurable test will be the company’s third-quarter FY27 results, particularly regulated-market revenue, commercialised product additions, EBITDA margins and net operating cash flow. Progress towards the proposed March 2027 capacity completion and the anticipated launches through United States government channels will provide further evidence of whether manufacturing expansion is aligned with commercial demand. A sustained improvement in cash conversion alongside higher product sales would strengthen the growth thesis, while slower launches or weaker operating cash generation would challenge the expected returns from the larger production network.
Key takeaways from Senores Pharmaceuticals’ ₹43 crore capacity expansion, Q2 FY27 earnings and share-price decline
- Senores Pharmaceuticals Limited announced ₹43 crore of planned manufacturing investments across three subsidiaries in the United States and India on 29 October 2026.
- Havix Group Inc. plans to increase annual capacity from 1.2 billion to 2 billion units through an estimated ₹18 crore investment.
- Apnar Pharma Private Limited intends to expand capacity from 500 million to 1.2 billion units at an estimated cost of ₹20 crore.
- Ratnatris Pharmaceuticals Private Limited is adding a separate prefilled-syringe line capable of producing 2.7 million units annually, at an estimated cost of ₹5 crore.
- Existing capacity utilisation of approximately 50% to 70% makes product commercialisation and demand conversion central to the expansion’s economics.
- Consolidated Q2 FY27 revenue increased 24.9% to ₹192.3 crore, while EBITDA grew approximately 38% to ₹57.7 crore and operating margin reached 30%.
- The regulated-market business contributed approximately 71% of first-half revenue, supported by an expanded portfolio of 64 approved ANDAs.
- Borrowings increased to approximately ₹394.5 crore at September 2026, while first-half net cash from operating activities reached ₹29.2 crore.
- Senores shares declined approximately 14.4% across the 29 and 30 October trading sessions, despite stronger reported quarterly earnings.
- The next catalysts include third-quarter results, additional product commercialisation, contributions from United States distribution ventures and progress towards March 2027 commissioning targets.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.