

Hudbay Minerals Inc. and Mitsubishi Corporation have approved construction of the Copper World project in Arizona, marking a significant investment decision for a planned major new US copper mine. The project carries an estimated initial capital requirement of $2.07 billion and targets first production in the second half of 2029, with Hudbay expecting its consolidated annual copper production to approximately double as the development reaches planned operating levels.
The announcement, released on October 21, 2026, follows completion of definitive feasibility studies covering project economics, production expectations and development requirements. Copper World is 70% owned by Hudbay Minerals and 30% owned by Mitsubishi Corporation, positioning the Japanese conglomerate as a strategic financial and development partner.
Why Hudbay Minerals’ Copper World project could double copper production and reshape its long-term growth outlook
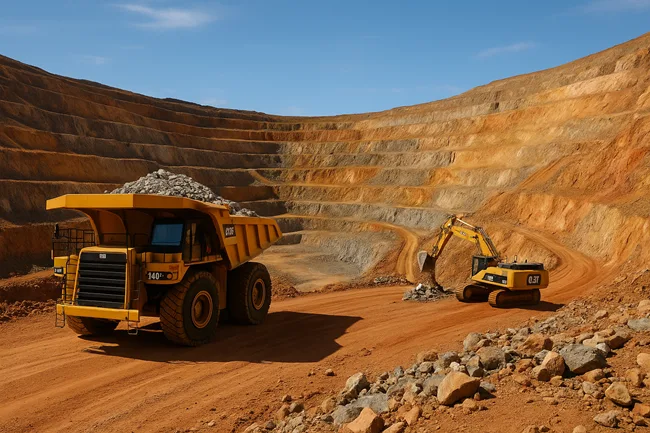
Copper World is located approximately 50 kilometres southeast of Tucson, Arizona, and is designed to become a substantial new source of domestically produced copper. According to Hudbay Minerals, the operation is expected to deliver average annual copper production of 102,000 tonnes during its first 10 years, representing an 11% improvement over the 92,000 tonnes projected in the company’s 2023 pre-feasibility study. The development could increase Hudbay’s consolidated annual copper output to approximately 250,000 tonnes when combined with growth initiatives at its existing operations.
The project’s definitive feasibility study outlines a base-case operating life of 15 years, supported by proven and probable mineral reserves of approximately 390 million tonnes grading 0.47% copper. An extended development scenario could potentially support operations for 37 years, although that outcome would require additional permitting and development activities involving federal lands. These longer-term possibilities provide Hudbay with an opportunity to establish a multidecade copper production platform in the United States.
The production profile also reflects planned operational expansion. Copper World is expected to begin with a processing capacity of 60,000 tons per day, increasing to 90,000 tons per day in its fifth year. This expansion could lift average annual copper production from approximately 84,000 tonnes during the first five years to 120,000 tonnes between years six and 10. The higher processing capacity is particularly important because it would allow Hudbay to generate additional output from the same mining complex without developing an entirely separate operation.
How Mitsubishi Corporation’s $600 million investment reduces Hudbay Minerals’ financial exposure
One of the most consequential elements of the Copper World announcement is the project’s financing structure. Although initial development capital is estimated at $2.07 billion, Hudbay Minerals expects its direct contribution to total approximately $500 million, representing less than one-quarter of the initial capital requirement. This structure significantly reduces the financial burden that would otherwise fall on Hudbay shareholders.
Mitsubishi Corporation’s $600 million initial equity investment provides a substantial portion of the required funding. The financing plan also incorporates a $230 million precious metals streaming deposit from Wheaton Precious Metals Corp. and approximately $650 million in anticipated project-level debt financing. Remaining equity contributions from Hudbay and Mitsubishi are expected to be deferred until 2028, giving Hudbay additional time to generate cash flow from its existing operations.
The company has also strengthened its financing flexibility by arranging an extension of its senior secured revolving credit facilities from November 2028 to November 2030, alongside an increase in available commitments to $700 million. The amended facilities are expected to close during the fourth quarter of 2026. Together, these measures could help Hudbay manage construction spending, existing debt obligations and potential fluctuations in commodity prices without placing excessive pressure on its balance sheet.
Nevertheless, the funding plan is not entirely free of execution risk. The anticipated project debt financing must still be secured, while construction costs and development timelines remain exposed to inflation, equipment availability and other operational uncertainties. Investors will therefore need to assess whether the company’s projected financing contributions remain achievable as construction progresses.
What Copper World’s $1.2 billion valuation and projected earnings mean for Hudbay Minerals investors
The Copper World feasibility study provides investors with several measures for assessing the project’s potential profitability. Under the base case, assuming a long-term copper price of $5 per pound, the project carries an estimated after-tax net present value of $1.2 billion using an 8% discount rate. The corresponding internal rate of return is projected at 17%, suggesting that the operation could generate meaningful economic value if development and production assumptions are achieved.
The economics become considerably more attractive under a higher copper-price scenario. At $6 per pound, the project’s base-case after-tax net present value increases to approximately $2.3 billion, while the internal rate of return rises to 22%. This sensitivity highlights both the potential upside associated with stronger copper markets and the importance of commodity prices to the project’s long-term investment case.
Hudbay also projects average annual earnings before interest, taxes, depreciation and amortization of approximately $661 million during the first decade of production under the $5-per-pound copper scenario. At $6 per pound, that estimate rises to approximately $859 million annually. These projections indicate that Copper World could become a major contributor to the company’s consolidated earnings, although they represent feasibility-study forecasts rather than guaranteed financial results.
Operating costs will be another important factor. Hudbay estimates average cash costs of approximately $1.65 per pound during the first decade, potentially positioning Copper World competitively among US open-pit copper operations. If the company achieves those costs while maintaining planned production levels, the mine could generate substantial operating margins under the copper-price assumptions used in the study.
The broader strategic importance extends beyond Hudbay’s individual financial performance. Copper remains essential for electricity transmission, renewable energy infrastructure, electric vehicles, industrial equipment and data-center development. Expanding domestic copper production could help strengthen US supply-chain resilience at a time when governments and manufacturers are increasingly focused on access to critical minerals.
How Hudbay Minerals stock is responding and what institutional investors should watch next
Hudbay Minerals shares traded higher during Wednesday’s session following the Copper World announcement. The company’s New York Stock Exchange-listed shares were quoted at approximately $23.82 as of 11:53 a.m. Eastern Time, representing a gain of roughly 0.7% from the previous closing price of $23.66. The relatively modest advance suggests that investors were responding positively but had not immediately assigned a dramatic valuation premium to the construction approval.
The broader share-price backdrop is also relevant. Hudbay shares have experienced volatility during October, reflecting the influence of copper prices, commodity-market sentiment and expectations surrounding future production growth. The Copper World approval provides a clearer development pathway, but investors must still consider the multiyear period before commercial production begins.
From an institutional investment perspective, the announcement strengthens Hudbay’s long-term growth narrative by converting a major development opportunity into an approved construction project. The Mitsubishi partnership also provides external validation of the project’s strategic importance while distributing financial exposure across multiple funding sources. However, institutional sentiment cannot be conclusively established from a single trading session, particularly without updated fund-flow or ownership disclosures.
Several milestones will determine whether that constructive outlook translates into sustained shareholder value. These include securing anticipated project financing, maintaining construction budgets, completing the planned processing expansion and demonstrating that production costs remain consistent with feasibility-study estimates. Investors will also monitor copper-price trends because the project’s valuation and projected cash generation are particularly sensitive to the metal’s long-term pricing environment.
Key takeaways: Hudbay Minerals’ $2.07 billion Copper World project signals major US copper production expansion and long-term growth potential
- Hudbay Minerals and Mitsubishi Corporation approved construction of the $2.07 billion Copper World project in Arizona.
- First copper production is targeted for the second half of 2029.
- Average annual production is projected at 102,000 tonnes during the first decade.
- Hudbay’s consolidated copper output could approximately double to 250,000 tonnes annually.
- Mitsubishi’s initial investment totals $600 million, reducing Hudbay’s direct funding burden.
- Hudbay expects to contribute approximately $500 million toward initial development.
- The base-case after-tax project valuation reaches $1.2 billion at $5-per-pound copper.
- Average annual project EBITDA could reach $661 million during the first decade under base-case assumptions.
- Construction execution, financing and copper prices remain key investor considerations.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.