Austal Limited (ASX: ASB) closed 7.1% higher at A$4.66 on September 9 after U.S.-based Wildcat Infrastructure submitted a non-binding proposal valuing Austal USA at US$1.25 billion to US$1.35 billion, above the US$1.05 billion to US$1.20 billion range previously proposed by South Korea’s Hanwha. The competing interest arrives only days after Austal reported a A$53.6 million FY26 net loss caused by a A$202.8 million U.S. segment EBIT loss, while its Australasian operation produced record A$85.3 million EBIT and now has more than A$5 billion of contracted work. Wildcat has requested four weeks of due diligence and intends to retain the Austal brand while operating the U.S. business as a standalone platform. With Austal’s entire equity market value around A$1.9 billion, investors now face an unusual question: how much value could remain in the Australian-listed company if a buyer pays a premium price for the division currently responsible for most of its reported losses?
Why did Austal shares jump 7.1% after the Wildcat proposal?
Wildcat’s proposal immediately improved Austal’s negotiating position because it sits above the Hanwha range at both ends.
The U.S. infrastructure investor has indicated an enterprise value of US$1.25 billion to US$1.35 billion for Austal USA on a cash-free and debt-free basis. Hanwha had previously proposed US$1.05 billion to US$1.20 billion and was already conducting due diligence after the Austal board determined that its approach warranted further evaluation.
The difference is commercially meaningful. Wildcat’s minimum is US$50 million above the top of Hanwha’s range, while its US$1.35 billion upper end is US$150 million higher. The presence of a second bidder also creates the possibility that Hanwha revises its proposal rather than allowing an important U.S. defence-industrial asset to move to a rival buyer.
ASB reached A$4.74 during September 9 trading before closing at A$4.66, up from A$4.35 on September 8. Trading volume increased to approximately 3.8 million shares, and the stock finished at its highest close since August.
The shares remain far below their 52-week high of A$8.82 and are down around 30% during 2026. That history explains why a proposal for the U.S. business can drive a strong one-day rally without returning Austal anywhere close to the valuation it commanded before the FY26 U.S. contract provisions became visible.
Why would buyers want Austal USA after a A$203m EBIT loss?
The FY26 loss reflects contract accounting problems rather than the absence of valuable strategic assets.
Austal USA generated A$1.383 billion of revenue during FY26, more than two-thirds of group revenue. Its EBIT loss of A$202.8 million was driven largely by non-cash provisions associated with onerous shipbuilding contracts after the U.S. Department of War did not agree to accelerated contractual relief.
Austal is pursuing the formal contractual process to recover additional costs. The company says its position is supported by a documented factual and contractual record, although investors should not assume full recovery until settlements or binding determinations actually occur.
Underneath those problem contracts sits a shipyard with capabilities that are increasingly scarce in the United States.
Austal USA builds Offshore Patrol Cutters for the U.S. Coast Guard, auxiliary vessels for the U.S. Navy and modules for Virginia and Columbia-class nuclear submarines. It also supports existing Expeditionary Fast Transport and Littoral Combat Ship fleets.
The Module Manufacturing Facility 3 expansion is scheduled for completion in December 2026. The facility is already partially operational and, when fully commissioned, is expected to support approximately 1,000 jobs while expanding Austal’s ability to manufacture nuclear submarine modules.
That industrial capacity is becoming more valuable as the United States attempts to expand naval shipbuilding and submarine production. Buyers are consequently looking beyond FY26 accounting losses toward the strategic value of an established yard, trained workforce, customer relationships and defence clearances that are difficult to replicate quickly.
How does the Wildcat offer compare with Austal’s current valuation?
Austal had approximately 420 million shares outstanding according to current market data. At A$4.66, that places the company’s equity value around A$1.9 billion.
Contemporary Australian-dollar estimates place Wildcat’s US$1.25 billion to US$1.35 billion proposal at roughly A$1.7 billion to A$1.9 billion.
The comparison is striking but needs care. Wildcat is offering an enterprise value for Austal USA on a cash-free, debt-free basis, while Austal’s quoted market capitalisation is an equity value for the entire listed group. Taxes, transaction costs, transferred liabilities, working capital, retained cash and the precise perimeter of the sale would determine how much value ultimately remains available to shareholders.
Austal also cannot simply distribute the headline consideration and continue unchanged. Selling Austal USA removes approximately A$1.38 billion of annual revenue, significant shipbuilding infrastructure and long-term U.S. defence opportunities.
What remains, however, is economically attractive in its own right.
Australasia generated A$650.7 million of FY26 revenue and record EBIT of A$85.3 million. Revenue increased 49%, while EBIT rose 137%, producing a much healthier earnings profile than the consolidated FY26 result suggests.
A transaction therefore has the potential to convert a complex group dominated by U.S. contract provisions into a smaller Australian-focused defence shipbuilder with substantial net cash and a record order book, depending on the eventual sale terms.
How valuable is Austal Australasia without the US business?
The Australian operation has undergone a significant strategic transformation.
Austal is the Commonwealth’s Strategic Shipbuilder for key Tier 2 naval vessels in Western Australia. Its Australasian order book now exceeds A$5 billion and spans a 12-year build programme, providing visibility far beyond the normal horizon available to commercial shipbuilders.
The company secured a A$1.029 billion contract for 18 Landing Craft Medium vessels and an approximately A$4 billion contract for eight Landing Craft Heavy vessels. It also received more than A$285 million of additional Evolved Cape-class Patrol Boat work during FY26.
Austal expects construction across the landing-craft programmes to continue well into the 2030s. Management believes existing and expected contracts create a pathway to doubling Australasian revenue during the next five years.
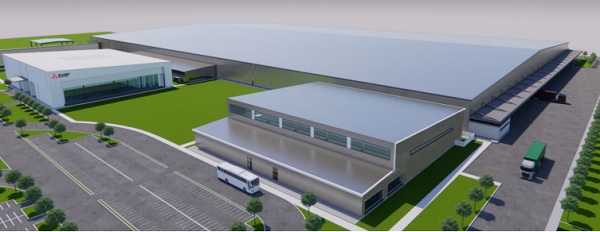
There is additional upside from the proposed Mogami-class General Purpose Frigate programme. Negotiations with Mitsubishi Heavy Industries have begun, although Austal currently expects any contract signing to progress toward FY29 rather than treating the programme as existing backlog.
This distinction is important for valuation. The more than A$5 billion order book is contracted activity, while future frigates represent potential work that should not be valued at the same certainty level until agreements are signed.
Even without that optionality, the retained Australasian business would start from an unusually strong position: record EBIT, multi-year sovereign shipbuilding work and a strategic agreement with the Australian government designed to support continuous naval construction.
Could a bidding contest force Hanwha to improve its offer?
Hanwha enters the situation with a strategic advantage and a strategic complication.
The South Korean defence group already owns 19.9% of Austal and has spent years seeking deeper involvement with the company. Its industrial capabilities across shipbuilding, aerospace and defence make Austal USA an obvious strategic fit as Hanwha tries to expand within the U.S. defence market.
Wildcat’s proposal changes the price benchmark.
Hanwha’s existing US$1.05 billion to US$1.20 billion range is now below Wildcat’s US$1.25 billion minimum. Unless Hanwha identifies material differences in transaction certainty or other terms that make its proposal superior despite a lower price, the Austal board has an incentive to investigate Wildcat’s offer thoroughly.
Wildcat itself still has substantial work to complete. The proposal is non-binding and conditional on four weeks of due diligence, meaning there is no certainty it becomes a binding transaction at the headline valuation.
Regulatory approval is another consideration. Austal USA operates highly sensitive U.S. defence programmes, including nuclear submarine work, making ownership and security approvals particularly important. A domestic U.S. buyer could potentially face a different regulatory pathway from a foreign strategic acquirer, although the actual approval requirements depend on the final transaction structure.
For shareholders, the favourable outcome is competition rather than dependence on any one bidder. Two credible parties examining the business create more information about its standalone value and may improve Austal’s ability to negotiate price and transaction protections.
Does Austal have enough financial strength to wait for a better deal?
The balance sheet gives the board some flexibility rather than forcing an immediate sale.
Austal ended June with A$311.9 million of cash and a net cash position of A$186.3 million. By July 31, cash had improved to A$366 million and net cash to approximately A$240 million.
The company also had A$435 million of undrawn debt facilities.
Those resources are important because Austal is executing a substantial expansion programme. FY26 capital expenditure reached A$352.7 million compared with A$194.9 million in the previous year, with spending concentrated on U.S. facilities including Final Assembly 2 and Module Manufacturing Facility 3.
Operating cash flow was only A$62.5 million during FY26, down from a prior year inflated by one-time MMF3 funding receipts. The company therefore remains capital intensive despite the net cash balance.
Austal did not declare an FY26 dividend because the board chose to retain capital for growth. A sale of Austal USA could dramatically alter that capital-allocation question, depending on the amount of net cash received and the investment needs of the remaining Australian business.
Investors should consequently avoid assuming that all sale proceeds would immediately be returned. The board would need to consider taxes, working capital, debt, expansion spending and the optimal capital structure of the retained company before determining any distribution.
What could prevent Austal shareholders from receiving the headline bid value?
The largest risk is transaction certainty.
Wildcat’s approach is only a non-binding indication of interest and remains subject to four weeks of due diligence. The final offer could be reduced, restructured or withdrawn if the buyer identifies liabilities or contract risks that alter its valuation.
The U.S. contract claims create another uncertainty. A buyer will need to determine how the potential recoveries and future losses associated with onerous programmes are allocated between seller and purchaser. Those negotiations could materially affect the amount of value Austal receives even if the enterprise-value headline remains unchanged.
Regulatory approvals and national-security requirements could also influence the process. Austal works on some of the most strategically sensitive naval programmes in both Australia and the United States, making a straightforward commercial M&A timetable less likely than for an ordinary industrial company.
The final risk is opportunity cost. Austal USA may currently report losses, but it also owns scarce shipbuilding infrastructure exposed to growing U.S. naval spending. Selling today transfers the future upside from those facilities to the buyer, so the board needs a price that compensates shareholders for both the current problems and the long-term strategic value.
Austal stock key takeaways after the Wildcat proposal
- Austal closed 7.1% higher at A$4.66 on September 9 after Wildcat Infrastructure offered US$1.25 billion to US$1.35 billion for Austal USA.
- Wildcat’s range is above Hanwha’s existing US$1.05 billion to US$1.20 billion proposal at both ends, increasing the possibility of competitive tension.
- Austal USA generated A$1.383 billion of FY26 revenue but reported a A$202.8 million EBIT loss, largely because of provisions associated with onerous U.S. shipbuilding contracts.
- Australasia generated record EBIT of A$85.3 million on A$650.7 million of revenue, with revenue up 49% and EBIT up 137%.
- The Australasian order book exceeds A$5 billion and includes Landing Craft Medium and Landing Craft Heavy programmes stretching well into the 2030s.
- Austal had approximately A$240 million of net cash at July 31 and A$435 million of undrawn debt facilities, reducing pressure to accept a transaction solely for short-term liquidity.
- Wildcat’s four-week due-diligence period, any response from Hanwha and the eventual treatment of U.S. contract liabilities are the next measurable catalysts for ASB shareholders.
What would strengthen or weaken the Austal investment case from here?
The investment case would strengthen if Wildcat converts its approach into a binding offer near the upper end of the US$1.25 billion to US$1.35 billion range or if Hanwha responds with improved economics. Greater competition would help establish that Austal USA’s strategic shipyard value is considerably higher than the losses currently dominating the consolidated financial statements.
A transaction would become especially compelling if Austal can transfer the problematic U.S. contracts while retaining a large net cash balance and the full value of its Australasian operations. The more than A$5 billion Australian order book and A$85.3 million FY26 EBIT would then become the starting point for valuing a dramatically simplified listed group.
The thesis would weaken if due diligence results in a materially lower Wildcat valuation, if neither bidder proceeds to a binding proposal or if transaction liabilities consume a much larger share of the consideration than investors currently expect. Continued U.S. contract losses would become particularly damaging if Austal remains the owner after the sale process fails.
ASB’s 7.1% September 9 gain reflects something more significant than takeover speculation alone. A second bidder has provided another external valuation for the division responsible for most of Austal’s current earnings volatility.
The next four weeks could therefore reshape the entire investment case. If competition produces a premium sale of Austal USA, investors may be left with a well-funded Australian defence shipbuilder supported by more than A$5 billion of contracted work. If the proposals fail to become binding, shareholders return to the much harder task of waiting for U.S. contract recoveries and operational profitability to repair the value themselves.
Discover more from Business-News-Today.com
Subscribe to get the latest posts sent to your email.